Someone using a phone to look up the difference between a check routing number and account number.

Check Routing vs Account Number: Differences Explained

The difference between a check routing and account number is that the routing number identifies the bank, while the account number reflects the specific checking account you hold.

If you’re looking for your bank routing and account numbers, they are likely easier to find than you may think: You can locate them on your checks or by logging into your financial institution’s app, for instance.That said, you probably don’t want to broadcast these digits to too many people, as they are sensitive financial details, used for everything from direct deposit to money transfers. Learn more about these digits and how to use and protect them.

Key Points

•   A routing number is a nine-digit code that identifies a bank or credit union.

•   An account number is a unique identifier for your specific bank account.

•   Routing numbers are used for various financial transactions like direct deposit, bill pay, and wire transfers.

•   Account numbers are private and should be kept secure to prevent fraud.

•   You can find your routing and account numbers on checks, through online banking, in-app, or by contacting your bank.

🛈 If you’re looking for the SoFi routing number, you can find it here: SoFi routing number.

What Is a Routing Number?

A routing number is a sequence of nine digits that identifies a bank or credit union, and each banking institution has a unique number. Here are some facts about routing numbers and how they work:

•   A routing number is also sometimes referred to as an ABA number, in reference to the American Bankers Association, which assigns them. Routing numbers are only issued to federal or state-chartered financial institutions that are eligible to maintain an account at a Federal Reserve Bank.

•   Your bank’s routing number and ACH routing number may or may not be the same digits. Check with your bank to be sure.

•   The routing number required for making a wire transfer may often differ from the routing number that is printed on your checks. That number can be found online or by contacting your bank.

•   A small bank may only have one routing number, while a larger financial institution may have several (they typically vary by state). An online bank, which operates without physical branches, will typically have one routing number.

Purpose of a Routing Number in Banking

The purpose of a routing number is to identify the financial institution that is responsible for the payment and ensure that funds are sent to the right place in a financial transaction.

Routing numbers are generally required when reordering checks, paying bills, setting up direct deposit, or making tax payments. Making sure you have the right digits can help ensure smooth transactions.

What Is an Account Number?

While the routing number identifies the financial institution where your account is held, the bank account number represents your specific account. While anyone can find your bank’s routing number, your account number is private; that’s a key difference in routing vs. account numbers. Here are some other points about account numbers to consider:

•   Typically between eight and 12 digits, your account number acts as a road map of sorts for your bank, letting them know where to deposit or withdraw money, whether that’s a checking account or a savings account.

•   If you have two different accounts at the same financial institution, you will have two different account numbers. The routing number for these accounts, however, will be the same.

•   Because your account number can unlock access to the funds in your checking or savings account, it’s critical that you keep it safe.

Role of an Account Number in Transactions

Whether you are receiving a paycheck, making online purchases, or setting up autopay, your account number plays a key role. While routing numbers identify your bank, account numbers ensure that money is correctly credited to or debited from the right bank account.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

When You Need a Routing Number vs Account Number

There are many times when you may need a routing number vs. account number for everyday financial transactions. These may include:

•   Setting up direct deposit of your paycheck

•   Setting up autopay

•   Setting up direct deposit of Social Security or other government benefits

•   Paying a bill by online banking

•   Setting up autopay

•   Check processing

•   Sending or receiving a wire transfer

•   Sending up a peer-to-peer payment app or service

•   Transferring funds between accounts at different banks

•   Making payments from your bank account by phone

•   Ordering new checks

•   Linking a budgeting app to your bank account

Recommended: 10 Benefits of Direct Deposit

Finding Your Check Routing and Account Number

If you need to find your routing and account numbers, you likely have several options, from looking at a physical check to logging in to your banking app:

How to Find the Routing vs Account Number on a Check

You can find your routing vs. account number on a check, printed on the bottom.

You’ll see three groups of numbers (often separated by spaces and/or symbols). Typically, reading left to right, the first number (nine digits) is the routing number; the next group of numbers (usually eight to 12 digits) is the account number; the third is the actual check number.
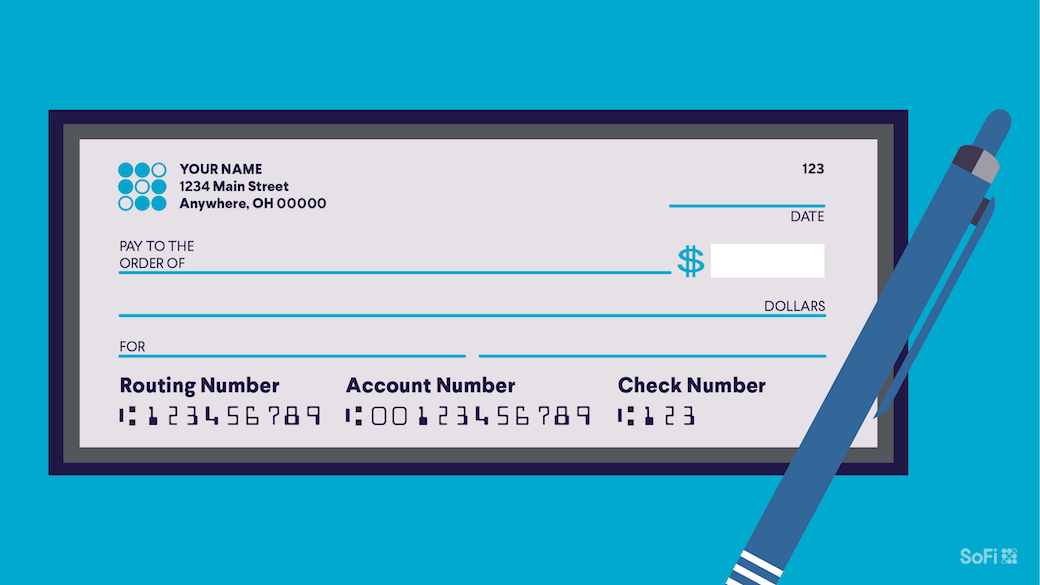
check image with numbers

Contacting Your Bank

If you need to find your routing number and account numbers and don’t have access to a check, you can call your bank (or stop into a branch) and ask a customer service representative to provide you with the numbers. Since your account number is private information, you will likely have to provide identifying details to verify your right to gain access to this number.

Note: If all you need is the routing number, you can easily find it on your bank’s website.

Accessing Your Online Account

If you log in to your bank account online or in-app, you should be able to get your banking details. Your account number may be encrypted (meaning you can only see the last four digits). If that’s the case, you can typically get the full number by downloading a recent bank statement. Or there may be a prompt you can click in order to see the full number.

Recommended: Checking Account vs Debit Card: What’s the Difference?

Protecting Your Routing and Account Numbers

Although anyone can locate your bank’s routing number, your account number is not public information. Just as you are probably mindful about who sees your Social Security number, the same goes for your bank account number. You want to try to make sure that someone doesn’t use your bank account and routing number without authorization, which can be a form of bank fraud.

Tips for Keeping Your Banking Information Secure

Here are some ways to help keep sensitive banking information safe:

•   Avoid sharing your banking details unless necessary. To protect yourself from potential bank fraud, you generally don’t want to share your account number with any person or business unless you absolutely need to. Also wise: not sharing pictures of checks you’ve written on social media, even if it is for the first payment on your dream car.

•   Store physical checks in a secure place. Since checks contain both your routing and account number, it’s a good idea to keep your checkbook tucked away in a safe place, not sitting out in the open. Also, if you void a check or are getting rid of old checks and paper statements, it can be wise to shred these documents before throwing them away.

•   Enable multi-factor authentication (MFA) for online banking. Two- or three-factor authentication requires additional information beyond a password — such as a code sent to your mobile phone or a fingerprint scan — for account access. You’ll typically find this option inside the account settings.

•   Regularly monitor your accounts. It’s a good idea to review your bank statements monthly and check your online banking once a week. This can help you to pick up on any suspicious transactions and nip any potential issues in the bud.

Recommended: How to Sign a Check Over to Someone Else

What to Do if Your Information Is Compromised

Here are smart steps to take if you suspect fraud or unauthorized access to your bank account:

•   Contact your bank immediately. Call customer service and inform the representative of any unauthorized banking transactions as soon as you notice them.

•   Change your login credentials: It’s a good idea to choose a new (unique) password for your bank account. Also consider setting up multi-factor authentication if you haven’t already.

•   Review your recent transactions: Comb through recent activity on your bank account and make a list of any transactions you don’t recognize, noting the date and details. You’ll typically need this information to file a dispute with your bank.

•   Consider placing a fraud alert on your credit report: You can contact any one of the three credit bureaus — Equifax®, Experian®, and TransUnion® — to place a fraud alert on all three of your credit reports. A fraud alert is free and notifies creditors to take extra steps to verify your identity before extending credit.

The Takeaway

A check routing number indicates the bank where your account is held, while an account number identifies your specific account at that bank. Routing and account numbers work together to identify your account and ensure that your money gets transferred from the right place or that you receive funds intended for you. Knowing the difference between these numbers, where to locate them, and how to protect them can be vital to managing your finances securely.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Do you need both a routing and account number for a wire transfer?

Typically, yes. Transactions like wire transfers require both a routing and account number. The routing number identifies your bank, while the account number specifies your individual account. Together, they ensure that funds are correctly withdrawn from the right institution and account.

What comes first on a check, the routing or account number?

Typically, when you look at the lower portion of a check (reading left to right), you’ll see the routing vs. account number first, followed by the account number, and then the actual check number.

The routing number is a nine-digit code that identifies the bank, while the account number indicates your specific account within that bank. Checks are typically numbered to help with record-keeping.

Which number do I provide for direct deposit?

For a direct deposit, you generally need to provide both your routing and account numbers. The routing number ensures the deposit is sent to the correct bank, while the account number directs the funds to your specific account. You may also be asked to provide a voided check.

What happens if you use the wrong routing or account number?

Using the wrong check routing number and/or account number can result in a failed transaction or funds being sent to the wrong account. If your bank catches the mistake, it may reject the transaction. If your bank misses it and the account number belongs to someone else, the money could get deposited into the wrong account. If that occurs, you’ll want to contact your bank immediately to try to remedy the problem.

Are routing numbers the same across all bank branches?

Not necessarily. Smaller banks often have a single routing number for all branches. But if a bank has branches located in different states, routing numbers usually won’t be the same across all branches. Your routing number will typically be based on the branch where you first opened your account.


Photo credit: iStock/SeventyFour


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.

SOBNK-Q426-148

Read more
Someone holding a piggy bank.

Pay Yourself First Budgeting Method: Strategy Explained

Budgeting can be key to financial success, but with so many strategies available, it can feel overwhelming. One simple approach is the pay-yourself-first method. What pay yourself means is turning traditional budgeting upside down by prioritizing saving and financial goals before addressing everyday expenses. In other words, instead of saving what’s left over at the end of the month, you save first — and spend what’s left after.

Whether you’re working toward building an emergency fund, saving for a house, or investing for retirement, you may want to consider the pay-yourself-first strategy. Here’s a closer look at how pay-yourself-first budgeting works and how to put it into practice.

Key Points

•   Pay-yourself-first budgeting involves prioritizing savings before expenses.

•   The method is designed to help build consistent saving habits.

•   To get started you’ll need to assess your current income and spending and possibly trim nonessential spending.

•   Automating savings is a way to save consistently and automatically without even thinking about it.

•   Seeing savings and investment accounts grow may help those who use this method stay motivated.

3 Reasons to Pay Yourself First

What pay yourself first means is to prioritize savings over spending when creating a budget. Here are some reasons why individuals might want to adopt this method that’s sometimes referred to as “reverse budgeting.”

1. To Save Consistently

One of the biggest benefits of the pay-yourself-first budget is that it could create a consistent saving habit. Consider this: Many people intend to save whatever money remains at the end of the month, only to find that there isn’t much — or anything — left.

By paying yourself first, you’re removing the temptation to spend that money. It becomes a non-negotiable — just like your rent or electric bill. You commit to putting aside a set amount each month into a savings account or investment account, treating your future self as a priority. Over time, these small contributions may accumulate into a sizable savings or investment fund, providing financial stability and peace of mind.

2. To Prepare for the Future

Financial emergencies are almost inevitable. Whether it’s a car repair, medical bill, or trip to the vet, unplanned expenses can derail even the most careful budgets. Paying yourself first helps you build a safety net by starting an emergency fund before life throws a curveball.

Beyond emergencies, the pay-yourself-first strategy may also help you work toward long-term financial goals. Whether you’re hoping to buy a home, travel, or fund a child’s education, prioritizing savings makes it easier to achieve big-picture plans without relying on debt. And while retirement may seem a long way off, the sooner you start saving, the more time your money potentially has to grow through compound returns (when returns start earning returns of their own).

3. To Stay Motivated

Budgeting can feel restrictive and discouraging, particularly when the main focus is on cutting expenses and limiting spending. Paying yourself first changes that mindset. Instead of seeing what you’re giving up, you focus on what you’re gaining when you save — a savings account that’s growing and/or a bigger retirement fund, and real progress toward your goals.

Each month that you pay yourself first may be considered another step forward. That sense of progress may inspire you to stay on track, stick with your budget, and look for even more ways to improve your financial well-being.

Recommended: 50/30/20 Budget Calculator

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

How to Start Paying Yourself First

If the idea of paying yourself first sounds appealing, here’s a simple step-by-step guide to getting started.

1. Assess Your Income and Spending

Before you can determine how much to pay yourself, you’ll need to get a sense of your overall financial picture. You can do this by gathering up the last several months of financial statements to calculate your average monthly income and spending.

Next, you’ll want to categorize your monthly expenses and divide the list into essential spending (like housing, utilities, groceries, debt payments) and nonessential spending (dining out, entertainment, clothing).

Once you have a clear picture of your income and expenses, you can start identifying how much room there is to pay yourself first. Keep in mind that the goal here is to prioritize saving as if it were an essential bill.

2. Determine How Much to Pay Yourself

How much money you should save each month depends on your income, expenses, and goals. A good starting point may be 10% to 20% of your take-home pay, but don’t be discouraged if that feels out of reach at first. Even saving 5% is better than nothing, and you can gradually increase the percentage as your financial situation allows.

To hone in the right amount to pay yourself, you’ll want to consider your short- and long-term financial goals, how soon you want to reach them, and how much you’ll need to save monthly to meet those goals.

If saving for multiple goals feels too overwhelming, you could prioritize. For example, If you don’t have a solid emergency fund, you might start there. To determine how big it should be you can use an emergency fund calculator. Once that’s in place, you might bump up your 401(k) contributions and/or start saving for another goal like a down payment on a home or car or your next vacation. The key is to start somewhere and commit to regular contributions.

3. Trim Unnecessary Expenses

If your current spending habits don’t leave much room for saving, you’ll need to find some places to cut back on spending. The easiest way to find extra money is to look closely at your nonessential spending and consider what you can live without.

Some areas where people tend to overspend include:

•   Eating out or ordering takeout frequently

•   Subscriptions and streaming services

•   Unused gym memberships

•   Impulse purchases or retail therapy

Redirecting even $50 or $100 per month from nonessential spending into savings could make a big difference over time. Trimming the fat in your spending not only eliminates waste, but also helps you start spending with more intention, rather than making decisions impulsively or passively. Like other budgeting methods, such as zero-based budgeting, the pay-yourself-first strategy helps ensure that your spending aligns with your values and goals.

4. Review Your Bank Accounts

To successfully pay yourself first, you need the right banking set-up. It’s generally a good idea to have multiple bank accounts to separate your savings from your everyday spending. This prevents the temptation to dip into savings for nonessential expenses.

At a minimum, you’ll want to have one checking account that doesn’t charge any monthly fees (bonus if it also earns some interest), along with at least one savings account that pays a competitive annual percentage yield (APY). To help grow your savings faster, you may want to open a high-yield savings account at a bank or online bank. These accounts offer significantly higher APYs compared to traditional savings accounts.

5. Automate Your Savings

Once you’ve decided how much to pay yourself each month and where to put those payments, automating your savings is the next step. By setting up automatic transfers from your checking account to your savings accounts, you eliminate the need to make a decision each month. It happens behind the scenes — just like a bill payment.

Consider setting your transfer to occur on the same day you receive your paycheck. This ensures the money is moved before you have a chance to spend it elsewhere. Alternatively, you might see if your employer will do a split direct deposit, where most of your paycheck goes into your checking account and a certain percentage goes directly into savings.

6. Review and Adjust Based on Your Goals

Life is constantly changing, and your personal budget should typically reflect that. It’s generally a good idea to periodically review your financial goals, income, and spending habits to make sure your savings strategy still aligns with your priorities. You might set a reminder in your calendar to review your budget every three to six months, for example. You’ll also likely want to go over your budget whenever you experience a major life change (like a new job, move, or marriage).

Some questions to consider when doing a budget review:

•   Am I meeting my savings goals and saving money fast enough?

•   Can I afford to increase how much I pay myself?

•   Are there any expenses I can reduce or eliminate?

•   Have my financial goals changed?

Adjustments are normal and necessary. The key is to remain proactive and intentional with your money. As your income increases and/or debt decreases, look for opportunities to boost your savings rate and pay yourself even more if you can.

The Takeaway

The pay-yourself-first strategy isn’t simply a budgeting method — it’s a shift in mindset that puts your financial well-being front and center. By prioritizing savings before spending, you can potentially build a habit of consistency, prepare for the future, and stay motivated as you work toward your goals.

This approach to budgeting is also typically easy to implement. To get started, you assess your income and expenses, decide how much to pay yourself based on your financial goals, cut unnecessary expenses to free up savings, and automate your savings to stay consistent.

Remember that it’s fine to start small. Over time, you’ll likely gain momentum and confidence, and those early efforts may pay off in the form of more financial flexibility and greater peace of mind.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Are there any disadvantages to paying yourself first?

While paying yourself first may be a powerful savings strategy, it can present challenges if your income is irregular or your monthly expenses are high. Automatically transferring money into savings before covering essentials could cause cash flow issues, especially during emergencies or months with unexpected costs. Prioritizing savings without a flexible plan might also lead to relying on credit cards or loans to make ends meet. It’s important to balance saving with realistic budgeting to avoid financial strain.

What types of accounts are best for paying yourself first?

High-yield savings accounts, retirement accounts, and investment accounts are some types of accounts individuals might wish to consider for the paying yourself first method. For example, high-yield savings accounts generally offer easy access and better interest rates than traditional savings accounts, potentially making them a place to save cash for short-term goals. Retirement accounts may provide tax advantages for long-term saving. Individuals will want to choose their accounts based on their specific goals, time horizon, and tolerance for risk.

How does paying yourself first help with financial stability?

Paying yourself first may help build financial stability by prioritizing savings before spending. The idea is that a person who uses this budgeting strategy would consistently set aside money for emergencies, future goals, and retirement, rather than relying on leftover funds. Over time, pay yourself first might help create a financial cushion that reduces stress, prepares an individual for unexpected expenses, and lessens the need for high-interest debt. Ideally, the approach may also help build long-term financial security.

Can I still pay myself first if I have debt?

It’s possible to pay yourself first even if you have debt, but whether it makes sense to do so generally depends on your specific situation and the type of debt you have. Building savings, even a small emergency fund, might prevent further debt when unexpected expenses arise. However, if you have high-interest debt, you may want to prioritize repaying that first to help reduce the amount of interest you’ll pay. You could eventually put the money you save on interest charges into savings.

What are the biggest challenges of paying yourself first?

One of the biggest challenges of paying yourself first is sticking to the habit, especially when money feels tight or unexpected expenses arise. People with irregular incomes may also find it challenging to divert a set amount of money to savings each month. To overcome these hurdles, they might choose to start small by saving a smaller amount whenever they can.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOBNK-Q426-149

Read more
overhead view of businessman working, looking at business charts and graphs

What Is the Wash-Sale Rule?

A wash sale occurs when an investor sells a stock or other security at a loss and, within 30 days before or after the sale, buys or acquires the same or a “substantially identical” security. The wash-sale rule is an Internal Revenue Service (IRS) regulation that generally prevents investors from deducting losses on these transactions immediately for tax purposes.

Investors may sell securities at a loss as part of a tax strategy called tax-loss harvesting, which involves using investment losses to offset capital gains. However, if they repurchase the same or a substantially identical security within the wash-sale window, they may not be able to claim the loss as a tax deduction when they expect to.

Understanding the wash-sale rule can help investors account for potential tax consequences when selling securities at a loss.

Key Points

•   The wash-sale rule disallows claiming tax losses if you buy the same or a substantially identical security within 30 days before or after the sale.

•   This regulation generally applies to stocks, bonds, mutual funds, ETFs, and options transactions across your taxable and retirement accounts.

•   Disallowed losses in taxable accounts are typically added to the cost basis of the replacement security, deferring the tax benefit until it is sold.

•   Purchasing replacement securities inside an IRA can result in permanently losing the tax deduction for the original loss.

•   To avoid triggering a wash sale, investors can wait at least 31 days before repurchasing or invest in non-substantially identical assets like broader ETFs.

Which Investments are Subject to the Wash-Sale Rule?

The wash-sale rule applies to most common stocks and securities, including:

•   Stocks

•   Bonds

•   Mutual funds

•   Exchange-traded funds (ETFs)

•   Options and certain other contracts to acquire securities

The rule can also apply to purchases made in an individual retirement account (IRA) or Roth IRA, as well as purchases made by a spouse. Certain securities futures contracts may also be subject to the rule.

The wash-sale rule generally does not apply to commodity futures or foreign currency trades. It also does not apply to sales of securities at a profit. For example, if an investor sells a stock at a gain and buys the same stock within 30 days, the transaction does not trigger a wash sale.

What Happens When You Trigger a Wash Sale?

Investors may sell securities at a loss as part of a tax-loss harvesting strategy, or they may decide to repurchase a security after selling it during a market downturn. The wash-sale rule is intended to prevent investors from claiming a tax deduction for a loss while maintaining substantially the same position in the security.

If an investor triggers a wash sale, the loss generally cannot be deducted immediately or used to offset capital gains on that year’s tax return. Instead, the disallowed loss is typically added to the cost basis of the replacement security, which can defer the tax benefit until the replacement security is sold.

There is an important exception: If an investor sells a security at a loss in a taxable account and purchases a substantially identical security in an IRA or Roth IRA within the wash-sale window, the loss is disallowed, but it generally is not added to the IRA’s cost basis. This means the tax benefit may be permanently lost.

The wash-sale rule can also apply if one spouse sells a security at a loss and the other spouse purchases a substantially identical security within the applicable window.

Understanding these rules can help investors account for potential tax consequences when making investment decisions. Investors with questions about how the wash-sale rule applies to their circumstances may want to consult a tax professional.

Avoiding a Wash Sale

The best way to avoid a wash sale is to understand how the rule applies to your transactions and keep track of purchases and sales across your accounts, whether you use a traditional brokerage or prefer online investing. The IRS generally considers a security a wash sale if you sell it at a loss and purchase or acquire the same or substantially identical security within 30 days before or after the sale.

Because the IRS does not provide a simple, universal definition of what makes two securities substantially identical, determining whether a particular transaction triggers a wash sale can be complicated. Investors who use tax-loss harvesting may want to review their transactions carefully and consult a tax professional when they’re unsure about a potential wash sale.

What to Do After Selling an Asset at a Loss

One straightforward way to avoid a wash sale is to wait at least 31 days after selling a security at a loss before purchasing the same or a substantially identical security.

Alternatively, an investor might choose to purchase a different security that provides similar, but not substantially identical, market exposure. However, determining whether two securities are substantially identical can be difficult, so investors may want to consult a tax professional before making the transaction.

Selling a security at a loss can potentially help investors offset capital gains and, subject to applicable limits, some ordinary income. However, if an investor wants to repurchase the same security shortly after selling it, the wash-sale rule may affect the timing or tax treatment of the transaction.

In some cases, selling stock in one corporation and purchasing stock in another corporation may not trigger a wash sale. Similarly, selling a company’s stock and purchasing its bonds may not trigger the rule. However, the tax treatment depends on the specific securities and transaction.

Investing in ETFs or Mutual Funds Instead

Investors who want to maintain exposure to a particular industry or market segment after selling a security at a loss may consider purchasing a different ETF or mutual fund.

For example, an investor who sells an individual technology stock at a loss might consider purchasing a diversified technology ETF. Because the fund holds multiple securities rather than just the stock that was sold, it may not be considered substantially identical to the individual stock. However, this is not a guarantee that the transaction will avoid a wash sale. The IRS considers whether securities are substantially identical, and the analysis depends on the specific investments involved.

Switching between two ETFs or mutual funds can also be complicated. Funds that track the same index or have nearly identical holdings may raise wash-sale concerns, even if they have different names or expense ratios.

Investors considering these transactions may want to review the funds’ underlying holdings and consult a tax professional before making a decision.

Wash-Sale Penalties and Benefits

If a transaction qualifies as a wash sale, the investor generally cannot deduct the disallowed loss immediately to reduce taxable income or offset capital gains. However, when a replacement security is purchased in a taxable account, the disallowed loss is generally added to its cost basis. This adjustment can defer the tax benefit until the replacement security is sold.

For example, suppose an investor purchases 10 shares of a stock for $1,000 and later sells them for $800, realizing a $200 loss. If the investor purchases 10 substantially identical shares for $850 within the wash-sale window, the $200 loss is disallowed.

The investor’s cost basis in the replacement shares becomes $1,050 ($850 purchase price + $200 disallowed loss). If the investor later sells the replacement shares for $1,200, the taxable capital gain would generally be $150 rather than $350, assuming no other adjustments apply.

The holding period of the original security is also generally added to the holding period of the replacement security. This may affect whether a future gain or loss is classified as short-term or long-term for tax purposes.

The treatment differs when the replacement security is purchased in an IRA or Roth IRA. In that case, the disallowed loss generally is not added to the IRA’s cost basis, so the tax benefit may be permanently lost.

The Takeaway

The wash-sale rule applies when an investor sells a stock or other security at a loss and buys or acquires the same or a substantially identical security within 30 days before or after the sale. The rule generally prevents investors from deducting the loss immediately, although the disallowed loss may be added to the cost basis of a replacement security in a taxable account.

Understanding the wash-sale rule can help investors account for potential tax consequences when selling securities at a loss. Because the rule can apply across multiple accounts and involves some uncertainty about what qualifies as substantially identical, investors may want to consult a tax professional when planning transactions.

Tax considerations are one part of managing an investment portfolio, and understanding how different transactions may affect a tax return can help investors make more informed decisions.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

How do I avoid a wash sale?

To avoid a wash sale, you need to wait at least 31 days after selling a security at a loss before purchasing the same or a substantially identical security. You can also consider purchasing a different security that provides similar market exposure but is not substantially identical. Keep in mind that the wash-sale rule applies across relevant accounts, including taxable accounts and IRAs, and can also apply to purchases made by a spouse. Since wash-sale rules can be complicated, you may want to consult a tax professional.

What is the wash-sale rule in the IRS?

The IRS wash-sale rule generally prevents investors from deducting a loss on a security if they purchase or acquire the same or a substantially identical security within 30 days before or after selling it at a loss. The rule is intended to prevent investors from claiming tax deductions for losses while maintaining substantially the same investment position. In a taxable account, the disallowed loss is generally added to the cost basis of the replacement security.

What happens if I sell a wash-sale stock?

If you sell a stock at a loss and trigger the wash-sale rule, you generally cannot deduct the loss immediately on your tax return. If you purchase the replacement stock in a taxable account, the disallowed loss is typically added to its cost basis, which may reduce a future taxable gain or increase a future deductible loss. However, if you purchase the replacement security in an IRA or Roth IRA, the loss generally cannot be added to the account’s cost basis.

What is the downside of a wash sale?

The main downside of a wash sale is that you may not be able to deduct an investment loss when you expected to. In a taxable account, the tax benefit is generally deferred until you sell the replacement security. If you purchase a substantially identical security in an IRA or Roth IRA, the loss may be permanently disallowed. Wash sales can also complicate tax reporting and make it more difficult to plan transactions around tax-loss harvesting.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.

SOIN-Q426-082

Read more
Guide to Personal Loan Agreements

How to Write a Personal Loan Agreement

Your personal loan agreement is the document that contains everything you need to know about the deal you’re making with your lender, including your rights and responsibilities as well as theirs. It’s a fairly long and complex form, but breaking it down can make it easier to understand.

Here, take a closer look at personal loan agreements and how to draw up a personal loan agreement should you decide to do it yourself.

Key Points

•   A personal loan agreement outlines terms and conditions, providing legal protection for both the lender and the borrower.

•   Key elements include parties, loan amount, interest rate, repayment terms, default provisions, governing law, and signatures.

•   Steps to write a personal loan agreement include choosing to DIY or work with a lawyer, gathering details, agreeing on terms, listing payment and legal details, and signing.

•   Additional documents for loan approval typically include proof of identity, income verification, and proof of address.

•   A personal loan agreement is legally binding and enforceable in court if obligations are not met.

Personal Loan Agreements Defined

A personal loan agreement, as mentioned above, is a document that details exactly what is being agreed to on both sides of a personal loan: lender and borrower. At the very least, it will state how much money is being loaned and the terms and conditions of the borrower’s repayment responsibilities.

But what about a personal loan that is not with a traditional lender? Private lenders can be individuals or organizations that make loans to individuals, sometimes without the qualification requirements of traditional lending institutions. A private personal loan agreement is drafted as part of a private personal loan, one made between a private lender and a borrower.

Any personal loan agreement is a legally binding document, so it’s important to understand it in full before you apply your signature.

Key Elements of a Personal Loan Agreement

Say you’ve applied for a personal loan. If you qualify, you’ll move along to a personal loan agreement. Among the key elements of a personal loan agreement are:

•   Parties involved: These include the lender and borrower, including their legal names and addresses.

•   Loan amount: This is the amount of money being borrowed, also known as the principal.

•   Interest rate: This is typically expressed as an annual percentage rate (APR), which reflects the total cost of borrowing over a year. If you don’t understand APR vs interest rate differences, this is a good time to learn.

•   Repayment terms: These include how and when the loan will be repaid, including the payment schedule, payment frequency, and loan term.

•   Default provisions: These are the consequences of failing to make payments, such as late fees and potential actions the lender can take. Also, you may want to be sure severability clauses are spelled out, stating what happens if one aspect of the agreement is deemed unenforceable.

•   Governing law: This specifies which jurisdiction’s laws will govern the agreement in the event that there are disputes.

•   Signatures and date: These are needed from both the lender and borrower.

You might also include details on any loan collateral, late and early payment (prepayment) penalties, and guarantors or cosigners, as needed.

Secured vs Unsecured Personal Loans

Most personal loans are unsecured, meaning no collateral is required from the borrower. But at times, a personal loan can be secured by property, such as a car. Collateral can also be an asset such as a savings account or certificate of deposit. Collateral might be required if a borrower has a less-then-stellar credit score.

When a loan is secured with collateral, the lender can take possession of the collateral if the borrower fails to make their loan payments.

Why Is a Loan Agreement Needed?

A personal loan agreement is essentially a protective document. It protects both the lender and the borrower by laying out, in clear terms, exactly what is being agreed to. If either party fails to uphold the agreement, action can be taken — such as the lender seizing any assets offered as collateral or sending the account to collections — both of which, obviously, would be bad for the borrower.

But the document works both ways. Lenders, too, are subject to lender liability and can be taken to court if they fail to uphold their end of the loan agreement. Although these cases are far less common than borrower default, the loan agreement is a document that can be used for the borrower’s protection as well.

How to Write a Personal Loan Agreement in 5 Steps

If you’ve been wondering how to draw up a personal loan agreement, here are the usual steps:

1. Decide Whether to DIY It or Hire a Lawyer

Loan paperwork is often created by the lending institution. For private loans, depending on the specifics of your loan and situation, you could write up a simple agreement by hand or draft it on your computer and then print it out for signing if you are working toward a private loan. Or you might download a template from a reputable site, which can be a popular option. Both are often at no cost or sometimes a small fee.

However, if the loan is complicated or you don’t want to handle the agreement yourself, you could look into hiring a lawyer to draw up the paperwork. Either way, a personal loan agreement will be a legally binding arrangement. Hiring a lawyer will likely be a costlier proposition.

2. Gather the Necessary Personal Details

You will need the legal names and addresses of both parties. This ensures the lender can’t ask you for anything beyond the borrowed principal (plus interest, which will also be listed).

3. Agree to and Spell Out the Loan Terms

The loan agreement should list the payments that will be expected each month and the expected date of the conclusion of the loan term. You can use a personal loan calculator to see what the monthly amount should be.

The interest rate for the personal loan should also be on the personal loan agreement, likely expressed as an APR, which shows what percentage of the loan principal you’ll end up paying back in the course of one year, including interest and any additional fees that may be packaged into the loan. What is a high interest rate vs. a low one will depend on the market so keep an eye on published rates.

The interest rate will vary based on your credit score and other financial factors. If you have decent credit, you’ll likely be able to qualify for a personal loan. But generally speaking, the higher your score, the lower your rate.

Recommended: Personal Loans Glossary

4. List Payment and Legal Details

A personal loan agreement should also include the following, as noted above:

•   The loan agreement may list which types of payment are acceptable, such as check, bank transfer, or credit card.

•   The personal loan contract should also list specific repayment conditions, including when payment is due and whether or not additional principal can be applied without penalty.

•   A complete personal loan agreement should include details on how any disputes will be handled between the parties involved.

•   Some personal loan documents may include the option to change your loan’s term (the period over which the loan is repaid).

•   Personal loan contracts in the United States should stipulate which state’s laws will be used to govern and interpret the agreement if the borrower lives in a different state than the lender is headquartered.

•   The contract should have a severability clause that states that even if one part of a contract is found to be unenforceable or otherwise rendered null and void, the remainder of the agreement will still hold.

•   The contract should list any penalties associated with the personal loan, such as late fees that may be assessed, at what point the loan will go into arrears or default, or other scenarios.

5. Sign the Document

Finally, the contract for loaning money must be signed by the borrower and the lender in order to be made legally binding.

Recommended: Comparing Personal Loans vs Business Loans

Other Personal Loan Documents

Along with the signed personal loan agreement, other typical personal loan requirements include the following:

Proof of Identity

Your driver’s license or some equivalent form of photo ID will likely be necessary in order to verify your identity.

Income Verification

Lenders will consider your income when qualifying you for a loan. After all, they have good reason to be interested in whether or not you’ll be able to repay the debt. Along with asking you to list your annual income, verifying documents such as tax returns may also be required.

Proof of Address

In order to prove your residence, and therefore eligibility for any type of personal loan, you may need to provide utility statements, bank statements, or other official documents.

The Takeaway

If you’re considering a personal loan, reading the loan agreement in depth is a good way to understand for sure what you’re agreeing to. That loan agreement will contain many details about funds borrowed and how they will be repaid, and it serves to protect both the lender and the borrower.

Think twice before turning to high-interest credit cards. Consider a SoFi personal loan instead. SoFi offers competitive fixed rates and same-day funding. See your rate in minutes.

SoFi’s Personal Loan was named a NerdWallet 2026 winner for Best Personal Loan for Large Loan Amounts.

FAQ

Does a personal loan agreement need to be notarized?

No, a personal loan agreement does not need to be notarized to be legally binding. It simply needs to be signed by each party to the agreement.

What is a private personal loan agreement?

A private personal loan agreement is the binding legal contract between a borrower and a private lender for a personal loan. Depending on the specifics of your situation, this document can be written by hand, drafted on a computer, or created using a downloaded template.

Why do you need a loan agreement?

The personal loan agreement serves to outline the specific terms of the loan and protect both parties in case either fails to uphold the agreement. It establishes legally enforceable terms for the lender while safeguarding the borrower by ensuring the lender cannot demand payments beyond the agreed-upon principal, interest, and fees.

Can a personal loan agreement be legally enforced?

Yes, a written and signed agreement for a loan can be legally enforced. It’s a binding contract.

What happens if a borrower defaults on a personal loan agreement?

If a borrower defaults on a personal loan, they will face negative impacts on their credit score, potential legal action from the lender, and they might find that their account is turned over to collections. They might also be charged late fees and a higher interest rate on the remaining balance due.


Photo credit: iStock/Chaay_Tee


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

This article is not intended to be legal advice. Please consult an attorney for advice.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOPL-Q426-008

Read more
Comparing Personal Loans and Balance Transfer Credit Cards

Balance Transfer Credit Cards vs Personal Loans

Three ways to consolidate and pay off debt are a balance transfer credit card, a personal loan, or a combination of the two. Which option is best depends on the type and amount of debt you have and your ability to pay off that debt over time.

For instance, a balance transfer credit card might be a smart choice if you have good credit and debt across a few credit cards and are prepared to pay the debt off within the next 12 to 18 months. On the other hand, a personal loan might be better if you have multiple high-interest debts and need more time to pay them off.

Read on to learn more about the choice between a balance transfer or personal loan, how a personal loan works, the pros and cons of each option, and how to leverage the benefits of both.

Key Points

•   Balance transfer cards and personal loans are both ways to pay down debt, and you can use both simultaneously.

•   Balance transfer cards can allow you to pay down debt with no or low interest for a period of 12 to 18 months.

•   Personal loans can allow you to consolidate debt into a single, more convenient loan, often at more favorable rates.

•   Each option has its advantages and disadvantages, so research is recommended.

•   For some people, a combination of a balance transfer card and a personal loan will be the best way to deal with their debt.

What Is a Personal Loan?

A personal loan is a lump sum borrowed from traditional banks, credit unions, or online lenders that you agree to pay back over time, with interest. The borrower will make regular payments, usually on a monthly basis, to the lender over a fixed period of time until the loan is repaid.

Unlike many other types of loans, personal loans can be used for just about anything. Often, these loans are used to resolve short-term cash flow problems, cover unexpected expenses during an emergency, or pay for large expenses.

Personal loans for debt consolidation involve a borrower taking out a personal loan and using it to pay off balances on high-interest credit cards and other debts. Because personal loans typically have lower interest rates than credit cards, the borrower can potentially save money while paying off their debt.

Though there are different types of personal loans, they’re most often unsecured loans. This means they’re not backed by collateral as, say, a mortgage is backed by the borrower’s house. As such, the lender will usually assess your creditworthiness and financial situation when determining whether to approve you for the loan.

Recommended: Check Your Personal Loan Rate

What Is a Balance Transfer Credit Card?

A balance transfer credit card is a credit card that allows you to transfer balances from other accounts. Let’s say an individual has outstanding balances on three or four high-interest credit cards. They could transfer that debt to a balance transfer credit card that charges a lower or even 0% annual percentage rate (APR).

If a lower rate is offered, it will usually last for a limited period of time — 12 to 18 months is the norm. Should that person pay off their debt within that window, they could save money on interest and have all of their payments go directly toward paying down the principal. After the promotional period ends, however, the interest rate could be quite high, usually higher than the interest rate on a personal loan.

Recommended: Debt Consolidation Loan vs Personal Loan

Balance Transfer vs Personal Loan for Debt Consolidation

When deciding on either a balance transfer credit card or personal loan for debt consolidation, consider the level of debt you have and your capacity for monthly payments.

A balance transfer credit card might be the right choice if you’re confident you can pay off your debt within the low-APR introductory period. However, a personal loan might be the better choice if you find it difficult to resist spending on a credit card, or if you have debt that needs to be paid off over a longer period of time. Personal loans are also preferable if you want a fixed interest rate and would like to know ahead of time how much your monthly payment will be, as it’s going to be the same each month.

Either way, debt consolidation is often a good idea, as it can reduce the overall amount of interest that consumers pay and help clear debt more expediently.

Balance Transfer Credit Card vs Personal Loan

Balance Transfer Credit Card

Personal Loan

Types of Debt You Can Consolidate

•   Generally best for credit card debt

•   Good for multiple types of debt

Interest Rates

•   Can offer a lower intro APR, after which the rate will likely be higher than a personal loan

•   Generally a variable rate

•   Tends to have lower rates compared to credit cards

•   Typically a fixed rate

Fees

•   One-time balance transfer fee that’s usually 3% to 5% of the amount transferred

•   One-time origination fee ranging from 0% to 8% of the loan amount

Repayment Terms

•   Promo APR offers generally limited to 18-21 months

•   Can have terms up to 84 months or longer

Payments

•   Make only the minimum required payment

•   Fixed payments over a set period of time, with a predetermined payoff date

Credit Score Requirements

•   Generally need at least good credit (670+) to qualify

•   Better rates and terms reserved for those with good credit

Credit Score Impacts

•   Might increase credit utilization, which can negatively affect credit

•   Might lower your credit utilization, which can help credit

How to Decide Between a Balance Transfer and a Personal Loan

As you explore a balance transfer vs. personal loan, there are some important considerations. As noted above, if you don’t feel you can pay off your debt within the 12- to 18-month low-interest window that most balance transfer cards permit, you may want to pursue a personal loan. Consider the size of your debt and the amount you would be allowed to transfer to a balance transfer card. If you owe more than you can comfortably pay in a year, a personal loan could be the better option.

Do the Math to Compare Your Options

Restructuring debt with personal loans is quite common, and if you are thinking about taking this approach, you can use a personal loan calculator to compute the amount you would pay each month and your total interest paid over the life of the loan. For example, if you took out a $20,000 personal loan to settle your credit card debt and repaid that loan over 36 months at a rate of 8.00%, you would make a monthly payment of $627 and have a total interest payment of $2,562.

It can be more difficult to estimate the cost of paying off debt with a credit card, as rates change periodically. But if you are being offered a 0% APR balance transfer card, then you would need to look at any fees associated with the balance transfer (5% would not be unusual). If you transferred $20,000 onto a 0% APR card and paid a 5% fee, you would pay $1,000. At first, it might seem that the balance transfer option is more affordable. But this is only the case if you can pay off the entire balance before the 0% APR ends, because when it ends, you could face an interest rate of 18.00% or higher.

Pros and Cons of Personal Loans

Both balance transfer credit cards and personal loans can be good options depending on the amount and type of debt you have. If you need more than 12- to 18 months to pay off your debt, personal loans generally offer lower APRs. Personal loan terms vary, but it’s possible to borrow up to $100,000 and pay off the balance over several years.

However, your interest rate will also depend on your credit score — a low score can mean a high interest rate. It’s smart to compare a few personal loan rates to find the best offers.

Pros and Cons of Personal Loans for Debt Consolidation

Pros

Cons

Those with good credit can secure lower APRs. The interest rate may be high if you have bad credit.
Loans can be large enough to consolidate many types of debt. It could be a few years before your debt is fully paid off.
Budgeting is easier with fixed interest rates and monthly payments. There’s less flexibility in your monthly payments, as they’re fixed.
You can choose from different repayment terms. An origination fee may apply, which could be up to 8% of the loan amount.

Pros and Cons of Balance Transfer Credit Cards

If you have debt on only a few credit cards, a balance transfer credit card might allow you to save on interest while you pay it down. These cards can offer lower or even 0% APRs for a certain period of time, usually for 12 to 18 months. This gives you time to pay off the total balance transferred from other cards.

However, suppose you do not pay off the balance within that window. In that case, the interest rate could rise above the rate you were initially paying before you consolidated the amounts to your balance transfer credit card.

Pros and Cons of a Balance Transfer Credit Card for Debt Consolidation

Pros

Cons

You can get a low or 0% APR for an initial period, thus saving on interest. You need a good to excellent credit score to qualify.
Once your debt is paid off, you have an additional open credit line, which may boost your credit score. You may not be able to transfer the full amount of your debt to the card.
Some balance transfer credit cards offer rewards, points, or other perks. There may be a balance transfer fee, which generally is 3%-5% of the balance transferred.
You’ll have the flexibility to pay off as much as you’d like each month with no fixed payment schedule. If you don’t pay off your debt during the promo period, the interest rate may become higher than that of your initial debt.

Using A Balance Transfer Credit Card and a Personal Loan

It’s not always necessary to decide between a personal loan vs. balance transfer credit card. A third option for debt consolidation is to use both a personal loan and a balance transfer credit card. You could use a balance transfer credit card to pay off as much high-interest credit card debt as you can at a low APR. Then, you’d take out a personal loan to pay off the rest of your debt at a lower interest rate than what you’re currently paying.

To figure out how much of a personal loan to take out in this scenario, add up your total debt. Next, calculate how much you would have to pay each month in order to pay off your debt in full by the end of the promotional APR.

For example, if you had $4,000 in credit card debt and a 0% APR that lasted for 18 months, you’d have to pay about $222 each month. If you weren’t able to pay that much, you could consider applying for a personal loan to pay off the remaining amount.

The Takeaway

Three ways to proactively consolidate and pay off debt are to use a balance transfer credit card, a personal loan, or a combination of the two. In general, a balance transfer credit card is best for those with good credit and primarily credit card debt. Those with various types of debts and who need a structured debt payment plan may prefer a personal loan. A combination of both can suit a variety of situations.

Think twice before turning to high-interest credit cards. Consider a SoFi personal loan instead. SoFi offers competitive fixed rates and same-day funding. See your rate in minutes.

SoFi’s Personal Loan was named a NerdWallet 2026 winner for Best Personal Loan for Large Loan Amounts.

FAQ

What is a balance transfer loan?

A balance transfer is a credit card transaction whereby debt is moved from one account to another. These cards often offer a 0% introductory APR for 12 to 18 months, which means any balances moved to the card could potentially be paid off interest-free. The downsides are that there is often a balance transfer fee, and there may be a limit to the total amount you can transfer to the new card. Explore a balance transfer credit card vs. personal loan to determine which is the most affordable way to manage your debt.

Does a balance transfer hurt your credit?

It depends. Opening a new credit card and transferring all your other credit card balances to it could push your credit utilization ratio to its limit, which would hurt your credit score. Your score is also negatively affected from the hard inquiry that results from applying for a new card. However, if you use a balance transfer credit card wisely and pay off all of your higher-interest cards, that will lower your credit utilization ratio and build your score.

Is there a difference between a loan and a balance transfer?

Either a balance transfer or personal loan can be a way to consolidate debt, but they are not the same thing. A debt consolidation loan is where you take out a loan to pay off your existing debt, while a balance transfer allows you to move your existing debt onto one credit card. Each option has unique pros and cons and exploring a personal loan vs balance transfer is a key step in managing debt.

What credit score do you need for a balance transfer or personal loan?

A good to excellent credit score of 670 or higher is generally required for a balance transfer credit card that offers an attractive low interest rate. It may be possible to obtain a personal loan with a credit score of 580 or better.

How long does a balance transfer take to complete?

It’s not unusual for a balance transfer to a new credit account to take two to three weeks to be completed, though some transfers are accomplished in just a few days. How long a balance transfer takes will depend on several factors, including how many different banks or credit card companies you are transferring from and whether or not you are setting up a new credit account or using an existing one. During the transfer process, it’s important to keep tabs on your old and new accounts and to continue making any payments that are due.


Photo credit: iStock/PeopleImages


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOPL-Q426-005

Read more
TLS 1.2 Encrypted
Equal Housing Lender