Someone using a phone to look up the difference between a check routing number and account number.

Check Routing vs Account Number: Differences Explained

The difference between a check routing and account number is that the routing number identifies the bank, while the account number reflects the specific checking account you hold.

If you’re looking for your bank routing and account numbers, they are likely easier to find than you may think: You can locate them on your checks or by logging into your financial institution’s app, for instance.That said, you probably don’t want to broadcast these digits to too many people, as they are sensitive financial details, used for everything from direct deposit to money transfers. Learn more about these digits and how to use and protect them.

Key Points

•   A routing number is a nine-digit code that identifies a bank or credit union.

•   An account number is a unique identifier for your specific bank account.

•   Routing numbers are used for various financial transactions like direct deposit, bill pay, and wire transfers.

•   Account numbers are private and should be kept secure to prevent fraud.

•   You can find your routing and account numbers on checks, through online banking, in-app, or by contacting your bank.

🛈 If you’re looking for the SoFi routing number, you can find it here: SoFi routing number.

What Is a Routing Number?

A routing number is a sequence of nine digits that identifies a bank or credit union, and each banking institution has a unique number. Here are some facts about routing numbers and how they work:

•   A routing number is also sometimes referred to as an ABA number, in reference to the American Bankers Association, which assigns them. Routing numbers are only issued to federal or state-chartered financial institutions that are eligible to maintain an account at a Federal Reserve Bank.

•   Your bank’s routing number and ACH routing number may or may not be the same digits. Check with your bank to be sure.

•   The routing number required for making a wire transfer may often differ from the routing number that is printed on your checks. That number can be found online or by contacting your bank.

•   A small bank may only have one routing number, while a larger financial institution may have several (they typically vary by state). An online bank, which operates without physical branches, will typically have one routing number.

Purpose of a Routing Number in Banking

The purpose of a routing number is to identify the financial institution that is responsible for the payment and ensure that funds are sent to the right place in a financial transaction.

Routing numbers are generally required when reordering checks, paying bills, setting up direct deposit, or making tax payments. Making sure you have the right digits can help ensure smooth transactions.

What Is an Account Number?

While the routing number identifies the financial institution where your account is held, the bank account number represents your specific account. While anyone can find your bank’s routing number, your account number is private; that’s a key difference in routing vs. account numbers. Here are some other points about account numbers to consider:

•   Typically between eight and 12 digits, your account number acts as a road map of sorts for your bank, letting them know where to deposit or withdraw money, whether that’s a checking account or a savings account.

•   If you have two different accounts at the same financial institution, you will have two different account numbers. The routing number for these accounts, however, will be the same.

•   Because your account number can unlock access to the funds in your checking or savings account, it’s critical that you keep it safe.

Role of an Account Number in Transactions

Whether you are receiving a paycheck, making online purchases, or setting up autopay, your account number plays a key role. While routing numbers identify your bank, account numbers ensure that money is correctly credited to or debited from the right bank account.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

When You Need a Routing Number vs Account Number

There are many times when you may need a routing number vs. account number for everyday financial transactions. These may include:

•   Setting up direct deposit of your paycheck

•   Setting up autopay

•   Setting up direct deposit of Social Security or other government benefits

•   Paying a bill by online banking

•   Setting up autopay

•   Check processing

•   Sending or receiving a wire transfer

•   Sending up a peer-to-peer payment app or service

•   Transferring funds between accounts at different banks

•   Making payments from your bank account by phone

•   Ordering new checks

•   Linking a budgeting app to your bank account

Recommended: 10 Benefits of Direct Deposit

Finding Your Check Routing and Account Number

If you need to find your routing and account numbers, you likely have several options, from looking at a physical check to logging in to your banking app:

How to Find the Routing vs Account Number on a Check

You can find your routing vs. account number on a check, printed on the bottom.

You’ll see three groups of numbers (often separated by spaces and/or symbols). Typically, reading left to right, the first number (nine digits) is the routing number; the next group of numbers (usually eight to 12 digits) is the account number; the third is the actual check number.
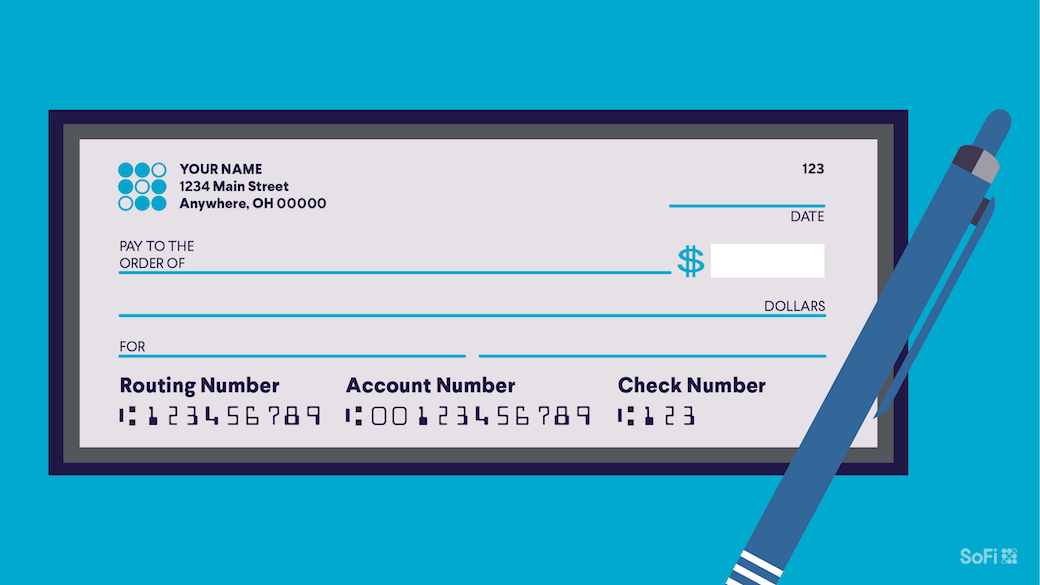
check image with numbers

Contacting Your Bank

If you need to find your routing number and account numbers and don’t have access to a check, you can call your bank (or stop into a branch) and ask a customer service representative to provide you with the numbers. Since your account number is private information, you will likely have to provide identifying details to verify your right to gain access to this number.

Note: If all you need is the routing number, you can easily find it on your bank’s website.

Accessing Your Online Account

If you log in to your bank account online or in-app, you should be able to get your banking details. Your account number may be encrypted (meaning you can only see the last four digits). If that’s the case, you can typically get the full number by downloading a recent bank statement. Or there may be a prompt you can click in order to see the full number.

Recommended: Checking Account vs Debit Card: What’s the Difference?

Protecting Your Routing and Account Numbers

Although anyone can locate your bank’s routing number, your account number is not public information. Just as you are probably mindful about who sees your Social Security number, the same goes for your bank account number. You want to try to make sure that someone doesn’t use your bank account and routing number without authorization, which can be a form of bank fraud.

Tips for Keeping Your Banking Information Secure

Here are some ways to help keep sensitive banking information safe:

•   Avoid sharing your banking details unless necessary. To protect yourself from potential bank fraud, you generally don’t want to share your account number with any person or business unless you absolutely need to. Also wise: not sharing pictures of checks you’ve written on social media, even if it is for the first payment on your dream car.

•   Store physical checks in a secure place. Since checks contain both your routing and account number, it’s a good idea to keep your checkbook tucked away in a safe place, not sitting out in the open. Also, if you void a check or are getting rid of old checks and paper statements, it can be wise to shred these documents before throwing them away.

•   Enable multi-factor authentication (MFA) for online banking. Two- or three-factor authentication requires additional information beyond a password — such as a code sent to your mobile phone or a fingerprint scan — for account access. You’ll typically find this option inside the account settings.

•   Regularly monitor your accounts. It’s a good idea to review your bank statements monthly and check your online banking once a week. This can help you to pick up on any suspicious transactions and nip any potential issues in the bud.

Recommended: How to Sign a Check Over to Someone Else

What to Do if Your Information Is Compromised

Here are smart steps to take if you suspect fraud or unauthorized access to your bank account:

•   Contact your bank immediately. Call customer service and inform the representative of any unauthorized banking transactions as soon as you notice them.

•   Change your login credentials: It’s a good idea to choose a new (unique) password for your bank account. Also consider setting up multi-factor authentication if you haven’t already.

•   Review your recent transactions: Comb through recent activity on your bank account and make a list of any transactions you don’t recognize, noting the date and details. You’ll typically need this information to file a dispute with your bank.

•   Consider placing a fraud alert on your credit report: You can contact any one of the three credit bureaus — Equifax®, Experian®, and TransUnion® — to place a fraud alert on all three of your credit reports. A fraud alert is free and notifies creditors to take extra steps to verify your identity before extending credit.

The Takeaway

A check routing number indicates the bank where your account is held, while an account number identifies your specific account at that bank. Routing and account numbers work together to identify your account and ensure that your money gets transferred from the right place or that you receive funds intended for you. Knowing the difference between these numbers, where to locate them, and how to protect them can be vital to managing your finances securely.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Do you need both a routing and account number for a wire transfer?

Typically, yes. Transactions like wire transfers require both a routing and account number. The routing number identifies your bank, while the account number specifies your individual account. Together, they ensure that funds are correctly withdrawn from the right institution and account.

What comes first on a check, the routing or account number?

Typically, when you look at the lower portion of a check (reading left to right), you’ll see the routing vs. account number first, followed by the account number, and then the actual check number.

The routing number is a nine-digit code that identifies the bank, while the account number indicates your specific account within that bank. Checks are typically numbered to help with record-keeping.

Which number do I provide for direct deposit?

For a direct deposit, you generally need to provide both your routing and account numbers. The routing number ensures the deposit is sent to the correct bank, while the account number directs the funds to your specific account. You may also be asked to provide a voided check.

What happens if you use the wrong routing or account number?

Using the wrong check routing number and/or account number can result in a failed transaction or funds being sent to the wrong account. If your bank catches the mistake, it may reject the transaction. If your bank misses it and the account number belongs to someone else, the money could get deposited into the wrong account. If that occurs, you’ll want to contact your bank immediately to try to remedy the problem.

Are routing numbers the same across all bank branches?

Not necessarily. Smaller banks often have a single routing number for all branches. But if a bank has branches located in different states, routing numbers usually won’t be the same across all branches. Your routing number will typically be based on the branch where you first opened your account.


Photo credit: iStock/SeventyFour


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.

SOBNK-Q426-148

Read more
woman walking through city hall

What Is Financial Wellness? Definition, Examples & Tips

In theory, financial wellness is something we all want. But the term can sound a little vague and potentially complex. What exactly does it mean, and how do you achieve it?

Simply put, financial wellness is the ability to manage your money in a way that supports your needs, goals, and overall quality of life. It involves meeting your current expenses while preparing for future needs. You can improve your financial wellness by developing healthy money habits, including budgeting, saving, managing debt, and planning for retirement.

Financial wellness isn’t just about earning a substantial income — it’s about how effectively you manage the resources available to you. You can take steps toward financial wellness at almost any income level or stage of life. Read on for a closer look at what financial wellness means, why it matters, and how to improve your own financial well-being.

Key Points

•   Financial wellness is the ability to manage your money to meet daily expenses, handle emergencies, and reach future goals.

•   Financial security comes from how well you manage your money rather than the size of your paycheck.

•   The core elements of financial wellness include budgeting, saving for emergencies, managing debt, and investing for long-term needs.

•   While financial literacy provides foundational money knowledge, financial wellness represents the practical application of those habits to your life.

•   Building strong financial habits can help reduce stress, boost financial resilience, and give you greater overall peace of mind.

What Is Financial Wellness?

Financial wellness describes a state in which you can manage your current bills and expenses, pay your debts, handle unexpected financial emergencies, and work toward long-term goals, such as saving for retirement or a child’s education.

The Consumer Financial Protection Bureau (CFPB) uses the term financial well-being to describe a similar concept. It defines financial well-being as a condition in which people can meet their current and ongoing financial obligations, feel secure about their financial future, and make choices that allow them to enjoy life.

Just as overall wellness involves adopting habits that support your physical and mental health, financial wellness involves everyday practices that support your financial stability. These might include following a budget, building savings, paying bills on time, and planning for major expenses.

Financial wellness isn’t a final destination. Your financial circumstances and priorities can change over time, so maintaining financial wellness means regularly assessing your finances and adjusting your habits and plans as needed.

Financial Wellness Examples

Financial wellness can look different from one person to another, depending on their income, expenses, responsibilities, and goals. Here are a few examples of what it can look like in everyday life:

•   Managing monthly expenses: You can pay your rent or mortgage, utilities, groceries, and other regular bills without consistently struggling to make ends meet.

•   Preparing for unexpected costs: You have emergency savings available to help cover an unexpected car repair, medical bill, or temporary loss of income.

•   Keeping debt manageable: You make your required debt payments on time and have a plan to pay down high-interest balances.

•   Saving for future goals: You regularly set aside money for retirement, a home purchase, education, or other priorities.

•   Making informed financial decisions: You understand your options when choosing a bank account, comparing insurance policies, or deciding how to use available funds.

•   Having flexibility and peace of mind: You can make reasonable spending choices, pursue personal goals, and handle some financial setbacks without derailing your entire financial plan.

You don’t have to check every box to make progress. Financial wellness is an ongoing process, and even small changes to your money habits can help you build greater financial security over time.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

The Four Elements of Financial Wellness

Financial wellness is often broken down into four key areas of personal finance. These elements overlap and can affect one another, but addressing each can help you build a more complete financial plan.

1. Budgeting and Financial Planning

Creating a budget that accounts for your income, expenses, and financial goals lays the foundation for financial wellness. A budget helps you understand where your money goes, prioritize spending, and plan for both immediate needs and future goals.

Financial planning takes this a step further by helping you prepare for major expenses and life events, such as buying a home, starting a family, or retiring.

2. Savings and Emergency Funds

Building and maintaining savings can help you prepare for unexpected expenses and future needs. An emergency fund, in particular, provides a financial cushion if you lose your job, face an unplanned medical expense, or need to make a major home or car repair.

Having savings available can also reduce the need to rely on credit cards or loans when unexpected costs arise.

3. Debt Management

Managing debt involves making payments on time, understanding borrowing costs, and developing a plan to reduce balances when appropriate. Paying down high-interest consumer debt can free up money for other priorities, including emergency savings and retirement contributions.

Not all debt is necessarily harmful to your financial well-being. The key is understanding your obligations and ensuring that your payments fit within your overall financial plan.

4. Investing for the Future

Preparing for the future means setting money aside for long-term goals, particularly retirement. Depending on your circumstances, it may involve contributing to an employer-sponsored retirement plan, an individual retirement account (IRA), or another appropriate account.

Starting early can give your savings more time to benefit from potential investment growth and compounding. However, the amount you can save, your time horizon, and your financial priorities will influence your approach.

7 Tips to Improve Your Financial Wellness

If your finances don’t currently reflect the definition of financial wellness, that doesn’t mean you can’t get there. The following steps can help you strengthen your financial habits and work toward greater financial security.

1. Set Clear Financial Goals

Building financial wellness starts with understanding your current financial situation and deciding what you want to accomplish. Clear goals can help you prioritize spending, saving, and debt repayment.

Consider setting specific, realistic objectives for different time frames. For example, you might want to save for a vacation in three months, build a down payment for a home over the next few years, or increase your retirement contributions.

Once you’ve identified your goals, estimate how much each will cost and when you’ll need the money. This can help you determine how much to set aside regularly and incorporate those amounts into your monthly budget.

2. Create and Stick to a Budget

A realistic budget accounts for your monthly income and expenses while making room for savings and debt repayment. It gives you a plan for directing your money toward necessities, discretionary purchases, financial goals, and other priorities. There are many different types of budgets to choose from. The best method is the one you can maintain consistently.

One popular approach is the 50/30/20 rule, which divides your take-home income into three categories:

•   50% for needs: Essential expenses, such as housing, groceries, utilities, transportation, and minimum debt payments.

•   30% for wants: Discretionary spending, such as dining out, entertainment, and hobbies.

•   20% for savings and extra debt payments: Contributions to savings accounts, retirement plans, and payments toward debt beyond the minimum due.

These percentages are guidelines, not strict requirements. If housing costs or other necessities take up more than half your income, you may need to adjust the allocations to fit your circumstances.

Recommended: 50/30/20 Budget Calculator

3. Pay Yourself First

One way to make saving more consistent is to automatically transfer a set amount into savings each time you get paid. This approach, known as paying yourself first, helps you prioritize savings before spending the money elsewhere.

It can be helpful to open a dedicated savings account and arrange for recurring transfers from your checking account shortly after payday. Choose an amount that fits your budget, even if you can initially save only a small amount.

If you’re building savings, consider an account that offers a competitive interest rate and low or no monthly fees. Online banks and other financial institutions may offer high-yield savings accounts, which can help you earn interest while keeping your money accessible. Compare rates, fees, withdrawal restrictions, and deposit insurance coverage before choosing an account.

4. Build an Emergency Fund

An emergency fund can help cover unexpected expenses without forcing you to rely on high-interest credit cards or loans. A common goal is to save three to six months’ worth of essential living expenses. If your income is irregular or you have limited job security, you may want to aim for a larger cushion.

Keep in mind that you don’t have to build the entire fund at once. You might start with a manageable initial goal, such as $500 or $1,000, and increase your savings over time.

Ideally, you want to keep emergency savings in an account where you can access the money when needed. A high-yield savings account may be a good option because it can offer competitive interest while keeping your funds relatively liquid.

Recommended: Emergency Fund Calculator

5. Protect Your Assets

Savings can help you handle unexpected costs, but insurance can provide another layer of financial protection. Depending on your circumstances, health, auto, homeowners, renters, disability, and life insurance may help limit the financial impact of accidents, illnesses, property damage, or loss of income.

It’s a good idea to review your coverage periodically to make sure it reflects your needs. Pay attention to premiums, deductibles, coverage limits, and exclusions when comparing policies.

You may receive health insurance through your employer, while other types of coverage may require you to shop around. Comparing policies from multiple providers can help you find coverage that fits your budget without leaving important gaps.

6. Pay Off High-Interest Debts

High-interest debt, particularly credit card debt, can make it harder to save and meet other financial goals. Paying more than the minimum when you can afford to can help reduce the interest you pay over time.

Two common repayment strategies are the debt avalanche and debt snowball methods:

•   Debt avalanche: Make the minimum payment on every debt, then direct extra money toward the balance with the highest interest rate. Once that debt is paid off, move to the next-highest rate. This approach can reduce total interest costs.

•   Debt snowball: Make the minimum payment on every debt, then direct extra money toward the smallest balance. Once it’s paid off, move to the next-smallest balance. This approach can provide a sense of progress as you eliminate individual debts.

No one repayment method is right for everyone. The best approach is one you can follow consistently while keeping up with your required payments and other essential expenses.

7. Start Investing

Retirement planning is another important part of financial wellness. If you’re able to set aside money for retirement, regular contributions can help you prepare for future living expenses.

If your employer offers a 401(k) or similar retirement plan, consider contributing an amount that fits your budget. If your employer matches some of your contributions, you ideally want to contribute enough to receive the full match.

An individual retirement plan (IRA) is another option to explore. The right account and contribution strategy will depend on factors such as your income, eligibility, tax situation, and retirement timeline.

Starting early gives your contributions more time to potentially grow through investment returns and compounding. Still, it’s important to balance retirement saving with immediate needs, emergency savings, and high-interest debt. You can adjust your contributions as your financial situation changes.

What’s the Difference Between Financial Wellness vs. Financial Literacy?

Financial wellness and financial literacy are related, but they aren’t the same thing.

Financial wellness describes your overall financial well-being, including your ability to meet current expenses, manage debt, handle financial setbacks, and work toward future goals. It reflects not only your financial circumstances but also your habits and the choices you make with your money.

Financial literacy refers to your knowledge and understanding of financial concepts, such as budgeting, interest rates, credit, loans, insurance, and retirement accounts.

Financial literacy can help you make informed decisions, but knowledge alone doesn’t guarantee financial wellness. For example, you might understand the importance of emergency savings but struggle to build a fund because your income barely covers your essential expenses.

Improving financial literacy can help you develop better money-management strategies. Applying what you learn, while accounting for your circumstances and available resources, can help you work toward greater financial wellness.

Benefits of Financial Wellness

Financial wellness can support several aspects of your life, from day-to-day money management to long-term planning. Potential benefits include:

•   Less financial stress: Having a plan for paying bills, managing debt, and preparing for unexpected costs may help reduce uncertainty about money.

•   Greater financial resilience: Emergency savings and appropriate insurance can help you absorb some financial setbacks without disrupting your entire budget.

•   More flexibility: When your finances are manageable, you may have more room to make choices about work, education, travel, or other personal priorities.

•   Progress toward long-term goals: Regular saving and thoughtful financial planning can help you prepare for major milestones, such as buying a home or retiring.

•   More informed decisions: Understanding your financial situation can help you evaluate trade-offs, compare options, and decide how to use your money.

•   Greater peace of mind: Knowing what you owe, what you have saved, and what you’re working toward can make it easier to approach financial decisions with confidence.

Financial wellness doesn’t mean having no debt, earning a high salary, or never worrying about money. Unexpected expenses and changing circumstances can affect anyone. The goal is to develop habits and resources that help you manage your finances and adapt when challenges come up.

The Takeaway

Financial wellness means being able to manage your money, meet your current needs, prepare for unexpected expenses, and work toward future goals. It doesn’t require a high income or a perfect financial record.

You can improve your financial wellness by setting realistic goals, following a budget, building savings, managing debt, protecting yourself with appropriate insurance, and planning for retirement. You might start with the areas that need the most attention, then build on your progress over time. Even small, consistent steps can help you create a stronger financial foundation.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

How is financial wellness measured?

Financial wellness can be measured by looking at whether you can pay your bills, manage debt, cover unexpected expenses, and make progress toward financial goals. You can also assess how secure you feel about your financial future and how much flexibility you have when making money decisions. The Consumer Financial Protection Bureau offers a financial well-being scale that can help you evaluate your financial situation and sense of security.

What are the signs of poor financial wellness?

Signs of poor financial wellness may include regularly struggling to pay bills, relying on credit cards to cover basic expenses, having little or no emergency savings, and falling behind on debt payments. You might also feel persistent stress about money or find it difficult to plan for future expenses. These challenges don’t necessarily mean you’re doing something wrong, but they may signal that your finances could benefit from additional support or a new strategy.

Why is financial wellness important in the workplace?

Financial wellness can affect employees’ stress levels, productivity, and overall well-being. Employees who are worried about money may have difficulty concentrating at work or feel less satisfied with their jobs. Employers can support financial wellness by offering benefits such as retirement plans, emergency savings options, financial education, and access to financial counseling. These resources may help employees manage their finances and feel more confident about their financial future.

Can you achieve financial wellness while in debt?

Yes, financial wellness doesn’t require being completely debt-free. You can work toward financial wellness while managing student loans, a mortgage, or other debts, provided you have a plan for making payments and balancing your other financial priorities. The key is to focus on paying bills on time, keeping debt manageable, building emergency savings when possible, and addressing high-interest balances. The best approach will depend on your income, expenses, interest rates, and financial goals.

What is a financial wellness program?

A financial wellness program is a set of resources, tools, or benefits designed to help people improve their financial knowledge and manage their money. Workplace programs may include budgeting workshops, retirement planning assistance, debt management education, financial counseling, and emergency savings benefits. Employers may offer these programs to help employees address financial challenges and plan for the future. The specific resources available vary by employer and program.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.

SOBNK-Q426-142

Read more
Three people discussing when to take social security.

What Age Should You File for Social Security? 62 vs 65 vs 67?

Social Security is a critical part of most people’s retirement plans, and knowing when to start drawing on those benefits is important. Having an idea of how much you could ultimately receive from Social Security may help you determine other parts of your retirement plan and work toward your retirement goals.

Americans can start drawing Social Security benefits at age 62, but there can be benefits to waiting until full retirement age (67), or longer.

There are many factors to consider when choosing your retirement date, but thinking ahead about your potential Social Security benefits may be beneficial. Here’s what to know.

Key Points

•   The earliest Social Security benefits can be claimed is at age 62.

•   Claiming at age 62 results in reduced benefits — an individual would get about 70% of their full benefits.

•   Full retirement age is 67, offering 100% of benefits. Delaying benefits until age 70 increases monthly payments by approximately 25%.

•   Factors influencing when to claim DSocial Security typically include health, life expectancy, marital status, and financial situation.

•   It may be wise for individuals to supplement Social Security benefits with other retirement income, such as that from a workplace plan like a 401(k) or an IRA.

How Might Social Security Impact When You Retire?

Social Security is likely an important part of your retirement plan. But it’s important to keep in mind that it’s only one part, as many people will likely need more savings and investments to fund their retirement. Knowing your potential Social Security benefits could help you figure out what your additional savings or investments may need to amount to.

With that in mind, you’ll want to give some thought to additional factors, such as your health and family situation, to help figure out when you should plan to start drawing your Social Security benefits. For many people, it may be best to wait until full retirement age, if possible.

What Is Full Retirement Age (FRA)?

Full retirement age, as outlined by the Social Security Administration, is 67, assuming you were born in 1960 or later. That’s the age at which an individual is eligible for their full Social Security benefit.

The earliest you can apply for Social Security is age 62, but in this case, your benefits will be diminished.However, if you wait longer (up to age 70), you could get increased benefits.

Here’s a look at the percentage of Social Security benefits that you could be paid monthly depending on the age at which you decide to retire:

Retirement age Percentage of full Social Security benefit paid out*
62 70%
63 75%
64 80%
65 86.7%
66 93.3%
67 100%
68 108%
69 116%
70 124%

*Data reflects percentages for those born in 1960 or later, with a full retirement age of 67.

Source: Social Security Administration

Claiming Social Security at 62 (Early Retirement)

The earliest most people can apply for Social Security is age 62. Applying at 62 will reduce the amount of your benefit.

How Much Social Security Will You Get at 62?

As discussed, for those born in 1960 or later, full retirement age is 67. Taking retirement at 62 will cause your benefit to be reduced by about 30%.

If your benefit at full retirement would be $1,000 a month, and you file for benefits at 62, you will only receive about $700 or 70% of the amount you would have received at full retirement. For each month you wait past the age of 62, that amount rises a little bit. At $700 a month starting at 62, if you lived to the average U.S. lifespan of about 80 years old, you would receive $151,200 over your lifetime.

Benefits of Claiming Early

The benefit of claiming early is that you’d start seeing money sooner – potentially years sooner than if you had waited. Depending on numerous factors (health issues, etc.), this may be advantageous for some people.

When Claiming Social Security at 62 Might Be a Good Idea

It may be a good idea to start claiming benefits early if you are unable to work or otherwise find a source of income, or if you have health issues. Again, you’ll take a hit in the form of a reduced benefit, but for some people, it may be worth it.

Claiming Social Security at 67 (Full Retirement Age)

Claiming Social Security at age 67, which is the full retirement age for people born after 1960, means you’re eligible for 100% of your benefits.

How Much Social Security Will You Get at 67?

If you wait to apply for benefits until full retirement, you will get the full amount of your benefit. In the example used above, that would be $1,000 a month. In this scenario, if you live to age 80, you would receive $156,000 over those retirement years, which is close to $5,000 more than if you filed five years earlier.

Benefits of Waiting Until Full Retirement Age

The most obvious benefit of retiring at 67 is that you get your complete Social Security benefit, without reduction. If you continue to work between 62 and 67 as well, you may also have more time to add to your savings and investments, too, to help you stretch your retirement accounts.

When Claiming Social Security at 67 Might Be a Good Idea

Claiming Social Security at 67 might be a good idea if you don’t have any immediate need to retire early. Waiting to get your entire benefit may be helpful, especially since retiring at, say, 62, would reduce that benefit by up to 30%. So, if you have no immediate concerns about your health or ability to continue earning income, you might consider waiting to claim your benefits.

Delaying Social Security Until Age 70

Every month you delay applying for benefits causes the monthly benefit amount to grow, up until age 70. If you file at age 70, your monthly Social Security retirement payment is close to 25% higher than it would have been if you filed at full retirement.

How Much Social Security Will You Get at 70?

Continuing with our hypothetical scenario, rather than receiving $1,000 a month you would receive about $1,300 a month if you waited until age 70 to apply for Social Security. If you live to age 80, that comes to $156,000 — which is the same total amount you would receive if you filed at full retirement age (67). This brings into the equation one of the factors that influences at what age you may want to file for Social Security benefits: how long you expect to live.

Benefits of Delaying Your Social Security

The biggest benefit of delaying your Social Security benefits is a larger benefit. If you stand to draw a significantly bigger benefit at 70 than you would at 62 or 67, it may be worth it to wait — so long as you’re able.

When Claiming Social Security at 70 Might Be a Good Idea

Your benefits won’t increase after age 70, so it may be a good idea to start claiming them at 70 whether you need to or not. And even if you are taking Social Security at 70, it doesn’t mean you need to stop working or generating income otherwise. It all comes down to an individual’s specific circumstances.

What Factors Should You Consider When Deciding to Take Social Security?

Besides your age, there are some other key factors and variables you should keep in mind when deciding when to start drawing Social Security. These include your health, life expectancy, whether you’re married or not, and your overall financial situation.

Health and Life Expectancy

No one knows for certain how long they will live. But if you expect to live to age 75 for one reason or another, you might be inclined to take your Social Security benefit early so that you could enjoy it for a longer time. But if you expect to live until age 90, taking Social Security retirement benefits early may cost you a lot of money. Here’s how your lifetime benefit would typically be impacted by filing at different ages if your retirement benefit at full retirement is $1,000 a month:

•   By filing at age 62, you would receive a total of $235,000 over your retirement years.

•   By filing at age 65, you would receive $260,100.

•   By filing at 67 that jumps to $276,000.

•   If you wait to file until age 70 you would receive $312,000.

If you expect to live a long life, waiting a few extra years to file could potentially make a big difference in your total benefit.

Financial Situation and Other Retirement Income

A big chunk of the money spent after retirement goes toward typical retirement expenses like housing and healthcare. The average Social Security benefit as of January 2026 was $2,071 per month. So an average married couple would receive a little over $4,100 in benefits.

Many people typically rely on other forms of retirement income, including money from workplace retirement plans, earnings from investments, pensions, dividends, and interest, in addition to their Social Security benefit. In fact, having access to other forms of income may impact when you can retire.

If you do have income besides your Social Security benefit, you might want to delay claiming your benefit. For example, if you earn income from working, and you claim your benefit before full retirement age, your benefit may be reduced, depending on factors like how much you earn. If you have other types of income, such as pensions or earnings on the money you contributed to your individual retirement account (IRA), your benefit will not be reduced. However, you may have to pay taxes on it, depending on the type of account you have.

Spousal Benefits

There are many myths around Social Security benefits, so it’s important to delve into your particular situation. Spouses may be eligible for half of the benefit their spouse would receive at full retirement age. That amount is reduced if the primary beneficiary files early.

For instance, if the primary beneficiary or spouse were to apply for Social Security benefits before they reach full retirement age, they would automatically be deemed as applying for spousal benefits as well as their own benefits if their spouse is already receiving benefits. The maximum spousal benefit a person can qualify for is typically 50% of their partner’s benefits calculated at full retirement age.

One option for spouses may want to consider is to file for one spouse’s benefit early, say at 62, and postpone filing for the other spouse’s benefit until age 70. This could provide money now and more money later. If one partner dies, the surviving partner is automatically assigned the higher benefit between their own and their late spouse.

How Social Security Fits Into Your Retirement Plan

When it comes to how Social Security benefits ultimately fit into your retirement plan, including your investments, it’s important to try and take a broad, holistic view of your situation. Many people may not be able to get by during their retirement years on their Social Security benefits alone, so they would likely need some investments and savings to augment that income.

401(k)s and IRAs

To supplement your Social Security benefits, you may contribute to a workplace retirement plan, if your employer offers one. Or you might have a traditional or Roth IRA. There are differences between these two types of retirement plans, and it may be worth speaking with a financial professional to see if you are on track to supplement your Social Security and reach your retirement goals.

The Takeaway

Deciding when to file for Social Security depends on a number of factors. The earlier an individual files, the smaller their benefit will likely be. Waiting until full retirement age or later could give them a higher monthly benefit. But it is ultimately a personal decision. Either way, having other sources of income in retirement may help individuals live out their golden years more securely and comfortably.

Prepare for your retirement with an individual retirement account (IRA). It’s easy to get started when you open a traditional or Roth IRA with SoFi. Whether you prefer a hands-on self-directed IRA through SoFi Securities or an automated robo IRA with SoFi Wealth, you can build a portfolio to help support your long-term goals while gaining access to tax-advantaged savings strategies.

Help build your nest egg with a SoFi IRA.

FAQ

Is it better to take Social Security at 62, 67, or 70?

The best time to take Social Security depends on your specific circumstances. But in a broad sense, waiting until 70 may maximize your benefits, while taking benefits at age 62 typically reduces them.

How much do you lose if you retire at 62 instead of 67?

If you retire at 62, you could see your benefits reduced by as much as 30% compared to what you would have received at age 67 (full retirement age).

What is one of the biggest mistakes people make when claiming Social Security?

One mistake people may make is to claim Social Security benefits early at age 62, not realizing that doing so locks them in to collecting reduced benefits — as much as 30% lower than what they would have received if they had waited until the full retirement age of 67 — for the rest of their life.


Photo credit: iStock/FG Trade


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOIN-Q426-049

Read more
A woman holding an umbrella.

What Is a Rainy Day Fund and How Do You Start Saving?

A rainy day fund is a pool of savings set aside to cover minor, unexpected expenses that fall outside your regular budget. Unlike a full-fledged emergency fund, which is designed to help you manage major financial disruptions, a rainy day fund covers smaller surprises — such as a flat tire, an unexpected vet bill, a broken household appliance, or an unplanned medical copay.

Having money set aside for these expenses can help you keep your budget on track, avoid high-interest debt, and handle financial surprises without dipping into other savings. Below, we take a closer look at what a rainy day fund is, how it differs from an emergency fund, and how to build and maintain one.

Key Points

•   A rainy day fund covers minor, unexpected expenses like a flat tire or vet bill without throwing off your spending plan.

•   It typically ranges from $500 to $2,500, making it smaller than a full-fledged emergency fund.

•   Having a separate rainy day fund helps you avoid credit card debt or dipping into long-term savings when unexpected costs arise.

•   You can build this fund gradually using automatic transfers, direct deposits, spare change, or windfalls.

•   A good place to store your rainy day money is in an easily accessible, liquid account such as a high-yield savings account or money market account.

What Is a Rainy Day Fund?

A rainy day fund is a small, easily accessible cash reserve that you can use to pay for minor, unexpected expenses without disrupting your regular budget or going into debt. Unlike an emergency fund, which is intended to cover major financial disruptions such as job loss or a significant medical expense, a rainy day fund is designed for life’s smaller financial hiccups.

A rainy day fund often ranges from $500 to $2,500, although the right amount depends on your financial situation and the expenses you may need to cover. It’s generally kept in a liquid account, such as a high yield savings account, so you can access the money when needed.

Examples of a Rainy Day Fund

A rainy day fund can help you manage minor financial surprises without throwing off your monthly budget. Common examples of expenses it might cover include:

•   Car repairs: Replacing a flat tire or buying a new car battery.

•   Home repairs: Fixing a leaking pipe or repairing a broken washing machine.

•   Medical expenses: Paying an unexpected copay for an urgent care visit or a dental filling.

•   Pet care: Covering an unplanned vet visit for a minor illness.

•   Unexpected travel: Paying for a last-minute trip to visit a family member.

A rainy day fund can also help cover small, unplanned expenses that don’t fit neatly into your regular budget. However, predictable costs that occur periodically, such as annual subscriptions, holiday gifts, or routine car maintenance, may be better suited to a sinking fund. This type of savings fund lets you set aside money over time for expenses you know are coming, helping you prepare for them without dipping into your rainy day savings.

Rainy Day Funds Vs. Emergency Funds

Rainy day funds and emergency funds both provide a financial cushion, but they serve different purposes.

A rainy day fund is a smaller pool of savings intended for minor, unexpected expenses or budget snags that are likely to occur occasionally. You might use it to pay for a small car repair, replace a broken appliance, or cover an unexpected medical copay.

An emergency fund is a larger reserve designed to cover significant financial setbacks, such as losing your job, facing a major medical bill, or needing an expensive home repair. A common goal is to save three to six months’ worth of essential living expenses.

Here’s how the two types of savings compare:

Rainy Day Fund Emergency Fund
Target amount Often $500 to $2,500 Typically three to six months of essential living expenses
Primary purpose Cover minor, unexpected expenses Cover major financial disruptions
Typical uses Small car repairs, appliance fixes, unexpected copays Job loss, major medical expenses, significant property damage
When to use it When a relatively small, unplanned expense arises When a major expense or loss of income threatens your financial stability

You don’t necessarily need to build both funds at once. If you have limited savings, you might start with a small rainy day fund while gradually working toward a larger emergency fund.

Recommended: Emergency Fund Calculator

Why Can’t I Use My Emergency Fund?

You can use your emergency fund to cover smaller, unexpected expenses. However, doing so repeatedly can reduce the amount available for a more serious financial setback.

For example, if you use your emergency fund to pay for every minor car repair or unexpected household expense, you may have less money available if you lose your job or face a major medical bill. Without enough savings to cover an emergency, you may need to rely on a credit card or personal loan. Depending on the interest rate and repayment terms, borrowing can make an already expensive situation even more costly.

You might also be tempted to withdraw money from retirement savings or funds earmarked for a child’s education, which could trigger taxes and penalties and reduce the money available for future needs.

Having a rainy day fund won’t eliminate every financial challenge, but it can give you another resource to draw on before turning to credit or other long-term savings.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

How Much Money Should I Put in My Rainy Day Fund?

A rainy day fund often ranges from $500 to $2,500, but your savings goal should reflect your circumstances. Someone who owns a home and a car may face different unexpected expenses than someone who rents and relies on public transportation.

To estimate how much to save, make a list of the minor unexpected expenses you might face and how much they could cost. For example, you might want enough money to cover a car battery replacement, a small plumbing repair, or an unexpected vet bill. Reviewing your bank and credit card statements from the previous year can also help you identify expenses that caught you off guard.

You may also want to account for the possibility of two expenses occurring close together. If you have a $500 car repair and a $300 appliance repair in the same month, for instance, a $500 fund may not be enough to cover both.

Ideally, you’ll want to keep predictable expenses separate. Costs that occur periodically, such as routine car maintenance, annual subscriptions, back-to-school shopping, and holiday gifts, may be better suited to a sinking fund. It’s a good idea to estimate their annual cost and set aside money each month so you can pay those bills without dipping into your rainy day savings.

How Do I Save for a Rainy Day Fund?

Building a rainy day fund is similar to saving money for any other financial goal. You can choose one strategy or combine several to make progress.

•   Cut back on nonessential spending: Review your recent expenses to see where you could free up money. Cooking at home more often, canceling a streaming service you rarely use, or reducing clothing purchases could give you extra cash to put toward savings.

•   Bring in extra income: A side hustle, such as dog walking, babysitting, or freelance work, can help you build your fund. You could also sell items you no longer need and deposit the proceeds into savings.

•   Put windfalls toward savings: A tax refund, work bonus, or cash gift can give your rainy day fund a boost. Consider setting aside some or all of the money before spending it elsewhere.

•   Save your spare change: Collecting coins in a jar is a simple way to save a little at a time. You can also use a bank’s rounding-up feature, if available, to move small amounts into savings automatically.

Setting Up Automatic Transfers

One of the easiest ways to build your rainy day fund is to schedule automatic transfers from your checking account to a dedicated savings account. You could arrange a transfer for the day after payday so that a portion of your income goes toward savings before you spend it.

You might start with an amount that comfortably fits your budget, even if it’s just $10 or $25 per paycheck. Consistent contributions can add up over time, and you can increase the amount as your financial situation allows.

Utilizing Direct Deposit

If your employer offers split direct deposit, you may be able to send a portion of each paycheck directly into your rainy day savings account while depositing the rest into checking. This approach helps you save automatically without having to initiate transfers yourself.

For example, when you set up direct deposit, you might direct $25 from each biweekly paycheck into savings. That would add up to $650 over a year, before any interest earned, assuming 26 paychecks and no withdrawals.

If split direct deposit isn’t available, you can set up an automatic transfer from checking to savings instead. The key is to choose an amount and schedule you can maintain without making it difficult to cover your regular bills.

Recommended: Should You Pay Off Debt or Save?

Where Should I Keep My Rainy Day Fund?

Ideally, you want to keep your rainy day fund in an account that’s separate from your everyday spending money but still easy to access. A high-yield savings account can be a good option because it may earn more interest than a traditional savings account while keeping your money readily available. Compare account fees, minimum balance requirements, and withdrawal options before opening one.

If your bank offers savings vaults or subaccounts, you may be able to use these features to organize your money without opening multiple accounts. For example, you could create one vault for rainy day expenses and another for your emergency fund. This can make it easier to track each savings goal separately.

A money market account (MMA) is another option. It may offer competitive interest rates along with checks and a debit card for convenient access to your money, though features, fees, and minimum balance requirements vary by bank.

Whichever option you choose, it’s important to prioritize easy access, low fees, and deposit protection. Savings accounts and MMAs at FDIC-insured banks are generally insured up to applicable limits. If you use a credit union, check whether it has coverage through the National Credit Union Administration (NCUA).

The Takeaway

A rainy day fund can help you cover minor, unexpected expenses without disrupting your budget or relying on credit. To create one, start with a savings goal that fits your circumstances, contribute regularly, and keep the money in an accessible savings account. When you use the fund, it’s important to replenish it as your budget allows so you’ll be better prepared for the next unexpected expense. Over time, even small contributions can provide a useful financial cushion.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

What is considered a rainy day fund?

A rainy day fund is a pool of savings set aside for minor, unexpected expenses, such as a small car repair, an unplanned vet bill, or a broken appliance. It typically ranges from $500 to $2,500, depending on your financial situation and potential expenses. Unlike an emergency fund, which is designed for major financial setbacks, a rainy day fund helps you handle smaller costs without disrupting your budget or taking on debt.

Can state governments also have rainy day funds?

Yes. State governments can establish rainy day funds to help manage budget shortfalls during economic downturns or periods of reduced tax revenue. These reserves can help states maintain essential services without immediately raising taxes, cutting spending, or borrowing money. Like a personal rainy day fund, a government reserve provides a financial cushion for unexpected challenges, although the amounts involved and the rules governing when the money can be used vary by state.

Should I prioritize a rainy day fund over paying off debt?

It depends on your financial situation. Building a small rainy day fund while making at least the minimum payments on your debts can help you cover unexpected expenses without borrowing more. If you have high-interest debt, such as credit card balances, directing extra money toward repayment may save you more in interest than building a larger cash reserve. Once you have a basic savings cushion, you can balance additional savings with debt repayment based on your expenses, interest rates, and financial goals.

How do I replenish my rainy day fund after using it?

After using your rainy day fund, you’ll want to review your budget to determine how much you can comfortably set aside each month. You might set up automatic transfers from checking to savings, direct part of any bonus or tax refund toward the fund, or temporarily reduce nonessential spending. You don’t necessarily have to replace the entire amount immediately. Consistent contributions can help rebuild your savings over time while allowing you to keep up with regular bills and other financial priorities.

Is a rainy day fund different from a sinking fund?

Yes. A rainy day fund generally covers minor, unexpected expenses, while a sinking fund helps you save for a known expense in the future. For example, you might use a rainy day fund to pay for an unexpected appliance repair and a sinking fund to save for holiday gifts, an annual insurance premium, or a planned vacation. With a sinking fund, you typically estimate the cost in advance and contribute regularly until you have enough to cover the expense.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOBNK-Q426-143

Read more
A woman with curly hair writes at a desk with a calculator, possibly filling out common tax forms.

16 Common Tax Forms in the United States

Before you can file your tax return, you need to make sure you have the right forms. But with hundreds of Internal Revenue Service (IRS) tax forms out there, how do you know which ones you need to file?

The key is pinpointing which ones pertain to your individual circumstances. For example, if you’re employed, working as a freelancer, receiving Social Security, or earning income from investments, you’ll find a different form for each situation.

Sifting through the various types of tax forms isn’t always easy, but this guide can help clear up any confusion.

Key Points

•   Form 1040 is the primary tax return for individuals, and it allows you to report income and determine your tax liability.

•   Residents of all states fill out the same federal forms, but you may have specific state and local forms to fill out as well.

•   Knowing which forms you need to submit well before Tax Day can make filing less overwhelming and help prevent mistakes.

•   Though there are hundreds of IRS tax forms, there are only a handful that the average person will ever need.

•   Selecting the correct tax forms based on financial circumstances ensures accurate reporting and reduces audit risk.

The Importance of Knowing Different Tax Forms

IRS income tax forms are the official documents used to report income, expenses, and other financial transactions. In order to figure out whether or not you owe the federal government taxes, or if you’ve overpaid in the past year, you’ll need to file a tax return.

A tax return consists of this documentation. While residents of all states use the same federal forms, you may also have to fill out specific state tax forms as well, unless you live in one of the states that do not collect state taxes on earned wages. You may also have to fill out specific forms if you live or work in a certain city. Check with your particular state and local tax departments or divisions to see if any additional paperwork is necessary to file at tax time.

Since there are hundreds of different tax documents, the whole process of understanding your taxes can be dizzying. That’s why knowing the exact forms you’ll need can help you feel less overwhelmed and avoid making any mistakes when filing.

Submitting a tax return that doesn’t report all your income can trigger an IRS tax audit. You can also incur penalties and interest if you’ve submitted a return with errors and don’t file an amended one. And, yes, there’s a form for that, too.

16 Different Types of Tax Forms

Typically, the more complicated your finances, the more tax forms you’ll need. For instance, if you are a freelance worker with multiple clients and also rent out your second home, you’ll have a more complex tax return than a salaried employee with no side-hustle earnings or rental income.

To help make things easier, here’s a list of common tax forms you may need as you prepare for tax season. Knowing what they are can help boost your financial literacy and your tax-filing confidence:

1. Form 1040

The Form 1040 is the first step for most taxpayers when filing their annual tax return. It’s the document you use to declare your filing status, report your income, claim deductions and tax credits if you have any, and determine the amount of tax you owe or whether you’re due a tax refund.

Depending on the type of income you need to report, it may be necessary to attach additional forms, also known as schedules. These various schedule forms are used to itemize deductions, report interest and ordinary dividend income, or profit or loss through business, among others.

2. Form 1040-SR

Nearly identical to Form 1040, this document is specifically for people aged 65 and older. It’s printed using a larger font so it’s easier to read and can be used by seniors who are filing a paper return. Form 1040-SR uses the same schedules and instructions as the main Form 1040.

3. Form 1040-X

If you find you’ve made a mistake after you’ve filed your return, you’ll want to get Form 1040-X. This form is for taxpayers who need to fix or make amendments after previously filing their 1040 form.

4. Form W-2

Also known as the Wage and Tax Statement, the W-2 form tells you how much money you earned in the previous year and the amount of tax your employer withheld from your paycheck. The statement also supplies other very important information you’ll need when you fill out your 1040. This intel includes how much your employer paid for other benefits, including health insurance, dependent care assistance, health savings account (HSA) contributions, and more.

Employers who have withheld income and Social Security should issue a W-2 to their employees and the IRS by January 31. If you haven’t received yours by then, follow up with your employer and let them know.

5. Form 1099-NEC

There are several types of Form 1099, which document payments from someone that typically isn’t your employer. The 1099-NEC, which the IRS rolled out in 2020, is what companies or individuals now use to report money paid to any non-employees who did work for them. If the business paid the freelancer, independent contractor, or gig worker more than $2,000 a year in non-employee compensation, they should send that worker a Form 1099-NEC. The employer will also send a copy to the IRS.

6. Form 1099-MISC

Form 1099-MISC is used by businesses when reporting other miscellaneous paid income, such as rents, attorney fees, royalties, commissions, prizes, or awards paid to third parties. In general, an individual will get a 1099-MISC form to report payments that are not subject to self-employment taxes.

7. Form 1099-G

Form 1099-G will be issued by a government agency if you’ve received certain government taxable income, such as unemployment benefits. The form also provides information on other government payments, such as state and local tax refunds, credits or offsets, taxable grants, and money received from the Department of Agriculture. You’ll need to report information from Form 1099-G on your federal return.

Most states mail it out and may send more than one to you. However, some states don’t. If you need to access your state form, try obtaining it online from your state’s department of revenue or contact the department directly.

8. SSA-1099

People who receive Social Security benefits during the tax year will receive an SSA-1099 form from the Social Security Administration (SSA). The SSA-1099 form tells you how much Social Security income to report to the IRS on your tax return and is mailed out each January to people who receive benefits. The IRS will also receive a copy of this form.

If Social Security was your only type of income last year, your benefits may not be taxable, and therefore, you may not need to file a tax return. However, if you have income from other sources, you may have to pay taxes on some of your benefits.

9. Form 1099-R

Individuals who have received $10 or more from their retirement plan should receive a 1099-R. Besides reporting distributions from retirement plans, the 1099-R also covers annuities, profit-sharing plans, IRAs, insurance contracts, or pensions. Additionally, any rollover transfers from one retirement account to another will also be reported on Form 1099-R. The plan issuer is responsible for sending out the form to the taxpayer, but, as with most forms, it’s on the individual to include it when filing.

10. Form 1099-INT

The 1099-INT form is used by taxpayers to report any income received from interest. This statement comes from the entity that issues the interest payments. Interest income can come from a mutual fund, brokerage, bank, or a U.S. savings bond.

Payers must issue a Form 1099-INT to any party to whom they paid at least $10 of interest during the year. The document includes a roundup and categorization of all types of interest income and associated expenses. People should receive Form 1099-INT from their particular financial institution, which also makes sure the IRS gets a copy. The information should be reported on your tax return.

11. Form 1099-DIV

Individuals who have received $10 or more in dividends or distributions from any type of investment should get a 1099-DIV form from the financial institution with whom they invest. Since dividends are an extra income stream for investors, the money has to be reported to the IRS.

Investors can receive more than one 1099-DIV if their portfolio spans multiple investment funds. Any 1099-DIV form figures should be reported when filing.

12. Form 1098 Mortgage Interest Statement

If you’re a homeowner with a mortgage and paid any interest over $600, you’ll get Form 1098 from the lender. Form 1098 reports the amount of mortgage interest you paid during the year. Your lender, though, isn’t required to send you this form if your mortgage interest was less than $600. Mortgage interest can be taken as an itemized deduction.

13. Form 1098-T

The 1098-T form is sent by eligible universities, colleges, and vocational schools to students who paid qualified educational expenses in the prior year. Qualified educational expenses include tuition, books, any required enrollment fees, and course materials for those who have attended an eligible educational institution. These expenses may entitle you to a tax credit or an adjustment to income, according to the U.S. Department of Education.

14. Form 1098-E

Form 1098-E is a student loan tax form that reports the amount of interest paid on a student loan. Loan lenders submit a copy of this form to the IRS and send one to the borrower who paid $600 or more in interest during the tax year. If you didn’t pay at least $600 in student loan interest, you won’t receive any 1098-E forms. Students with more than one loan servicer will receive a separate 1098-E form from each lender.

Use your 1098-E Form to figure out your student loan tax deduction. Borrowers can deduct up to $2,500 in interest from their taxable income if they meet certain income and other requirements.

15. Schedule 1-A,

Schedule 1-A is a new IRS form intended for people declaring deductions that were created by the One Big Beautiful Bill Act signed in July 2025. If you plan to claim deductions for tip income, overtime compensation, interest paid on car loans, or seniors over age 65, you’ll need to use 1-A. You do not need to itemize deductions to use Schedule 1-A. For details on each deduction, see the IRS site.

16. Form 4868

Need more time to file your taxes? If so, you’ll want to fill out IRS Form 4868, also called Application for Automatic Extension of Time to File U.S. Individual Income Tax Return. Form 4868 gives taxpayers an additional six months to file their federal income tax returns.

If you decide that you do need a tax extension, be sure to file Form 4868 by the normal April filing deadline. By obtaining the extension, you avoid any late-filing penalties as long as you file by the extended due date. However, it’s important to note that any taxes due must still be paid on time.

Recommended: What Happens If I Miss the Tax Filing Deadline?

5 Tips for Filling Out Your Tax Forms

Now that you know a bit more about common tax forms in the United States, here’s some advice on filling out your tax return in time for the mid-April deadline.

•   Start gathering your paperwork early. Give yourself time to make sure you’re not missing any tax documents. It’s better to have ample time to track them down if you don’t receive them from your employer, brokerage firm, or bank, for example.

•   Enter your information on your return correctly. Avoid any headaches down the road by ensuring you’re entering the right information. Even one incorrect Social Security or tax ID number, name spelling, or not signing and dating all the relevant pages can cause problems in processing your return. If you’re filing your taxes for the first time, double-checking the details is a great habit to start.

•   Have last year’s tax information handy. It might be helpful to have your federal and, if applicable, your state return on hand as a guide and good refresher of what you filed last year and what forms you used.

•   Get help from the IRS. The IRS provides online instructions on how to fill out the various tax forms. You can plug in the particular form number you need help with into the search field here.

•   Consider using a professional tax preparer or tax software. This is especially true if your taxes tend to be more complex, you’re strapped for time, or the thought of filling out forms yourself sends you into panic mode. Although it costs more than filing yourself, having someone else who knows exactly how to file a tax return on your side can help alleviate unnecessary anxiety and stress. The same holds true for tax software. By getting professional support in this way, you may also uncover deductions, which can lower your taxable income, that you didn’t know you were eligible for.

The Takeaway

Tax time can be stressful and confusing, especially if your tax situation is more complex. Being familiar with the types of tax returns and the specific IRS tax forms can help make things easier, especially if you’re doing the filing yourself. Keeping track of the statements you receive from employers, financial and educational institutions, loan lenders, and more can help ensure your taxes are done accurately by Tax Day.

Take control of your finances with SoFi Coach. You can easily view all of your accounts in one convenient dashboard: bank and investment balances, current debts, spending breakdowns, and credit score. Easily set up budgets and spot upcoming bills. And get personalized insights on everyday money questions and take action with Coach chat, the AI guide that’s powered by the playbooks of SoFi Financial Planners, so its guidance comes from expert knowledge.

Meet Sofi Coach, your smart personal guide to getting your money right.

FAQ

What tax forms are the most important?

The key tax forms most people need to know about are Form 1040 (the Individual Income Tax Return that gets filed by Tax Day), a W-2 if you’re a regular employee or contractor who has had your taxes withheld, 1099s, which reflect forms of income other than a salary, and 1098s, which are used to report tax-deductible expenses such as mortgage interest, student loan interest, and tuition payments. Starting in the 2025 tax year, Schedule 1-A allows taxpayers to take advantage of four new deductions introduced in the One Big Beautiful Bill Act.

How many tax forms do people file a year on average?

The number of tax forms people file will vary, and some may only be required to pay federal taxes. Others may pay federal, state, and local taxes and therefore file different types of tax returns to reflect that. Each tax filer has a unique set of circumstances and requirements.

How many types of tax forms are there?

There are more than 1,000 different Internal Revenue Service (IRS) tax forms, but you’ll likely only encounter a fraction of these. The most common tax forms include W-2 (for employees to report wages and taxes withheld), 1099 (for interest, dividends, and freelance earnings), and 1040 (the main individual tax return form). The number of tax forms you receive and need to file will depend on your situation.


Photo credit: iStock/eclipse_images


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SORL-Q426-019

Read more
TLS 1.2 Encrypted
Equal Housing Lender