piggy bank with band-aids

What Is an Emergency Fund? Definition, Meaning & Guide

An emergency fund is a lump sum of money set aside to cover unanticipated expenses or financial emergencies that may happen.

Besides offering peace of mind, an emergency fund may help prevent you from having to rely on high-interest debt options like credit cards. Read on to learn more about what an emergency fund is and how to build one.

Key Points

•   An emergency fund is a lump sum of money that can be used for unexpected expenses, financial emergencies, or in the event of income loss, such as losing a job.

•   Financial professionals generally advise having three to six months’ worth of living expenses in your emergency savings fund.

•   An emergency fund may help prevent individuals from going into debt, provide funds during unemployment, and provide peace of mind.

•   To begin building an emergency fund, it might help to start with a smaller goal, such as $500 or $1,000.

•   Using a high-yield savings account and automating contributions to the account may help gradually build up your emergency fund to the amount that’s best for your circumstances.

What Is an Emergency Fund?

The emergency fund definition is: Money set aside that you could use if you get an urgent, unexpected bill (like a medical expense or car repair) or endure a loss of income, such as job loss. It’s essentially a savings fund earmarked for unplanned expenses or financial emergencies.

A major home repair, like a leaking roof, is an example of an unplanned expense that typically needs to be dealt with right away. Losing a job is an example of a financial emergency that may cause a lot of stress if you don’t have an emergency fund to help pay for necessities and bills.

If someone doesn’t have an emergency fund and experiences financial difficulties, they might turn to high-interest debt. For instance, they may use credit cards or personal loans to cover expenses, which can lead to struggling to pay down the debt that’s left in its wake.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.20% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.30% APY as of 9/23/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

Why Do You Need an Emergency Fund?

An emergency fund can help protect you financially if and when an emergency happens.

Having an emergency fund with liquid assets you can access quickly, generally comes with a range of benefits. Below are some of the perks of having an emergency fund.

Preventing You From Going into Debt

There may be other ways to cover the cost of an emergency, such as using credit cards or pulling money from other savings, like retirement funds. But utilizing these options may come with high interest (credit cards) or early withdrawal penalties (certain types of retirement accounts).

Though there are many reasons for having an emergency fund, preventing debt is an important one.

Providing Peace of Mind

Another reason why it’s important to have an emergency fund is that living without a safety net may cause you to feel stressed. Thoughts about what would happen if you got hit with a large, unanticipated expense might keep you up at night.

Being prepared with an emergency fund, on the other hand, may give you a sense of confidence that you can tackle unexpected events without experiencing financial hardship.

Providing Finances During Unemployment

If you lose your job, applying for unemployment benefits, if you are entitled to them, may help you afford some of your daily expenses. However, these payments are generally not enough to cover your entire cost of living.

You could use your emergency fund to help cover the cost of everyday expenses — like utility bills, groceries, and insurance payments — while you’re unemployed.

Making Better Financial Decisions

Having extra cash set aside in an emergency fund helps keep that money out of sight and out of mind. Having money designated for emergencies may make you less likely to spend it on something else.

Also by having a separate emergency savings account, you’ll know exactly how much you have — and how much you might still need to save. This may be preferable to keeping a cash cushion in your checking account and hoping it will be enough.

In fact, in SoFi’s Banking Survey of 500 U.S. adults, 77% of respondents who have a savings account said they used it specifically for emergencies.

Recommended: Checking vs. Savings Accounts

How Much Should You Keep in an Emergency Fund?

When it comes to just how much to keep in an emergency fund. financial professionals often recommend having at least three to six months’ worth of basic living expenses set aside.

That may be a lofty goal considering that one recent study showed that about 37% of Americans would struggle to come up with $400 in an emergency scenario. And in SoFi’s survey, 45% of respondents said they have less than $500 set aside in an emergency fund. But it’s generally wise not to be caught short and to prioritize saving an emergency fund. You could start by aiming to achieve smaller goals, such as saving $500 or $1,000 and building from there.
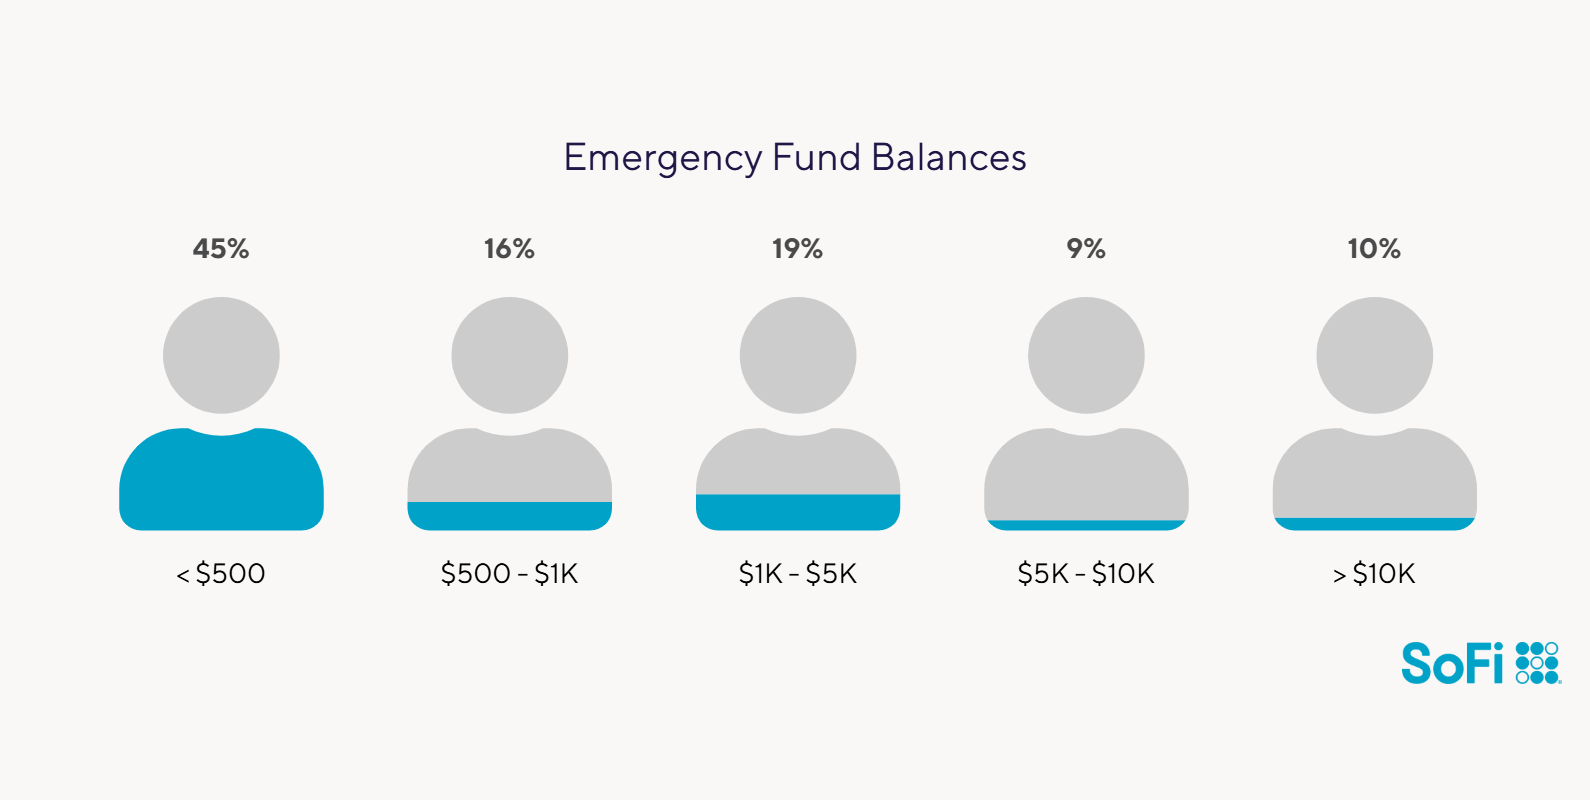
Emergency Fund Balances - SoFi How People Bank Today Survey

Source: SoFi’s 2024 Banking Survey

Emergency Fund Statistics

Curious about how much other people have in their emergency funds? Here are some recent research numbers to know:

•   About 75% of people report having emergency savings.

•   46% have enough money to cover three months’ worth of expenses.

•   Just 19% of people in SoFi’s report said they have between $1,000 and $5,000 in emergency savings.

•   24% of people overall have no emergency savings at all.

•   37% of Americans said they couldn’t cover a $400 emergency expense, according to Federal Reserve data.

•   47% of U.S. survey respondents said they couldn’t cover a $1,000 emergency bill.

How Do You Build an Emergency Fund?

Stashing money aside for a rainy day is a vital part of financial health and one way of developing good money habits. And starting an emergency fund doesn’t have to be complicated. The following are some tips to start building an emergency fund.

1. Calculate Your Monthly Expenses

Make a list of all your expenses for the month, including housing, utility bills, food, student loan payments and car payments, credit card bills, and so on. Add up all those expenses to get a total.

2. Set a Savings Goal

Next, decide how much to save. One of the easiest ways to do that is to multiply the total amount of your monthly expenses (from the step above) by the number of months’ worth of savings you’d like to have (typically, at least three to six months). If the resulting amount seems overwhelming, you can start smaller and aim to save $500 or $1,000 first, then build up your emergency fund from there.

3. Automate Your Contributions

Once you’ve set up a bank account for your emergency fund, you can schedule automatic transfers into the account — from your paycheck or checking account, for instance. This way, you can grow your emergency fund automatically.

Where Should You Keep Your Emergency Fund?

A savings account is generally a good place to keep your emergency fund because the money is safe and easy to access. Opening a high-yield savings account may be an option to consider, since you can typically earn a higher APY (annual percentage yield) on balances than you would with a traditional savings account, while still maintaining convenient access to your money.

You might open a savings account at an online bank, or you could choose to open an account at a traditional bank and use its online banking features. Forty-eight percent of people say they use online banking daily, according to SoFi’s data.

You may wonder about putting the money into a certificate of deposit (CD) account instead or investing it in the market. But there are issues with those options. A CD is a time deposit, meaning you agree to leave your savings in the account for a set amount of time until the CD matures. If you need to withdraw money from a CD in an emergency before maturity, your bank may charge you an early withdrawal penalty.

And while investing an emergency fund money in the stock market might earn a higher rate of return compared to a savings account, returns are not guaranteed. An individual is taking a risk with that money, since a downturn may reduce their investment’s value.

How Long Does It Take to Grow an Emergency Fund?

Saving enough money in an emergency fund to equal three to six months’ worth of typical living expenses can take some work and time. Here’s an example to consider: If your monthly costs are $3,000, you would want to have between $9,000 and $18,000 set aside for an emergency, such as being laid-off.

•   If your goal is $9,000 and you can set aside $200 per month, that would take you 45 months, or almost four years, to accumulate the funds.

•   If you can put aside $300 a month, you’d hit your goal in 30 months, or two and a half years.

•   If you can stash away $500 a month, you’d have $9,000 saved in one and a half years.

How Can You Grow It Faster?

Saving gradually is one way to build a cash cushion should an emergency hit. Here are some ways to potentially save even faster:

•   Putting a windfall into your emergency fund. This could be a tax refund, a bonus at work, or gift money from a relative.

•   Selling items you don’t need or use. If you have gently used clothing, electronics, jewelry, or furniture, you might sell it on Facebook Marketplace, Craigslist, or eBay.

•   Starting a side hustle. One of the benefits of a side hustle is bringing in extra cash; it may also be a way to explore new directions, build your skills, and fill free time.

Recommended: Emergency Fund Calculator

Prioritizing Your Emergency Fund When You Have Other Financial Obligations

Many people have competing financial goals: paying down student debt or a credit card balance; accumulating enough money for a down payment on a house; saving for a child’s college fund; and socking away money for retirement, for example. In many cases, you’ll see variability in financial goals by age, but there are often several needs vying for your dollars at any given time.

Potential ways to allocate funds include:

•   Starting or continuing to save toward your emergency fund. Even if you can only spare $25 per month right now, it could get you on the road to hitting your goal. Otherwise, if an emergency were to strike, you might have to resort to high-interest credit cards, or tapping any retirement savings, which may involve a penalty.

•   Continuing to pay down high-interest debt, like credit card debt. Paying more than the minimum balance due, if possible, may help you chip away at the debt a little faster.

•   Regularly paying other debt on time, such as student loans and mortgages.

•   Funding your retirement savings as much as you can. As with an emergency fund, even a small amount could help you work toward your future goals.


Test your understanding of what you just read.


The Takeaway

Building an emergency fund is an important financial goal. It’s generally ideal to aim for at least three to six months’ worth of basic living expenses, which may help you feel more secure if a major unexpected expense pops up or a job loss happens. Putting emergency funds in a savings account, such as a high-yield savings account, could help deliver both liquidity and interest.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Can I use an emergency fund for a non-emergency expense?

Technically, yes, you can use an emergency fund for a non-emergency expense. After all, it’s your money. But it defeats the purpose of saving this cash in case you need it. If you use your emergency funds to pay for a vacation or new clothes, for example, then if a true emergency arises, you may not be prepared.

How do you rebuild an emergency fund after using it?

It can be difficult to rebuild an emergency fund, just as it was to accumulate the money in the first place. But you can do it in the same way. For instance, put as much money into your emergency savings account every month as you can. Set up automatic transfers so you don’t even have to think about it. Put any “found” money like a bonus you got at work, a tax refund, or a monetary gift from a relative into the emergency fund. You might also consider starting a side gig like dog walking to earn extra money to contribute to your fund.

What are some emergency fund examples?

Examples of when you might need to use the money in your emergency fund include losing your job and needing money to help pay your expenses and tide you over, a bill for an unexpected medical procedure, or a major home repair that can’t wait, like a leaking roof. These are all instances when you may need the cash in your emergency fund to help you cover the expenses.

Should I pay off debt or build an emergency fund first?

If possible, paying off debt and building an emergency fund at the same time can be a wise strategy so that you can save and chip away at debt simultaneously. Even if you can put $25 or $50 in your emergency fund each month, it can start to add up, while paying off your debt, especially high-interest debt, may help you become more financially secure. If you can only do one of these things, however, it generally makes sense to focus on your high-interest debt. Paying down your debt could then free up funds to start putting into your emergency savings.

Is an emergency fund the same as a savings account?

No, an emergency fund and a savings account are two different things, though you may keep your emergency fund in a savings account. An emergency fund is a lump sum of money designated specifically for emergencies like a sudden medical situation or serious home or car repairs. A savings account is a type of bank account in which you keep cash for various needs. A savings account might hold money you need to access for daily spending and bills, for instance. And you might open a second savings account to hold your emergency fund.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.
Third-Party Brand Mentions: No brands, products, or companies mentioned are affiliated with SoFi, nor do they endorse or sponsor this article. Third-party trademarks referenced herein are property of their respective owners.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOBNK-Q326-121

Read more
Stacks of coins next to each other with a blue question mark on the tallest stack.

What Is a Cash Management Account (CMA)? Complete Guide

A cash management account (CMA) is a financial account that combines some of the features of checking and savings accounts and is typically offered by a brokerage firm or other financial services company. Like a savings account, a CMA typically pays interest on your cash. Like a checking account, it may offer checks, a debit card, or both. Many CMAs also make it easy to transfer money to a linked brokerage account.

CMAs can be convenient, but also have some potential drawbacks, including a lack of full-service banking features and limited access to in-person banking. Some may also pay less interest than dedicated high-yield savings accounts.

Is a CMA right for you? This guide explains how cash management accounts work, their pros and cons, and what to consider before opening one.

Key Points

•   A cash management account (CMA) combines checking and savings features into a single account, often offered by brokerage firms.

•   CMAs allow you to manage banking and investments in one place while offering features like debit cards and checks.

•   Many CMAs use sweep networks to distribute deposits across partner banks, potentially providing expanded FDIC coverage.

•   Drawbacks can include lower interest rates than high-yield savings accounts, limited customer service, and potential account fees.

•   A CMA can be a good fit for individuals who want an all-in-one platform for managing cash and investments.

What Are Cash Management Accounts?

Cash management accounts (CMAs) generally combine features of checking and savings, with the added features of linking to a brokerage account. Depending on the provider, you may be able to earn interest on your cash, spend using a debit card, write checks, and transfer money to and from other accounts.

CMAs are typically offered by brokerage firms and other nonbank financial services companies. Some providers charge low or no account fees, while others may charge for certain services or require a minimum balance to avoid fees. The company may also offer other financial products, such as brokerage, retirement, or financial planning services.

One potential benefit of a CMA is that you can manage your banking and brokerage accounts through the same company. This may make it easier to move money between accounts and keep track of your finances. However, a CMA may not offer every feature you would find at a traditional bank.

How Do Cash Management Accounts Work?

Cash management accounts generally function as a place to hold cash for day-to-day spending and short-term savings goals. Because they are often offered by nonbank financial service companies, however, they may work differently from regular bank accounts.

Some CMAs use a process called a cash sweep. Instead of keeping your cash at the company itself, the provider moves it into one or more partner banks. If those banks are FDIC-insured, the deposits may qualify for FDIC insurance, subject to applicable limits and requirements.

The company may also offer a debit card, checks, electronic transfers, or other way to access your money. If the CMA is linked to a brokerage account, you can generally transfer cash between the two accounts through the same platform.

The specific features, interest rate, fees, and insurance arrangements vary by provider. Before opening an account, it’s important to review how your cash is held and what protections apply.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.20% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.30% APY as of 9/23/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

What Are the Pros of Cash Management Accounts?

Understanding the benefits of a cash management account can help you determine whether it fits your needs and financial goals.

Convenience

One of the biggest advantages of a cash management account is the ability to manage your banking and brokerage accounts through one company. A CMA may offer checking and savings features, along with the ability to move cash to a linked brokerage account.

Keeping your accounts in one place can make it easier to manage transfers, monitor balances, and organize your money. However, the convenience may come with trade-offs, such as fewer banking features or less competitive interest rates.

Traditional Banking Features

Many CMAs offer features you may expect from a checking account. Depending on the provider, these may include:

•   Debit cards

•   Checks

•   ATM fee reimbursement

•   Mobile banking

•   Direct deposit

•   Electronic transfers

Since features vary, you’ll want to make sure the account offers the tools you need before opening an account. For example, if you regularly deposit cash or use mobile check deposit, check whether those services are available.

FDIC Insurance and Sweep Networks

The Federal Deposit Insurance Corporation (FDIC) generally insures eligible deposits at FDIC-insured banks up to $250,000 per depositor, per insured bank, for each account ownership category. If a bank fails, FDIC insurance can protect eligible deposits up to the applicable limit.

Some CMA providers use sweep networks to distribute your cash across multiple FDIC-insured partner banks. This may allow you to receive more than $250,000 in total FDIC coverage, depending on the number of participating banks and how your accounts are structured.

What Are the Cons of a Cash Management Account?

CMAs also come with some potential downsides. Here are a few to keep in mind as you decide whether one is right for you.

Lower Interest Rates

While CMAs may offer better interest rates than traditional checking accounts, their yields are not always higher than those of dedicated high-yield savings accounts or some certificates of deposit (CDs).

If your primary goal is earning the highest possible APY on your savings, it may be worth comparing CMAs with online banks and credit unions. You may find a better place to keep your short-term savings.

Fewer Features

A CMA may not offer all the conveniences of a standard checking account, such as bill pay, mobile check deposit, or cash deposits. As a result, it may not fully replace a checking account.

Before opening a CMA, consider how you use your current bank account. If you need to deposit cash regularly, write checks frequently, or use other specialized banking services, you’ll want to make sure the CMA supports those needs.

No Physical Branches

Many CMAs are offered by online brokerages or financial technology companies, which means you often do not have access to brick-and-mortar locations. If you regularly deposit cash, need services such as cashier’s checks or safe deposit boxes, or prefer in-person assistance, this may be a significant disadvantage.

Cash Management Accounts vs Checking and Savings Accounts

Cash management accounts offer some of the same services as traditional bank accounts, but there are notable differences. Here’s a look at how they compare.

Cash Management AccountChecking AccountSavings Account
Primary purposeManaging cash, spending, and short-term savingsEveryday spending and bill paymentsSaving money and earning interest
InterestOften pays interest, but rates varyMay pay little or no interestUsually pays interest
Debit card or checksOften availableOften availableMay be limited or unavailable
ATM accessMay include a debit card and ATM fee reimbursementCommonly availableMay be available, but access varies
Brokerage integrationOften availableUsually separateUsually separate
FDIC insuranceMay apply to eligible deposits held at FDIC-insured partner banksApplies to eligible deposits at FDIC-insured banksApplies to eligible deposits at FDIC-insured banks

Considerations When Comparing Cash Management Accounts

If you’re thinking about opening a CMA, it’s a good idea to compare the account’s features, fees, interest rate, and how your money is held. Here are some factors to consider.

Customer Service

When you have a question or need help resolving an issue, customer service can make a difference. It’s wise to check the provider’s available support options, including customer service hours and whether you can speak with a representative. If the account is offered entirely online, find out how you can get help with issues involving transfers, debit cards, account access, or other transactions.

Minimum Balance Requirements

Some CMAs may have minimum balance requirements to avoid fees or qualify for certain features. Before opening an account, be sure to check whether there is a minimum balance and determine whether it fits comfortably within your financial situation.

Interest Rate and APY

If you’re primarily using a CMA to hold cash, you’ll want to compare its APY with those offered by other accounts. Keep in mind that rates can change, particularly for accounts with variable rates.

Also consider whether the rate applies to your entire balance or only to certain amounts and whether you need to meet any requirements to earn the advertised rate.

Fees

It’s a good idea to review the account’s fee schedule before opening a CMA. Potential costs may include monthly maintenance fees, ATM fees, wire transfer fees, or fees associated with other financial services.

An account with a competitive APY may not be the best value if its fees significantly reduce the benefit of holding cash there.

FDIC Insurance and Cash Sweeps

If FDIC insurance is important to you, you’ll want to understand exactly how the provider handles your cash. Find out whether funds are swept into FDIC-insured partner banks, which banks participate, and how much coverage may be available.

You might also consider whether you already have deposits at any of the participating banks because those balances may affect your total FDIC coverage at a particular institution.

Investment Services

Many CMA providers also offer brokerage or investment services. If you plan to use those services, you may want to consider the provider’s investment options, account fees, and other features separately from the CMA itself.

A CMA can make it convenient to move money between accounts, but convenience shouldn’t be the only factor when choosing a brokerage or investment provider.

Is a Cash Management Account a Good Fit for You?

A CMA may be a good fit for people who want to manage cash and brokerage accounts through the same company. The all-in-one nature of these accounts can make it easier to move money and keep track of your finances.

A CMA may also be worth considering if you hold a large amount of cash and want to explore whether a sweep network can provide additional FDIC coverage. However, coverage depends on the provider’s arrangements and applicable insurance limits. It’s important to review the details rather than assume all your cash is insured.

Active investors may also prefer a CMA to a traditional checking or savings account if they want to earn interest on uninvested cash while keeping it available for future investment opportunities.

However, a CMA may not be ideal for people who frequently deposit cash or rely on in-person banking services. If your primary goal is maximizing APY, a dedicated high-yield savings account may be a better option. In addition, combining spending, saving, and brokerage funds in one account may make it harder to track sub-balances and could lead to accidentally spending money intended for other saving or investing.

Recommended: 50/30/20 Budget Calculator

The Takeaway

CMAs offer a convenient alternative to traditional checking and saving accounts. Since investment firms often offer CMAs, they may allow you to manage your banking and brokerage accounts through one company. As with any financial product, there are pros and cons to these accounts. Determining whether one is right for you will depend on your money management style, the features you need, and your financial goals

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

What is the purpose of a cash management account?

A cash management account (CMA) is designed to help you manage cash for spending, saving, and other financial needs in one place. Depending on the provider, a CMA may offer features such as interest on your cash, a debit card, check-writing, ATM access, and electronic transfers. CMAs are often linked to brokerage accounts, making it convenient to move money between your cash and brokerage accounts. They can be useful if you want to manage banking and brokerage services through the same company.

What type of account is cash management?

A cash management account (CMA) is a financial account that combines features commonly associated with checking and savings accounts. CMAs are generally offered by brokerage firms and other nonbank financial services companies rather than traditional banks. Depending on the provider, a CMA may offer interest on cash, debit card access, check-writing, ATM access, and electronic transfers. Some providers also use FDIC-insured partner banks to hold customers’ cash.

Is a cash management account the same as a money market account?

No. A cash management account (CMA) and a money market account are different types of accounts. A CMA is typically offered by a brokerage or other nonbank financial services company and may combine checking, savings, and brokerage features. A money market account is a type of deposit account offered by banks and credit unions. Both may pay interest and offer easy access to your money, but their features, rules, fees, and insurance arrangements can differ.

Are cash management accounts safe from market losses?

It depends on where your money is held. Cash held in an FDIC-insured bank deposit through a cash management account’s sweep program may be protected from losses resulting from a bank failure, subject to applicable FDIC limits and requirements. However, money held in investments through a linked brokerage account can lose value. It’s important to understand whether your cash management account balance consists of bank deposits, investments, or another type of financial product and what protections apply.

Can I write checks from a cash management account?

Many cash management accounts offer check-writing privileges as one of their standard features. Providers may also offer debit cards, electronic transfers, ATM access, or other ways to access your money. If writing checks is important to you, be sure to check the account’s features before opening it. You may also want to review any limits, fees, or requirements associated with check-writing.


Photo credit: iStock/MicroStockHub


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.

SOBNK-Q326-131

Read more
hands on table using smartphones

What Does P2P Mean in Banking? How P2P Payments Work

P2P payments, or peer-to-peer transfers, are a popular digital way to send money to and receive money from other people. With P2P, you can send a friend your half of the dinner bill, gas money, or other payments, quickly and easily from your mobile device.

To move money via P2P, all you need to do is to download a P2P app, like Venmo or PayPal, and connect your bank account, debit card, or credit card to it. Or your financial institution may offer app options you can enable. Either way, once you are set up, you are just a few clicks away from being able to send money.

Read on to learn what P2P is and how P2P payment works.

Key Points

•   P2P (or peer-to-peer) payments are a popular way to send money to and receive money from others.

•   These apps allow for transfers to say, split a dinner bill with a friend or pay a dogsitter or hairstylist.

•   These apps may transfer money instantly or take a few days to move money into a bank account.

•   Depending on the specific transaction, fees may be assessed.

•   Alternatives to P2P apps include cash, checks, money orders, and wire transfers and other transfer services offered by banks.

What Is a P2P Payment?

What P2P means is peer-to-peer, and it’s a quick and easy way to send money to someone. With a P2P payment, you can send money to a friend with just a few clicks on your mobile device. This replaces the need to get cash at an ATM or write out a personal check, options that aren’t always quick or convenient.

For traditional P2P apps like Venmo or PayPal, both parties need to have an account with the transfer service in order to make the transaction. For example, if you want to use Venmo to repay a friend for the salad they bought you at lunchtime, that person would also need to have a Venmo account to receive the payment.

Typically, a P2P account is attached to your online bank account. Some P2P platforms, however, allow customers to link their P2P accounts to a debit card or even a credit card, though it may involve additional fees.

Recommended: Guide to Direct Deposit

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.20% Annual Percentage Yield (APY) on one SoFi Savings account with a 0.90% APY Boost (added to the 3.30% APY as of 9/23/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/26. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

How Does a P2P Payment Work

Here’s a closer look at what goes on when you use a P2P payment app.

Overview of the P2P Transfer Process

Say that you want to send money P2P to your sister for your mother’s birthday present. Depending on the type of P2P service you use, you’ll follow some variation of these basic steps.

•   Creating a P2P account. You will need to download a P2P app and then sign up for an account. In order to send money to your sister, you’ll both need to have an account with the same money transfer service.

•   Linking your bank account to your P2P account. Some P2P services have the ability to hold funds, but they generally must be linked to a primary bank account (such as your checking account), credit card, or debit card in order to be fully operational. This is how the account will pull any funds needed to make a payment.

To link your checking account, you may need your checking and routing number (which appear at the bottom of a check). Some P2P transfer services may only need your bank log-in information. Others may allow you to set up extra verification measures.

•   Searching for a user to transfer funds to. To send money to your sister, you’ll need to find her on the P2P platform. You can typically search by username, email address, or a phone number.

•   Initiating a transfer. The next step in how P2P payment works is getting the money moving. Your sister can request a payment from you, or you can initiate the payment yourself. This requires choosing the option to pay, entering a dollar amount, and confirming the transfer. If you’ve enabled additional security measures on your account, you may need to enter a PIN that gets texted to you as well.

You may have the option to add a description or note to your transaction. Some P2P services may require this information so that they can charge a fee for business-related transactions. Others offer the option to act as a personal ledger should you need it in the future.

•   Waiting for the transfer to complete. Now the funds are in motion via a P2P bank transfer. When money is sent from one customer to another, it moves in the form of an electronic package safeguarded with multiple layers of data encryption. This makes it hard for hackers to access data (like your bank account number) within the transfer while it is in motion. Similarly, data encryption is designed to keep your money and account information safe. Once the data set reaches its destination, it is decoded and deposited as currency.

•   Transferring the funds into the payee’s bank account. When a P2P transfer is completed, the funds may be deposited directly into your sister’s bank account, such as a savings account. Or they may go into an account created for her by the P2P service. Funds received into P2P user accounts can then be transferred into a person’s bank accounts at little to no cost. (Recipients are likely to pay a fee if they want the funds transferred ASAP versus in a couple of days.)

Your sister will likely receive some combination of email, text, and/or in-app notifications that the funds have arrived. If she decides to leave the money in her P2P account, she can use that account balance the next time she needs to pay someone or purchase something from a business that accepts P2P transactions.

How Long Do P2P Transfers Take?

Money transferred via P2P is usually available instantly for use within the app. However, if you choose to transfer the money into your bank account, the amount of time it takes depends on whether you opt for a standard transfer or an instant transfer.

For a standard transfer, the general rule of thumb is to allow one to three business days to complete and the money to land in your bank account. That’s because standard bank transfers use the ACH (or Automated Clearing House) system.

If you choose an instant transfer of the money from the app into your bank account, some apps may not charge a fee; others may assess a charge of 0.5% to 1.75% of the overall transfer amount.

Are P2P Money Transfers Safe?

You may wonder if mobile payment apps are safe. Any time your bank account, credit, or debit card information is online, there is a chance that someone can get a hold of it, and P2Ps are no different. While all major money transfer companies encrypt your financial information, no P2P system can say it’s totally impervious to hacks and scams.

There are additional measures you can take to make sure that your account remains secure. For example, you may be able to set up two-factor authentication, which might involve typing in a unique pin number that is texted to your phone for each transaction. Or you might elect to receive notifications each time there’s a transaction posted on your account, enabling you to spot financial fraud right away if it were to happen.

You may also want to take care when you type in a recipient’s email address, phone number, or name. A typo could lead to the money going to the wrong person.

How Do Peer-to-Peer Transfer Companies Make Money?

P2P transactions are largely offered for free to consumers, which may beg the question of how the companies that offer these services stay in business. Here are two major ways that P2P money transfer apps may generate income.

Account Fees

Typically, you can make P2P payments from a linked bank account or straight from the P2P account for free. But if you want an instant transfer or you are transferring money using a credit card or from depositing checks into your P2P account, there may be a fee involved.

Business Fees

P2P platforms aren’t just for consumers — they are used by businesses as well. Compared to the free transactions offered to standard users, businesses are generally subject to a seller transaction fee for each customer purchase made with a P2P money transfer app. Venmo, for instance, charges a fee of 1.9%, plus 10 cents for each transaction.

What Are the Benefits of P2P Money Transfers?

There are three main benefits to using online money transfer services.

•   They’re fast. Depending on the service, P2P money transfers can happen very quickly. They can take anywhere from just a few seconds to a couple of business days.

•   They’re cheap. When exchanging money between friends and family, P2P money transfers are often free. There may be a small fee, however, if you want an instant bank transfer, or if you’re using a credit card instead of a bank account, making a transfer above a certain dollar amount, conducting a high volume of transfers, or using the service for a business transaction.

•   They’re easy. P2P transfers eliminate the need to make trips to the ATM or a local bank branch to get cash, which can make money management more convenient. They also eliminate the need to get out your checkbook, write a check, and then mail it to someone. For a P2P transfer, all you likely need is a mobile device, the app, and cell service or wifi.

Alternatives to P2P Money Transfers

What if a P2P money transfer isn’t available or doesn’t suit your needs? Try these options instead to move money.

Sending a Check

You can go old-school and write a paper check. You fill out the necessary details and hand or mail the check to the person you are paying. Typically, no fee is involved, although you may sometimes have to pay for a new checkbook when you run low and order more checks.

Money Orders

Money orders are in some ways similar to a check, but you don’t write them from a bank account. Instead, you purchase them (essentially pre-paying for the amount you are sending) at the post office, businesses like Western Union or Moneygram, or from certain retailers.

Typically, you will pay a small fee. For example, the United States Post Office will issue domestic money orders up to and including $1,000. Those that are for amounts up to $500 will be assessed a $2.65 fee; for ones that are $500.01 to $1,000, $3.75 will be charged. Once you have a money order, you can either give it to the recipient in person or mail it. You can also typically track a money order to see when it’s cashed.

Using Online Bill Payment Services

Many financial institutions offer ways for their customers to pay bills electronically. A key feature of mobile banking, this bill payment service can be a simple way to send funds from your checking account, regardless of where you are or what time it is. You may be able to set up recurring payments as well for bills you receive regularly.

Wire Transfers

Wire transfers are another way to send funds electronically using a network of financial institutions and transfer agencies that operate globally. Typically, you will make a wire transfer via your bank, its website, or its app.

The process for how to wire transfer is fairly simple. You’ll need to have your payee’s banking details and will likely pay a fee to wire money.

For instance, domestic wire transfer fees can be anywhere from $0 to $30 (depending on whether they are incoming or outgoing), and they can often be processed in a few hours or within a day. International wire transfers can cost more (with both the sender and recipient possibly paying fees, typically $35 to $50 for the sender) and can take longer, typically two days. Certain banks may offer free wire transfers, perhaps only for certain types of accounts (such as premium ones), so if this is an important feature for you, it can be worthwhile to do your research.

You can also use wire transfers to transfer money between bank accounts you may have.

Recommended: Wire Transfer vs. Direct Deposit

The Takeaway

Peer-to-peer (or P2P) payment apps facilitate mobile money transactions. You can use them in place of cash or writing a check when you want to give friends or family money, whether it’s to cover your portion of a dinner bill or split the cost of a vacation rental. Some businesses also accept this form of payment.

All you need to make a P2P transfer is a mobile device, an internet connection, and your P2P app, which you must link to your bank account, debit card, or credit card.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Can you cancel a P2P payment?

You cannot typically cancel a P2P payment once the recipient has accepted it. Be sure to check the recipient’s username, email, or phone number to make sure the information is correct before sending a P2P payment.

Is P2P digital money?

P2P itself isn’t a form of money — instead P2P is a digital way of moving money from one person to another. Once a P2P transfer is complete, the recipient has money they can use to pay for purchases or transfer into their bank account.

What’s an example of a P2P payment?

An example of a P2P payment would be to use a P2P app such as PayPal or Venmo to send funds to a friend you owe money. You could also use a P2P app to send a payment to a service provider, like a hair stylist for a haircut, or a retailer when you buy an item.

Do banks use P2P?

Many banks offer their own version of P2P apps. For example, you might be able to send funds from your account to a friend, a retailer, or a service provider by using a bank’s app.

Are there tax implications for using P2P payments?

If you are using P2P to send money to friends or pay for personal goods or services you received, there are no tax implications involved. However, if you use P2P payments for business, there are potential tax considerations. If a business uses P2P to accept payments from customers, those payments need to be reported as income.


SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.

^Early access to direct deposit funds is based on the timing in which we receive notice of impending payment from the Federal Reserve, which is typically up to two days before the scheduled payment date, but may vary.

Annual percentage yield (APY) is variable and subject to change at any time. Rates are current as of 9/23/26. There is no minimum balance requirement. Fees may reduce earnings. Additional rates and information can be found at https://www.sofi.com/legal/banking-rate-sheet

Eligible Direct Deposit means a recurring deposit of regular income to an account holder’s SoFi Checking or Savings account, including payroll, pension, or government benefit payments (e.g., Social Security), made by the account holder’s employer, payroll or benefits provider or government agency (“Eligible Direct Deposit”) via the Automated Clearing House (“ACH”) Network every 31 calendar days.

Although we do our best to recognize all Eligible Direct Deposits, a small number of employers, payroll providers, benefits providers, or government agencies do not designate payments as direct deposit. To ensure you're earning the APY for account holders with Eligible Direct Deposit, we encourage you to check your APY Details page the day after your Eligible Direct Deposit posts to your SoFi account. If your APY is not showing as the APY for account holders with Eligible Direct Deposit, contact us at 855-456-7634 with the details of your Eligible Direct Deposit. As long as SoFi Bank can validate those details, you will start earning the APY for account holders with Eligible Direct Deposit from the date you contact SoFi for the next 31 calendar days. You will also be eligible for the APY for account holders with Eligible Direct Deposit on future Eligible Direct Deposits, as long as SoFi Bank can validate them.

Deposits that are not from an employer, payroll, or benefits provider or government agency, including but not limited to check deposits, peer-to-peer transfers (e.g., transfers from PayPal, Venmo, Wise, etc.), merchant transactions (e.g., transactions from PayPal, Stripe, Square, etc.), and bank ACH funds transfers and wire transfers from external accounts, or are non-recurring in nature (e.g., IRS tax refunds), do not constitute Eligible Direct Deposit activity. There is no minimum Eligible Direct Deposit amount required to qualify for the stated interest rate. SoFi Bank shall, in its sole discretion, assess each account holder's Eligible Direct Deposit activity to determine the applicability of rates and may request additional documentation for verification of eligibility.

See additional details at https://www.sofi.com/legal/banking-rate-sheet.

We do not charge any account, service, or maintenance fees for SoFi Checking and Savings. We do charge transaction fees for outgoing wire transfers, Instant Transfers, and global remittance transfers. Our fee policy is subject to change at any time. See the SoFi Bank Fee Sheet for details at sofi.com/legal/banking-fees/.
*Awards or rankings from Forbes are not indicative of future success or results. This award and its ratings are independently determined and awarded by their respective publications.

Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.

Financial Tips & Strategies: The tips provided on this website are of a general nature and do not take into account your specific objectives, financial situation, and needs. You should always consider their appropriateness given your own circumstances.

Third-Party Brand Mentions: No brands, products, or companies mentioned are affiliated with SoFi, nor do they endorse or sponsor this article. Third-party trademarks referenced herein are property of their respective owners.

SOBNK-Q326-133

Read more
Someone at a desk using a laptop to research fiat currency.

What is Fiat in Crypto? Fiat Currency Definition & Valuation

We use money to pay for things all the time, yet many of us don’t stop to think about what gives it value. A paper bill or digital balance on your checking account has no real worth on its own. So why does it work? The answer lies in the fiat money system.

Fiat money is currency that has value not because it’s backed by a physical commodity like gold or silver, but because governments declare it legal tender and people trust that it will be accepted. In the U.S., fiat money is simply the dollars and cents we use every day. In the UK, it’s pounds, and in Japan, it’s yen. Below, we’ll explore how fiat currency works, how it came to be, its pros and cons, and what the future may hold as digital currencies rise in influence.

Key Points

•   Fiat currency derives its value from government decree and public trust rather than from backing by physical assets like gold.

•   It functions as legal tender because governments regulate the money supply and mandate its use for settling debts and taxes.

•   Unlike commodity money, fiat currency has no intrinsic value outside of its role as a medium of exchange.

•   The global financial system evolved from the gold standard to the current system of free-floating, government-managed fiat money.

•   Digital currencies and stablecoins are emerging as new financial tools that offer alternatives to traditional fiat systems.

Fiat Currency Definition and How It Works

Fiat money, or fiat currency, is a form of exchange or legal tender that’s backed by faith in the government, not an underlying asset like silver or gold. You can also think of fiat money as a national or regional currency. Examples of fiat currency include the dollar In the U.S., the pound in England, and the yen in Japan. Fiat money gets its value from public trust in the issuing government, the stability of that government, and the dynamics of supply and demand.

Unlike commodity money backed by tangible goods, fiat money derives its value strictly from government decree and public trust.

Fiat Money vs Commodity Money

Commodity money is a type of currency that is itself a valuable physical good, meaning it has intrinsic value apart from its use as money. A gold coin is valuable both as money and as gold. Commodity money can be used outside the monetary system. For example, silver jewelry retains value regardless of government policy.

By contrast, fiat money has no intrinsic value. A $20 bill is just a piece of money. Its worth comes from collective trust and the fact that the U.S. government requires its acceptance for payments.

A middle-ground money category is representative money, which once dominated economies. Under the gold standard, for example, paper notes were redeemable for a fixed amount of gold stored by the government. Today, however, almost all national currencies are purely fiat-based.

Crypto is
back at SoFi.

SoFi Crypto is the first national chartered bank where retail customers can buy, sell, and hold 25+ cryptocurrencies.


Why Does Fiat Money Have Value?

Even though fiat money is not backed by a physical asset, people readily accept it in exchange for goods and services. This acceptance relies on a combination of legal authority, public trust, and market forces.

Governments establish the official status of fiat money. For example, federal law declares that U.S. coins and currency are legal tender for all debts, public charges, taxes, and dues. To maintain a stable financial system, the government strictly regulates the money supply, which helps protect purchasing power and foster consumer confidence.

The lack of tangible backing to fiat currency gives central banks more flexibility to manage their economies. For instance, the Federal Reserve controls the supply of U.S. dollars, while the European Central Bank manages the euro.

What Is the Fiat System? History and Evolution

To understand how we arrived at today’s fiat-based economy, it’s helpful to trace the evolution of global monetary standards.

Asset-backed paper money originated in China, with European nations later adopting gold-backed banknotes and the gold standard to regulate currency supply. The United Kingdom officially adopted the gold standard in the 19th century, with the United States and other major economies following suit. This system effectively tied the value of paper money directly to physical gold reserves.

After World War II, the Bretton Woods Agreement established a new monetary order. Foreign currencies were pegged to the U.S. dollar, and the U.S. dollar was pegged directly to gold at $35 per ounce.1 This made the U.S. dollar the premier global reserve currency.

In August 1971, President Richard Nixon suspended the U.S. dollar’s convertibility into gold due to declining gold reserves and rising inflation. This event, known as the “Nixon Shock,” permanently ended the gold standard and established the free-floating, government-decreed fiat system used today.

Here’s a look at notable milestones in U.S. currency history:2

•   1690: First issuance of paper notes in the Massachusetts Bay colony.

•   1739: Ben Franklin introduces anti-counterfeiting measures to stop the illegal reproduction of paper notes.

•   1775: The Continental Congress issues paper money to fund the Revolutionary War; lack of government backing results in a dramatic loss of value.

•   1791: Alexander Hamilton establishes the Bank of the United States to facilitate borrowing and lending for the U.S. government.

•   1861: “Greenbacks” are issued to finance the Civil War.

•   1862: Legal tender notes are issued in denominations of $1, $2, $5, $10, $20, $50, and $100.

•   1913: Federal Reserve Act establishes the Federal Reserve as the nation’s central bank.

•   1971: Nixon takes the U.S. off the gold standard.

The Pros and Cons of a Government-Backed Money System

Fiat currencies have many attractions, but they aren’t foolproof. Comparing the pros and cons of fiat money can help in understanding its importance and role on the global stage.

Advantages:

•   Flexibility: Fiat money allows for flexibility in managing economic policy and the money supply, potentially reducing the risk of banking disruptions.

•   Efficiency: Unlike commodity money, fiat money does not rely on scarce resources like gold.

•   Support for modern economies: Fiat money enables complex financial systems, credit expansion, and international commerce.

•   Portability and convenience: Paper bills and digital balances are easier to use than heavy coins and bullion.

Disadvantages:

•   Risk of inflation: Without strict limits, governments can over-issue money, eroding value.

•   Dependence on trust: If public confidence collapses, fiat money can quickly lose worth.

•   Potential for mismanagement: Poor monetary policy or political instability can trigger crises.

•   No intrinsic value: Unlike gold, fiat money has no fallback use if confidence collapses.

Pros and Cons of Fiat Currency

thumb_up

Pros:

•   Flexible policy control

•   Independent of gold reserves

•   Expands global trade

•   Highly convenient to use

thumb_down

Cons:

•   High inflation risk

•   Depends entirely on trust

•   Vulnerable to mismanagement

•   Lacks intrinsic worth

Real-World Fiat Currency Examples

Most currencies today are fiat money. Some of the most significant fiat currencies include:

•   U.S. dollar

•   Mexican peso

•   Canadian dollar

•   Indian rupee

•   Japanese yen

•   Chinese yuan

•   South Korean won

•   British pound

•   Euro

•   Australian dollar

•   New Zealand dollar

Notable Cases of Fiat Currency Failure

There are several instances of fiat currency failures throughout history. Some of the currencies that have collapsed or suffered catastrophic hyperinflation in the modern era include the:

•   German papiermark (1920s)

•   Belorussian ruble (1990s)

•   Russian ruble (1990s)

•   Venezuelan bolívar (1990s – present)

•   Zimbabwe dollar (2000s)

The collapse of the papiermark after World War I is notable because of the sheer size of the gap between its value and the dollar. By November 1923, you would have needed 4.2 trillion German papiermarks to have the equivalent of just one U.S. dollar.

Hyperinflation and Sovereign Currency Failures

Sovereign currency failures can occur when a government faces massive debts and prints unbacked money to fund its deficits. As the money supply explodes — while economic output shrinks — public trust in the currency shatters.

This can create a vicious loop known as hyperinflation — generally defined as an episode when the monthly inflation rate is greater than 50%.3 In extreme cases, prices double within days, destroying the currency’s utility as a medium of exchange. Citizens quickly abandon the worthless paper for stable foreign currencies or tangible goods.

Stabilization generally only occurs when the government completely abandons the dead currency. To reset public trust, the state typically must introduce a new, strictly limited currency or formally adopt a stable foreign “hard” currency.

What Does Fiat Mean in Crypto?

Fiat money is the primary means by which global commerce operates. However, an emerging and distinct class of digital currencies is now gaining momentum.

What Is Fiat in Crypto vs Decentralized Digital Assets

In recent years, digital currencies like Bitcoin have sparked debates about the future of money. Unlike fiat currencies, cryptocurrencies are managed by a decentralized network rather than any government or single authority.

Transactions made with cryptocurrencies are permanently logged on a ledger known as a blockchain. This ledger is viewable to anyone, therefore functioning as a public database. Cryptocurrencies offer a number of potential benefits, including faster transaction speeds, potentially lower fees, and greater accessibility. However, they still face challenges, including price volatility, environmental concerns, and the complexities of navigating strict new global compliance laws.

Stablecoins and CBDCs: Digital Bridges for National Currencies

Stablecoins are a type of cryptocurrency designed to maintain a fixed value by being pegged to a reserve asset, most commonly traditional fiat currencies like the U.S. dollar. Centralized issuers must hold assets in reserve so that stablecoin holders can redeem them at any time. Stablecoins may be bought and sold and used as a form of payment for goods and services.

Accessibility and reduced transactional costs are fueling interest in stablecoin. However, the safety of a stablecoin depends on its backing assets, the transparency and solvency of its issuer, and the security of the wallet used to store it.

Another notable development in the digital currency space is the emergence of central bank digital currencies (CBDCs) — virtual currencies that are issued and backed by a nation’s central bank.

CBDCs sound to some people like an oxymoron because cryptocurrencies, by definition, are decentralized and don’t have an authority backing them. However, more central banks are exploring the possibilities of using them.

Comparison of Fiat and Digital Currency Models

Fiat Currency Cryptocurries (e.g., Bitcoin) Stablecoins Central Bank Digital Currencies (CBDCs)
Issuer Central banks / governments No single issuer (decentralized) Regulated private issuers Central Banks
Supply cap No fixed cap (managed via monetary policy) Fixed or program controlled No fixed cap (changes based on reserve deposits) No fixed cap (controlled by the issuing bank)
Typical Settlement speed Minutes to days Seconds to hours Seconds to minutes Near-instantaneous
Control / Governance Centralized by the state Decentralized consensus Centralized by issuer Centralized by the state
Primary collateral Government decree/trust None (utility/market demand) Fiat or cash equivalents Government credit
Transaction privacy Private in cash; visible to banks digitally Pseudonymous (visible public ledger addresses) Pseudonymous on-chain; centralized identity verification Fully traceable by the government

The Future of the Global Money System

Fiat money isn’t going away any time soon, but we may see a blend of traditional systems and digital innovation in the coming years.

Changing Role of Central Banks

As the number of digital currencies continues to grow, central banks are increasingly forced to pay attention. The uptick in the number of countries exploring CBDCs is evidence that governments are aware of the risks of digital currencies and are seeking ways to mitigate those risks by integrating them into payment systems. In the U.S., the Federal Reserve recently withdrew guidance for banks related to crypto assets. They also issued a joint statement with the Office of the Comptroller of the Currency (OCC) and the FDIC addressing the safekeeping of crypto-assets by banks on behalf of their customers, creating a clear signal that banks can serve as custodians of digital assets.4

However, the U.S. has officially blocked the creation of a retail or intermediated digital dollar. Congress passed a strict legislative ban within the 21st Century ROAD to Housing Act, prohibiting the Federal Reserve from issuing a CBDC through the end of 2030.5 This statutory ban reinforces an executive halt driven by persistent concerns over user privacy, government surveillance, and commercial banking stability.

Ongoing Debates on Stability and Longevity

Cryptocurrency’s decentralized nature puts it at risk for wide swings in valuation. Compared to the dollar or other forms of fiat money, digital currencies may see values go up or down dramatically in a short period of time. Lack of government backing means that public confidence can play an even greater role in determining which way a cryptocurrency’s price moves.

Broad-scale accessibility and long-term viability remain major hurdles. Thousands of abandoned cryptocurrencies have historically lost all or nearly all of their value. Even stablecoins can “depeg” — moving away from their intended value — due to localized illiquidity, sudden regulatory crackdowns, or underlying smart contract failures.

Banks are opening pathways with crypto checking and savings accounts that blend traditional banking with digital asset management. They allow you to hold fiat money in an FDIC-insured bank account while storing cryptocurrency in a secure digital wallet. (Keep in mind, however, that cryptocurrency assets are not FDIC insured and may lose value.) These hybrid account options may entice more people to explore digital currencies and help push them to the forefront of financial systems in the U.S. and abroad.

U.S. Stablecoin Regulations (The GENIUS Act)

The federal GENIUS (Guiding and Establishing National Innovation for U.S. Stablecoin) Act, which was signed into law in July 2025, opens the door to a regulatory framework that would allow the use of stablecoins as a form of payment. The Act requires stablecoin issuers to hold reserves in U.S. currency and enforces key rules surrounding transparency. It does not, however, convey government-backed status to stablecoins and prohibits issuers from marketing their coins as being backed or insured by the government.

The federal Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act, signed into law in July 2025, established a formal regulatory framework for using stablecoins as a legitimate form of payment.

•   Reserve mandate: The Act requires permitted issuers to back tokens 1:1 with U.S. currency or other liquid assets, such as short-term Treasuries.

•   Transparency rules: Issuers must comply with strict, monthly public disclosure and independent audit rules.

•   No federal guarantee: The law does not grant government-backed status to stablecoins. It strictly prohibits issuers from marketing their coins as being backed or insured by the federal government.

Asset Tokenization and the Integration of TradFi With DeFi

Asset tokenization is the process of converting ownership rights of a physical or financial asset into a digital token on a blockchain. The goal is to transform illiquid, hard-to-trade assets into liquid, easily tradable digital units. By doing so, asset tokenization serves as the primary bridge for integrating traditional finance (TradFi) with decentralized finance (DeFi), creating a unified financial ecosystem often called “real-world asset” (RWA) tokenization.

This integration allows institutional assets to access the 24/7 liquidity, automated compliance, and global reach of blockchain networks. This process can make investing faster and lower transaction costs, while also giving DeFi protocols stable, valuable collateral to work with.

The Takeaway

Fiat money is a form of currency, such as the U.S. dollar or the euro, that is not backed by a physical commodity like gold or silver, but is instead given value by a government’s decree. Its value is based on the trust and confidence that people have in the issuing government and its economy. Most modern economies use fiat money, allowing central banks to control economic factors like inflation by managing the money supply.

Digital currencies offer an alternative to the fiat currency system, and are attracting significant interest from governments and the public due to their potential for faster, cheaper transactions, and new financial applications. These newer currency options range from decentralized cryptocurrencies to stablecoins and CBDCs.

SoFi Crypto is back. SoFi members can now buy, sell, and hold cryptocurrencies on a platform with the safeguards of a bank. Access 25+ cryptocurrencies, such as Bitcoin, Ethereum, and Solana, with the first national chartered bank to offer crypto trading. Now you can manage your banking, investing, borrowing, and crypto all in one place, giving you more control over your money.

Learn more about crypto trading with SoFi.

FAQ

What is a fiat currency and how does it get its value?

Fiat currency is government-issued legal tender, like the U.S. dollar, that isn’t backed by physical commodities such as gold or silver. Its value comes from the public’s trust in the issuing government, the stability of that government, and the dynamics of supply and demand. Because governments declare it as legal tender, it is widely accepted for paying debts, taxes, and dues, which further cements its value and utility in the economy.

What is the difference between fiat money and cryptocurrency?

Fiat money and cryptocurrency differ primarily in their management and structure. Fiat currency is centralized, managed by governments or central banks, and derives value from official decree and public trust. Conversely, cryptocurrencies are typically decentralized, managed by networks rather than a single authority, and operate on blockchain technology. While fiat serves as the standard medium of exchange for global commerce, cryptocurrencies provide different potential benefits, such as transparency through public digital ledgers and decentralized transaction processing.

Why does fiat money have value if it is not backed by gold?

Even without gold backing, fiat money holds value through legal authority, public trust, and government regulation. Federal law designates fiat currency as legal tender, mandating its acceptance for all debts, taxes, and public charges. This legal requirement creates a consistent baseline for demand. Additionally, central banks manage the money supply to foster economic stability and protect purchasing power. This combination of government enforcement and careful economic management ensures that people and businesses accept fiat currency in exchange for goods and services.

What does fiat gateway mean when buying crypto?

A fiat gateway is a service that lets you exchange traditional paper money (like USD, EUR, or JPY) for cryptocurrency. You can think of it as an entry ramp to the crypto market. It allows you to use standard payment methods — such as credit cards, debit cards, bank transfers, or mobile wallets — to buy digital assets directly on an exchange or platform.

Without a fiat gateway, you could only trade one cryptocurrency for another. It bridges traditional banking with the blockchain world, making it possible for beginners to enter the crypto ecosystem using regular cash.

How do modern stablecoins protect their value using fiat reserves?

Stablecoins are designed to maintain a consistent value by being pegged to traditional reserve assets, most commonly fiat currencies like the U.S. dollar. Centralized issuers are responsible for holding these assets in reserve, ensuring that stablecoin holders can redeem them. The effectiveness of this protection relies on three key factors: the quality of the backing assets, the transparency and solvency of the issuer, and the security of the digital wallet used to store the assets.

Article Sources


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOCRYP-Q326-003

Read more
TLS 1.2 Encrypted
Equal Housing Lender