alarm clock on pastel background

What Is a Delinquent Payment for Student Loans?

When a student loan payment is past due, even by just one day, it becomes a delinquent payment. For instance, if your student loan payment is due by the 15th of each month and the 16th arrives and you haven’t paid the amount you owe, you’re generally considered to be delinquent on that loan.

Once you’re late making a payment, a late fee may be assessed, and the late payments may impact your credit score.

Read on to learn more about student loan delinquency and the potential consequences, as well as ways to help prevent student loans from becoming delinquent.

Key Points

•   Federal student loans are considered delinquent when they’re just one day past due.

•   Delinquent student loans can negatively affect your credit score.

•   Delinquency gets reported to credit bureaus after 90 days of nonpayment and remains on your report for up to seven years.

•   Student loans go into default after 270 days of missed payments.

•   Possible consequences of default include wage garnishment and tax refund seizure by the government to collect what’s owed.

How Student Loan Delinquency Impacts Your Credit Score

Late student loan payments can negatively impact a borrower’s credit score. In fact, as of the first quarter of 2025, new student loan delinquencies have reduced borrowers’ credit scores substantially, with amounts ranging from about 100 points to more than 150 points, according to a recent report from the New York Federal Reserve.

How Long Do Delinquent Student Loans Stay on Your Credit Report?

If you are delinquent on your student loans for 90 days or more, your loan servicer reports the delinquency to the national credit bureaus. Delinquent student loans appear on your credit report, and they typically remain there for up to seven years.

This can make it harder to get approved for new loans, such as a car loan or mortgage, and credit cards.

Difference Between Delinquency and Default for Student Loans

Your federal student loans are considered delinquent the first day you are late with a payment. They remain delinquent until you pay what you owe or get a deferment or forbearance to temporarily stop your loan payments.

After 270 days, if the loans are still delinquent, they go into student loan default. This means that your loans are now due in full, along with accrued interest and any fees, fines, and penalties.

To collect this amount, the government can garnish up to 15% of your pay, and/or take your tax refund to put towards the debt. They can do the same to your loan cosigner, if you have one. And your loan servicer can even sue you.

Recommended: Student Loan Default Rate

Common Causes of Student Loan Delinquency

There are a number of different causes of student loan delinquency. Some common ones include:

•   The pandemic: The Covid-19 payment pause on student loans meant borrowers were not required to make payments for several years. The pause ended in 2023, but then there was an “on-ramp” to help borrowers prepare to restart their payments until October 2024. At that point, late and missing payments were once again reported to the credit bureaus. According to the New York Federal Reserve, the delinquency rate on student loans soon returned to what it was before the pandemic, with approximately 7 million borrowers in delinquency or default.

•   Higher burden of student debt: The amount of student loan debt in the U.S. more than doubled from 2010 to 2025, and the average borrower’s federal student loan balance is currently $40,467. Large amounts of debt can be challenging to repay.

•   Accumulating interest: The interest on most student loans accrues daily. When a borrower makes a payment, most of that payment goes toward the interest that has accumulated since the last payment, and whatever is left goes to the principal. This makes it difficult for borrowers to chip away at what they owe, because interest continues to accrue on the loan principal.

•   Financial challenges: Financial hardships, such as job loss, a reduction in income, or having a number of other debts to repay, can lead to student loan delinquency.

•   Attendance at for-profit colleges: Students who attend for-profit colleges tend to take on greater student loan debt and have more trouble repaying what they owe. These borrowers are also less likely to get good jobs after graduation and often earn less.

•   Not completing a degree: Borrowers who don’t finish school and earn their degrees are more likely to struggle to repay their student loans. That may be because they earn lower wages.

Late Student Loan Payment

Being late with a student loan payment has consequences, even after just one day. Here are some of the potential ramifications you might face.

What Happens If You Miss a Student Loan Payment?

Missing a federal student loan payment makes you delinquent on your loan. After just one day, your loan is considered delinquent, and in 30 days, you may be charged late fees, depending on your loan servicer.

After 90 days, the delinquency is reported to the credit bureaus where it goes on your credit reports. After 270 days, your loan goes into default. The loans are then due immediately in full, along with interest and any fees, fines, and penalties. To collect what you owe, the government can garnish 15% of your wages and/or take your tax refund. Your loan servicer may also take you to court.

Federal vs Private Student Loan Late Payment Policies

In general, federal student loans offer more options for borrowers who are late with their payments. For example, a borrower could choose deferment or forbearance or switch to another payment plan that lowers their monthly payments, such as income-driven repayment plans. Federal student loans might also offer a loan rehabilitation program.

Policies for late payment on private student loans vary by lender, but overall, private lenders tend to have less flexibility and more stringent rules. For example, a private lender might charge you late fees and send your case to collections when you miss payments. Private lenders can also sue borrowers who stop paying their loans.

Options to Get Back on Track After a Late Payment

If you’re late with a federal student loan payment, contact your student loan servicer and let them know that you’re having trouble paying your loan. They may suggest options to help, such as forbearance or deferment, or you may be able to switch to a different payment plan that could make it easier to repay your loans, such as income-driven repayment.

If you have private student loans, contact your lender immediately to see what they might be able to do to help.

If you simply forgot about the loan payment, make it as soon as you remember. The sooner you get out of delinquency status, the better.

Can You Refinance a Delinquent Student Loan?

It may be possible to refinance a delinquent student loan, depending on the lender. If the delinquency has not yet affected your credit, you may be able to qualify for refinancing. If not, you could ask a creditworthy family member or friend to be your cosigner on the loan, which might help you qualify.

Once a loan goes into default, however, refinancing is much more challenging.

How Refinancing Can Help Prevent Future Delinquency

If you are struggling with high student loan payments, one option that may help you avoid delinquency down the road is refinancing student loans. When you refinance your loans, you exchange them for a new loan from a private lender, ideally with a lower interest rate, which reduces the amount of interest you pay over the life of the loan. Or, you might be able to lower your monthly payments by extending the term of the loan. However, you’ll pay more in interest over the life of the loan with an extended term.

A student loan refinance calculator can help you determine how much you might save to see if refinancing makes sense for you.

Just be aware that if you refinance your federal loans with a private lender, you will forfeit all of your federal benefits, including programs such as income-driven repayment plans and deferment.

Recommended: Student Loan Refinancing Guide

How to Avoid Becoming Delinquent on Student Loans

To keep from becoming delinquent on your student loans and avoid any possible consequences, here are a few steps you can take.

Setting Up Autopay and Budgeting Tips

Enrolling in autopay means your payments will be automatic so that they are always made on time, without you having to think about them. Plus, federal student loan borrowers get a 0.25% discount on their interest rate when enrolling in autopay. Many private student loan lenders offer a discount for autopay as well.

In addition, create a budget that prioritizes loan payments and stick to it. Pull together all your bills for the month along with your income. Look to see where you can cut back (such as ordering takeout less or eliminating one or two of your streaming subscriptions), and put the money you save toward your loans.

Exploring Deferment, Forbearance, and Income-Driven Repayment Plans

If you’re struggling to make your federal student loan payments, an income-driven repayment plan may help. On these plans, payments are based on a borrower’s discretionary income and family size, and often result in lower payments.

If you’re undergoing financial hardship, perhaps because of a job loss or medical emergency, you can apply for federal student loan deferment, which can postpone payments or reduce them. Borrowers with qualifying loans are not required to pay the interest that accrues.

Another option is forbearance, which also temporarily allows you to reduce or postpone loan payments. However, with forbearance, borrowers are always responsible for paying the interest that accrues.

The Takeaway

Student loan delinquency begins the first day after you miss a payment. Federal student loans generally go into default after 270 days of missed payments, potentially leading to wage garnishment and tax refund seizure. If you’re struggling to make payments, consider contacting your loan servicer or lender to discuss your options. Setting up autopay and exploring alternative repayment plans can also help you avoid delinquency.

Looking to lower your monthly student loan payment? Refinancing may be one way to do it — by extending your loan term, getting a lower interest rate than what you currently have, or both. (Please note that refinancing federal loans makes them ineligible for federal forgiveness and protections. Also, lengthening your loan term may mean paying more in interest over the life of the loan.) SoFi student loan refinancing offers flexible terms that fit your budget.

With SoFi, refinancing is fast, easy, and all online. We offer competitive fixed and variable rates.

FAQ

What is considered a delinquent student loan payment?

A federal student loan is considered delinquent after just one day of missing a payment. After 90 days, the delinquency is reported to the credit bureaus and it goes on your credit report.

How long before a student loan is in default?

After 270 days of student loan delinquency, your loan goes into default. At that point, the consequences can be serious. The loan payments are due immediately in full, along with interest and any fees, fines, and penalties. The government can garnish 15% of your wages or take your tax refund to collect what you owe, and your loan servicer could take you to court.

Can delinquent student loans be removed from your credit report?

Delinquent student loans may eventually be removed from your credit report. Typically, a delinquent student loan remains on your credit report for up to seven years.

How can you fix a delinquent student loan?

If your student loan is delinquent, call your loan servicer or lender right away to see what options you might have. For instance, if you’re struggling to afford your monthly payments, you may be able to switch to an income-driven repayment plan, which is based on your discretionary income and family size and typically lowers your payments. Other possible options include deferment or forbearance to temporarily reduce or postpone your loan payments.

Does a single late student loan payment affect your credit score?

Missing just one federal student loan payment generally shouldn’t affect your credit score, as long as you make the missed payment as soon as possible. After 90 days, delinquent federal student loans are reported to the credit bureaus and go on your credit report. With private student loans, it depends on the policy of the lender, though you generally have up to 30 days before a missed payment ends up on your credit report.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

Disclaimer: Many factors affect your credit scores and the interest rates you may receive. SoFi is not a Credit Repair Organization as defined under federal or state law, including the Credit Repair Organizations Act. SoFi does not provide “credit repair” services or advice or assistance regarding “rebuilding” or “improving” your credit record, credit history, or credit rating. For details, see the FTC’s website .

SOSLR-Q426-019

Read more
A woman sitting with her laptop and holding a notebook and pencil as she works on student loan repayment.

Should I Consolidate My Student Loans?

As of Q1 2026, 42.6 million Americans collectively have over $1.863 trillion in student loan debt. If you are one of the millions with some form of student debt, you may have asked yourself, “Should I consolidate my student loans?”

Consolidation is a process that allows you to combine your student loans into one loan with one monthly payment. Simplifying the student loan repayment process might seem like a good idea, but there are a few things to consider before you consolidate your loans. In some cases, consolidating loans may disqualify you from certain federal student loan repayment programs and forgiveness. But other times, consolidation can allow you to lower your interest rates or shorten the amount of time it takes you to pay off your loan.

Read on to learn how student loan consolidation works, the pros and cons of the process, and when to consolidate student loans.

Key Points

•   Consolidating student loans can simplify repayment by combining multiple loans into one.

•   Reduced monthly payments and a new loan term are potential benefits of consolidation.

•   Federal loans can be consolidated through the Direct Consolidation Loan program. Private student loan consolidation is more commonly known as student loan refinancing.

•   Refinancing may offer lower interest rates, but refinancing federal loans results in losing federal benefits.

•   Carefully consider the pros and cons before consolidating or refinancing student loans.

What Is Student Loan Consolidation?

Student loan consolidation combines some or all of your student loans into one loan and makes repayment more manageable. There are both federal and private options when it comes to consolidating your student loans.

Private Student Loan Consolidation

Private student loan consolidation is more commonly known as student loan refinancing. This is when a private lender pays off all or some of your student loan debt and creates a new loan, which you will then make payments on. Ideally, when you refinance student loans, the new loan will have a lower interest rate and a better term than your previous student loans.

With a private lender, you can combine both federal and private loans. But if you refinance your federal loans, you will lose access to federal student loan forgiveness programs, such as income-driven repayment plans. If you plan on using one of these programs now or at some point in the future, it’s best to hold off on refinancing federal loans. Instead, you could refinance just your private loans.

Federal Student Loan Consolidation

If you are hoping to consolidate your federal loans only and want to keep access to federal forgiveness programs and other federal benefits, you can consolidate with a Direct Consolidation Loan through the U.S. Department of Education.

Consolidating through the federal student loan system doesn’t usually save you money. It simply combines multiple loans into one. Your new interest rate is a weighted average of all your loans’ interest rates, rounded up to the nearest eighth of a percentage point. Should you consolidate student loans, any unpaid interest on the loans you’re consolidating will be capitalized — that is, added to the principal of the new loan.

Consolidation may be particularly useful for borrowers who are pursuing federal student loan forgiveness or who are enrolled in one of the more flexible federal student loan repayment plans, such as an income-driven repayment plan.

You can also choose to consolidate your federal loans and refinance your private loans. If you go this route, you may be able to get the possible benefits of refinancing (lower interest rates, a better term) without losing the perks of having federal loans.

Before you consolidate or refinance your loans, you should consider the pros and cons of the process. Getting clarity on whether consolidation is right for you will help you make the right decision for your financial needs.

Benefits of Consolidating Student Loans

As you’re considering when to consolidate student loans, either with a Direct Consolidation Loan or refinancing through a private lender, there are several advantages to keep in mind.

Simplified Repayment

Whether you choose a Direct Consolidation Loan or choose to refinance through a private lender, your loan repayment may be simplified. Managing multiple student loan payments might increase your chances of missing a payment. If you miss even one payment, you may risk damaging your credit score. Late payments may also stay on your credit profile for up to seven years.

Consolidating loans into one may help eliminate some of the stress of juggling multiple loan payments and may make repayment more manageable.

Fixed Interest Rate

When you refinance your loans through a private lender, your interest rate and terms will be based on your credit score, your payment history, the type of loan you’re seeking, and other financial factors. While requirements may vary by lender, applicants who meet or exceed the lender’s criteria may qualify for better interest rates and terms and save money over the life of the loan.

Borrowers can also switch from a variable to a fixed interest rate when refinancing through a private lender if they’d like a payment that stays the same every month (variable rates can fluctuate with market conditions).

With federal Direct Loan Consolidation, as mentioned earlier, a borrower’s interest rate is a weighted average of current loan rates rounded up to the nearest one-eighth of a percentage point, which means this doesn’t typically result in savings for the borrower. The borrower does, however, keep their access to federal loan forgiveness programs.

Recommended: Student Loan Consolidation Rates

Flexible Loan Terms

Student loan consolidation may allow you to change the duration of your loan. If you currently have a 10-year repayment plan, for example, you may choose to shorten or lengthen the term of your loan when you consolidate or refinance. Typically, lengthening the term of your loan will reduce your monthly student loan payment but add up to more total interest in the long run.

Recommended: Refinancing Student Loans After Consolidating

Drawbacks of Student Loan Consolidation

Even though there are benefits of student loan consolidation, there are also drawbacks. Here are a few considerations to be aware of before consolidating student loans.

You Can’t Lower Interest Rates on Federal Student Loans When Consolidating

If you choose the Direct Consolidation Loan, generally you won’t see any savings. Because your new interest rate is a weighted average of your current loans, rounded up to the nearest one-eighth of a percentage point, you will probably pay around the same amount you would have paid if you didn’t consolidate. In addition, any unpaid interest on the loan you’re consolidating will be capitalized.

If you extend your term, you may see your monthly payment decrease, but your total interest payments will increase.

However, if borrowers choose to refinance with a private lender, they may qualify for a lower interest rate, thus saving money over the term of the loan. They could also opt for lower monthly payments by extending their loan term. But they may pay more interest over the life of the loan if they refinance with an extended term.

Possible Disqualification From Federal Repayment Programs

Refinancing federal student loans with a private lender means you lose access to federal repayment programs, including the Public Service Loan Forgiveness Program (PSLF) and income-driven repayment plans.

Borrowers will also be disqualified from federal benefits such as student loan forbearance and deferment options, which allow qualifying borrowers to pause payments in the event of financial hardship.

Some private lenders may offer their own hardship programs, but policies are determined by individual lenders.

Student Loan Refinancing vs Consolidation

Consolidating or refinancing student loans are terms that are used interchangeably, but they actually apply to two different types of loans. A federal student loan consolidation is when you combine federal loans through a Direct Consolidation Loan. This is done by the U.S. Department of Education.

A student loan refinance allows you to combine private and/or federal loans into one new loan and is done by a private lender. While this does effectively “consolidate” your loans, it’s different in some important ways from federal student loan consolidation.

Below are some differences and similarities between student loan consolidation vs. refinancing.

Student Loan Refinancing vs. Consolidation

Refinance

Consolidation

It combines multiple loans into one It combines multiple loans into one
You can refinance federal and private loans You can only consolidate federal loans
Private refinance lenders may charge a fee There are typically no fees
A credit check is required No credit check is needed
Your interest rate could be lowered The interest rate is a weighted average of prior loan rates, rounded up to nearest one-eighth of a percent
Terms can be lengthened or shortened Terms can be lengthened or shortened
Once refinanced, federal loans will no longer qualify for federal forgiveness or repayment programs Loans remain eligible for federal forgiveness and repayment programs
You can save money if the interest rate is lowered Typically, this is not a money-saving option

The Takeaway

Understanding the benefits and drawbacks of student loan consolidation, as well as the difference between federal student loan consolidation and private refinancing, can help you make an informed decision about repaying student loans.

If you decide to consolidate your loans through student loan refinancing, you might want to consider evaluating a few options from different lenders, because requirements, interest rates, and loan terms can vary from lender to lender.

Looking to lower your monthly student loan payment? Refinancing may be one way to do it — by extending your loan term, getting a lower interest rate than what you currently have, or both. (Please note that refinancing federal loans makes them ineligible for federal forgiveness and protections. Also, lengthening your loan term may mean paying more in interest over the life of the loan.) SoFi student loan refinancing offers flexible terms that fit your budget.

With SoFi, refinancing is fast, easy, and all online. We offer competitive fixed and variable rates.

FAQ

Can your student loans still be forgiven if you consolidate them?

If you consolidate your federal student loans with a Direct Loan Consolidation, you are still eligible for federal loan forgiveness programs. However, if you choose to consolidate your federal loans through a private lender, which is known as refinancing, you will no longer be eligible for forgiveness programs and other federal student loan benefits.

When is consolidating student loans worth it?

Consolidating student loans is worth it if you’re looking to combine multiple student loan payments into one. You can use a Direct Consolidation Loan for your federal loans and keep your access to federal benefits such as income-based repayment programs or forgiveness.

Another option is to refinance your student loans through a private lender, which may give you a lower interest rate and lower monthly payment, but if you refinance federal loans, you lose access to federal benefits such as forgiveness and income-driven repayment plans.

What are some advantages of consolidating student loans?

The biggest advantage of consolidating your student loans is that you combine them into one loan so you only have one payment every month, which makes it easier to track your loans.

If you choose to refinance your loans with a private lender, you may also receive a lower interest rate, which can help you save money. But if you refinance federal loans with a private lender, you lose access to federal programs such as forgiveness and forbearance.

What types of student loans are eligible for consolidation?

The types of federal student loans eligible for consolidation through federal Direct Loan Consolidation include Direct Subsidized and Unsubsidized Loans, Direct PLUS Loans, Federal Stafford Loans from the Federal Family Education Loan (FFEL) program, FFEL PLUS Loans, and Federal Perkins Loans.

The types of student loans eligible for refinancing are federal student loans and private student loans. But refinancing federal student loans makes them ineligible for federal benefits such as income-driven repayment and federal forgiveness programs.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Disclaimer: Many factors affect your credit scores and the interest rates you may receive. SoFi is not a Credit Repair Organization as defined under federal or state law, including the Credit Repair Organizations Act. SoFi does not provide “credit repair” services or advice or assistance regarding “rebuilding” or “improving” your credit record, credit history, or credit rating. For details, see the FTC’s website .

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOSLR-Q426-013

Read more
mother and daughter in kitchen

Parent PLUS Loans vs Private Parent Student Loans for College

Paying for college is one of the biggest expenses a parent plans for, and it can seem overwhelming. At times, you might find yourself saving up for your kid’s future education while also trying to save for your own retirement, fund a house down payment, and pay down your own debt.

With the average cost of college tuition and fees for the 2025-26 school year at $11,950 for public in-state students, $31,880 for public out-of-state students, and $45,000 for private school students, it’s no wonder parents are taking out loans to help pay for their children’s undergraduate education.

Parents can rely on both Parent PLUS Loans and private student loans to help pay for college. Keep reading to learn the differences between the two and how to determine which type of loan may be best for you.

Key Points

•   Parent PLUS Loans are federal loans offered by the U.S. Department of Education, featuring fixed interest rates.

•   Private parent student loans are provided by private lenders, such as banks or credit unions, and may offer variable or fixed interest rates with terms based on the borrower’s creditworthiness.

•   Parent PLUS Loans have a borrowing limit of $20,000 per year and include an origination fee.

•   Private lenders may allow you to borrow up to the full cost of attendance.

•   To apply for a Parent PLUS Loan, the student must complete the Free Application for Federal Student Aid (FAFSA®), and the parent must complete a separate application. Private loans require a direct application to the lender, and eligibility criteria can differ widely.

What Are the Different Loans for College?

There are four types of federal loans offered by the U.S. Department of Education:

•   Direct Subsidized Loans are loans offered directly to the student, where the interest on the loan is paid by the U.S. Department of Education while the student is in school and during a six-month grace period after graduation. Thus, they are subsidized.

•   Direct Unsubsidized Loans are also offered directly to the student, but the interest is not paid by the federal government, and it accrues while the student is in school.

•   Direct PLUS Loans are loans for professional or graduate students or for parents of undergraduate students. Grad and professional PLUS loans are no longer available for new borrowers as of July 1, 2026.

•   Direct Consolidation Loans allow you to consolidate all federal loans into one loan with an interest rate that’s a weighted average of all your federal loans’ interest rates, rounded up to the nearest eighth of a percentage point.

The main difference between student loans offered to undergraduates and Direct PLUS Loans offered to parents is that certain Direct Loans (Direct Subsidized Loans) for undergraduates are awarded based on financial need, whereas PLUS Loans are not awarded based on financial need but do require a credit check for applicants.

In addition to federal loans, there are also private student loans available both for students and parents. Private student loans are loans from banks or private lenders, which set their own interest rates and terms.

💡 Quick Tip: Parents and sponsors with strong credit and income may find much lower rates on no required private parent student loans than Federal Parent PLUS Loans. Federal PLUS Loans also come with an origination fee.

A Parent’s Guide to
Paying for College

A free 5-part email series created with college counselors, financial aid specialists, and psychologists to help parents navigate tuition, financial aid, and the money conversations that matter most.


What Can These Loans Be Used For?

When a student’s financial aid package and other sources of funding aren’t enough to cover the cost of college and other educational expenses, Parent PLUS Loans and private student loans can help fill in the gaps. They can be used to cover expenses such as tuition, room and board, books, and other supplies.

While they can both be used to cover the same expenses, they each have different benefits and terms, so it’s worth considering your options as you determine how to pay for your child’s college education.

Parent PLUS Loans vs Private Student Loans Compared

Beyond the major difference that Parent PLUS Loans are federal student loans and private student loans are borrowed from individual lenders, there are other similarities and differences to consider.

Similarities

Here’s an overview of the major similarities between these two types of loans.

Primary Borrower

Both Parent PLUS Loans and private student loans can be borrowed by parents of undergraduate students to help them pay for their education. On both a Parent PLUS Loan and a private student loan borrowed by a parent, the parent will be considered the primary borrower on the loan.

Interest Accrual

While the application processes for these loans will be different, both loan types will accrue interest. The interest rates for Parent PLUS Loans are set annually by Congress. Interest rates on private student loans are set by the lender based on factors including the applicant’s credit score, income, and financial history, among other factors.

Loan Disbursement

Regardless of loan type, most student loans are disbursed directly to the school, where they pay for the cost of tuition and room and board. Any leftover money from Parent PLUS Loans is given to the parent, not the student.

Differences

Here’s an overview of the major differences between Parent PLUS Loans and private student loans.

Application Process

One of the major differences between these loans is the application process. Because Parent PLUS Loans are a type of federal student loan, students must first fill out the FAFSA. Then, parents are able to apply for a Parent PLUS Loan through the Federal Student Aid website.

Private student loans are administered by private lenders. To apply for a private student loan, parents will need to review the application requirements at their chosen lender.

Recommended: FAFSA Guide

Interest Rate

While both PLUS Loans and private student loans will require a credit check during the application process, it will not impact the interest rate available for PLUS Loans. Applicants with a strong credit history could potentially qualify for a more competitive interest rate with a private student loan than with a Parent PLUS Loan, which, as mentioned, has an interest rate that is set annually by Congress.

Repayment Plans

Borrowers who take out or consolidate a Parent PLUS loan after July 1, 2026, are only eligible for the Tiered Standard Plan. The repayment plan for a private student loan will be set by the lender.

SoFi offers low-rate, no fee required
parent student
loans to help you pay for your child’s
education.


Pros and Cons of Parent PLUS Loans

Parent PLUS Loans can help parents finance their child’s college education when other aid options fall short. However, it’s important to weigh the advantages and disadvantages before committing to this type of federal loan.

Pros of a Parent PLUS Loan

From high borrowing limits to flexible repayment options, these federal loans provide key advantages for parents who qualify. Pros of Parent PLUS Loans include:

•   High borrowing limit: Parents can borrow up to $20,000 each year for each student.

•   Fixed interest rate: These loans come with a fixed interest rate set by the federal government, providing predictable monthly payments.

•   Deferment options while the student is in school: Parents can defer loan payments while their child is enrolled at least half-time, easing financial pressure.

•   Federal loan protections: Parent PLUS Loans are eligible for certain federal protections, such as deferment and forbearance.

Cons of a Parent PLUS Loan

While Parent PLUS Loans can help families bridge the financial gap in paying for college, they also come with several drawbacks that are important to consider. Cons of Parent PLUS Loans include:

•   A credit check is required: Unlike most federal student loans, Parent PLUS Loans require a credit check, which may limit eligibility for some borrowers.

•   Interest rates and fees are higher: These loans typically have higher interest rates and origination fees compared to other federal student loans.

•   Parents are solely responsible: The parent, not the student, is legally responsible for repaying the loan, which could impact the parent’s long-term financial goals.

•   Limited repayment options: Parent PLUS Loans don’t qualify for income-driven repayment plans.

•   Interest isn’t subsidized: Interest accrues from the time the loan is disbursed, even if payments are deferred while the student is in school.

Pros and Cons of Private Student Loans

Private student loans can be a helpful resource when federal aid and other funding sources fall short. However, it’s important to weigh both the benefits and drawbacks before deciding whether a private loan is the right choice for your college financing needs.

Pros of Private Student Loans

Here are some potential benefits of private student loans to consider:

•   Higher borrowing limits: Private lenders may allow you to borrow up to the full cost of attendance, helping to bridge large funding gaps.

•   Competitive interest rates: Borrowers with strong credit — or a creditworthy cosigner — may qualify for lower interest rates than those offered by federal loans.

•   Flexible loan terms: Private lenders often provide a range of repayment terms, allowing you to choose a plan that fits your financial goals.

•   Fast approval process: Many private student loans offer quick application and approval timelines, which can be helpful for meeting urgent tuition deadlines.

•   Choice of fixed or variable rates: Borrowers can typically choose between fixed rates for stability or variable rates for potential savings if interest rates drop.

Cons of Private Student Loans

While private student loans can help fill funding gaps, they also come with potential drawbacks that are important to understand before borrowing. These include:

•   Credit and cosigner requirements: Approval often depends on the borrower’s or cosigner’s credit history, which can be a barrier for some students.

•   Variable interest rates: Some loans come with variable interest rates that can increase over time, making payments less predictable.

•   Limited repayment flexibility: Repayment terms are set by the lender and may not offer much flexibility if financial circumstances change.

•   Interest accrual during school: Unlike subsidized federal loans, interest on private student loans often begins accruing as soon as the funds are disbursed.

The chart below illustrates some more general comparisons between Parent PLUS Loans and private parent student loans:

Parent PLUS Loan Private Parent Student Loan
Who is the primary borrower? The borrower must be the biological, adoptive, or stepparent of a dependent undergraduate student. Some lenders allow any adult sponsor of that child (parent, grandparent, friend, etc.) to borrow for a student.
What are the credit criteria for the borrower? Parents may not have adverse credit history. Parents with adverse credit history can apply with a cosigner or submit documentation that outlines extenuating circumstances for adverse credit history. Generally, a strong credit history and score are key factors. Exact requirements will vary by lender.
Is school certification required? Yes Yes
Is the FAFSA required? Yes No
Interest rate For loans disbursed on or after July 1, 2026, and before July 1, 2027, the interest rate is fixed at 9.07%. Rates vary by lender and are based on an individual borrower’s history and other factors. Rates can be fixed or variable.
Are there any loan fees? PLUS Loans have a fee of 4.228% for loans disbursed on or after October 1, 2020. Fees vary by lender.
Annual loan limits $20,000 per student. Cost of attendance (COA) minus other student aid.
Where are funds disbursed? Funds are disbursed directly to the school. Funds are typically disbursed directly to the school.
Are there any grace periods? Payments are required immediately upon disbursement. However, you can request a deferment. Options vary by lender.
Can the loans be consolidated? Yes, loans can be consolidated through a Direct Consolidation Loan. Yes, private loans can be consolidated and refinanced through a private lender. New rates and terms will vary by lender and be based partially on a borrower’s credit history.

The Takeaway

Choosing between Parent PLUS Loans and private parent student loans depends on your financial situation and priorities. Parent PLUS Loans, as federal loans, offer fixed interest rates and options for deferment and forbearance. However, they come with origination fees and may have higher interest rates compared to some private loans.

On the other hand, private parent student loans, offered by private lenders, may provide lower interest rates for borrowers with strong credit profiles and often have no origination fees. Nevertheless, they lack the protections associated with federal loans.

If you’ve exhausted all federal student aid options, no-fee private student loans from SoFi can help you pay for school. The online application process is easy, and you can see rates and terms in just minutes. Repayment plans are flexible, so you can find an option that works for your financial plan and budget.

Cover up to 100% of school-certified costs including tuition, books, supplies, room and board, and transportation with a private student loan from SoFi.

FAQ

Can Parent PLUS Loans be forgiven?

Following recent rule changes, Parent PLUS Loans can no longer be forgiven through Public Service Loan Forgiveness (PSLF). However, all or a portion of a Parent PLUS loan may be discharged under certain circumstances such as bankruptcy or the school closing before your child could complete their program.

Can a student pay off a Parent PLUS Loan?

Yes, a student can help pay off a Parent PLUS Loan, even though the parent is legally responsible for repayment. Families can arrange informal agreements where the student makes payments directly to the loan servicer or reimburses the parent, but the loan remains in the parent’s name and credit history.

Is a Parent PLUS Loan considered a federal student loan?

Yes, a Parent PLUS Loan is considered a federal student loan. It is offered through the U.S. Department of Education to help parents pay for their child’s college education. Unlike federal student loans for students, Parent PLUS Loans require a credit check and are solely the responsibility of the parent borrower.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Non affiliation: SoFi isn’t affiliated with any of the companies highlighted in this article.

Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.

SOISL-Q426-049

Read more
A student wearing red headphones with a laptop in her lap sits on the floor between the bookshelves of a school library.

Is Tuition Insurance Worth It?

Paying for college is a significant financial investment, and many families want to ensure they’re protected in case something unexpected disrupts a student’s education. That’s where tuition insurance comes in.

Tuition insurance is a type of coverage that can help reimburse tuition costs if a student has to withdraw from school due to serious illness, injury, or other covered circumstances. But is it really necessary? This article explores what tuition insurance is, what it covers, how much it costs, and whether it’s worth considering for your family’s situation.

Key Points

•   Tuition insurance reimburses tuition costs if a student withdraws from school due to serious illness, injury, or mental health issues but not for academic or disciplinary reasons.

•   Coverage typically excludes preexisting conditions, risky activities, and pandemics, unless specific conditions are met and detailed in the policy’s fine print.

•   Plans usually cost around 1% of tuition, with some covering room and board. Policies are available through providers such as GradGuard or A.W.G. Dewar.

•   Filing a claim requires official documentation, including proof of withdrawal and a medical professional’s statement.

•   Before buying, check with your child’s school for existing refund policies and insurer partnerships, as some schools offer limited tuition refunds during early withdrawal periods.

What Is Tuition Insurance?

Just as you have health insurance to cover costs associated with unexpected health issues, you can get tuition insurance to cover college tuition costs in the event of unexpected health issues that prevent your child from attending.

Also called tuition refund insurance, it can recoup some or all of what you’ve paid in tuition if your child experiences a serious injury or illness that prevents college attendance.

What Does Tuition Insurance Cover?

Generally, tuition insurance covers,:

•   Serious sickness

•   Injury

•   Mental health conditions, including anxiety and depression

•   Death of the student or person paying tuition

You’ll need to read the fine print to find out what qualifying medical events are, as some policies will list specific illnesses, such as mononucleosis.

Imagine a pandemic sweeping the land (wild thought, huh?). Tuition insurance will not cover tuition if a college or university has to close or if your child simply isn’t comfortable attending class in person. However, if they contract the disease and are unable to attend classes as a result, they may be eligible for a partial refund of tuition for that semester.

To file a claim, the student typically has to withdraw from school, and a medical professional must document that withdrawal was necessary. The process can vary by policy, though.

What Does Tuition Insurance Not Cover?

It’s important to know what tuition insurance does not cover, as well. If the student leaves college for academic reasons or is on disciplinary probation, they will not be reimbursed for tuition.

Some preexisting conditions may not be covered, so if your child has a medical condition, make sure it is covered before buying the policy.

Tuition insurance may also not cover participating in professional sports or extreme sports (such as bungee jumping), participating in a riot, drug abuse, suicide, or self-inflicted injury.,

Who Should Consider Tuition Insurance?

Some students or parents paying for tuition might be better candidates for college tuition insurance than others.

For students with preexisting conditions that can be covered by a policy, it may be a good idea to purchase coverage, especially if it’s a condition that is known to keep the student bedridden or otherwise unable to function for weeks or months at a time. The reimbursed tuition money could be put toward medical bills or a future semester in college.

If you have more than one child in college, a tuition insurance policy could help you recoup costs for a student experiencing an issue that you could then put toward other college expenses.

And if the school your child is attending is very expensive, an insurance policy may reduce some stress in the event that something happens.

Recommended: What Is the Cost of Attendance in College?

Cost of Tuition Insurance

Part of determining whether college tuition insurance is worthwhile is understanding the policy cost vs. possible reimbursement, as well as tuition costs.

While a select few schools offer free tuition, most have significant price tags. The average costs of tuition for the 2025-2026 academic year are as follows:

•   In-state tuition for a four-year public university: $11,950

•   Out-of-state tuition for four-year public university: $31,880

•   Private nonprofit four-year institution: $45,000

These numbers add up over four (or more) years, so it’s understandable that paying for an insurance policy might make sense. But how much is tuition insurance?

Plans vary in pricing and features, but generally, you can expect to pay about 1% of the cost of tuition. Some cover other expenses, such as room and board, while others do not.

Buying a Tuition Insurance Policy

Currently, there are two primary providers of tuition insurance: GradGuard and A.W.G. Dewar. Some schools may work with a private insurance company, so start by asking the registrar’s office if the college has a partner for tuition insurance.

Of course, the most affordable and comprehensive coverage can be obtained by going directly through the school, if your school offers it. Make sure to ask your school about tuition insurance prior to seeking an outside provider.

To enroll in a policy, you’ll be asked about your student’s school and costs for a semester of tuition. You’ll then be given a quote, and if you want the coverage, you can purchase it from there by adding a few more personal details and inputting your payment information. You’ll pay your monthly premium, just as you do with auto or health insurance.

Reading the Fine Print

Before purchasing the policy, it’s best to read the fine print. The last thing you want is to purchase a policy and file a claim, expecting to be fully reimbursed, only to find out that the condition you’re filing for isn’t covered.

For example, GradGuard’s fine print discusses a preexisting medical condition exclusion waiver. It states that preexisting medical conditions are covered when the insured student does not have symptoms of the condition on the policy purchase date and was medically able to attend school, or if the student was covered by a similar policy by the same company within four months of the effective date of the current policy.

Other fine print items to note are whether a doctor or licensed mental health professional needs to diagnose the student with the medical condition to qualify for reimbursement, the effective date of the policy, and how to prove your loss. Not all policies will fully reimburse your tuition or other costs, so find out how much you may be eligible to be refunded before purchasing a policy.

How to File a Claim

Each insurance company has its own process for filing a claim. Be sure to read through the process, as one incorrect step could cause your claim to be denied.

You’ll need documentation for the expenses you want to claim from the college or university. You may need the registrar’s office to verify on paper that your student has withdrawn for the semester, as well as documents showing what you have paid in tuition and expenses.

You may also need a written order from your student’s doctor or mental health professional stating that your child is unable to attend school due to medical reasons. For mental health issues, withdrawal typically needs to be advised by a licensed medical professional.

Alternatives to Tuition Insurance

While tuition insurance can come in handy if medical conditions or injury force a student to withdraw, the college might offer full or partial reimbursement without insurance.

Policies vary from one school to another, so inquire with the college or university before assuming you can get expenses refunded.

Some schools will refund tuition, but they typically only give out full refunds before the first day of class, or partial refunds within a month of the first semester. Others may not reimburse tuition but might refund some or all of room and board expenses if students withdraw.

Prior to making a decision on whether or not tuition insurance is right for you, speak with your child’s college directly to review your options.

Is Tuition Insurance Right for You?

The bottom line: If you don’t like taking risks with your money and are concerned that your child might have a situation that results in withdrawal from school for one or more semesters, tuition insurance could be a worthwhile investment. It’s a low expense compared to tuition, so it could be well worth it should you end up filing a claim.

If your child has a preexisting condition that would be covered, insurance could mitigate your risk of losing money should that medical condition cause a need to leave school. On the other hand, not much is covered in terms of preexisting conditions or activities your child might be involved in, such as professional sports. In these cases, the policy would be moot if the condition isn’t covered when you file a claim.

If a student withdraws and not all costs are covered or if no policy is in place, a private student loan could be a solution to fill the financial gap. Private student loans can typically be used for tuition, books, room and board, transportation, and other college-related expenses.

The Takeaway

Tuition insurance can serve as a valuable safety net for families concerned about the financial risks associated with unexpected student withdrawals due to serious health issues. While it may not be necessary for everyone, it may offer some reassurance for those with higher tuition costs, limited school refund policies, or for students with preexisting medical conditions.

If you’re wondering how to pay for college, you can rely on cash savings, scholarships, grants, federal student loans, and private student loans.

If you’ve exhausted all federal student aid options, no-fee private student loans from SoFi can help you pay for school. The online application process is easy, and you can see rates and terms in just minutes. Repayment plans are flexible, so you can find an option that works for your financial plan and budget.

Cover up to 100% of school-certified costs including tuition, books, supplies, room and board, and transportation with a private student loan from SoFi.

FAQ

What is tuition insurance and how does it work?

Tuition insurance, also known as tuition refund insurance, is a policy that can reimburse some or all of your college tuition if a student must withdraw due to serious illness, injury, or mental health conditions. It acts as a financial safeguard against unexpected health issues that prevent attendance.

What does tuition insurance typically cover?

Generally, tuition insurance covers withdrawals due to serious sickness, injury, mental health conditions such as anxiety and depression, and the death of the student or tuition payer. However, coverage specifics can vary, so it’s essential to review the policy details.

What situations are not covered by tuition insurance?

Tuition insurance usually does not cover withdrawals for academic reasons, disciplinary actions, or preexisting conditions unless specified. It also excludes situations such as participating in extreme sports, drug abuse, suicide, and self-inflicted injuries.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Non affiliation: SoFi isn’t affiliated with any of the companies highlighted in this article.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOISL-Q426-039

Read more
Books with sticky note markers

What’s the Average Student Loan Interest Rate?

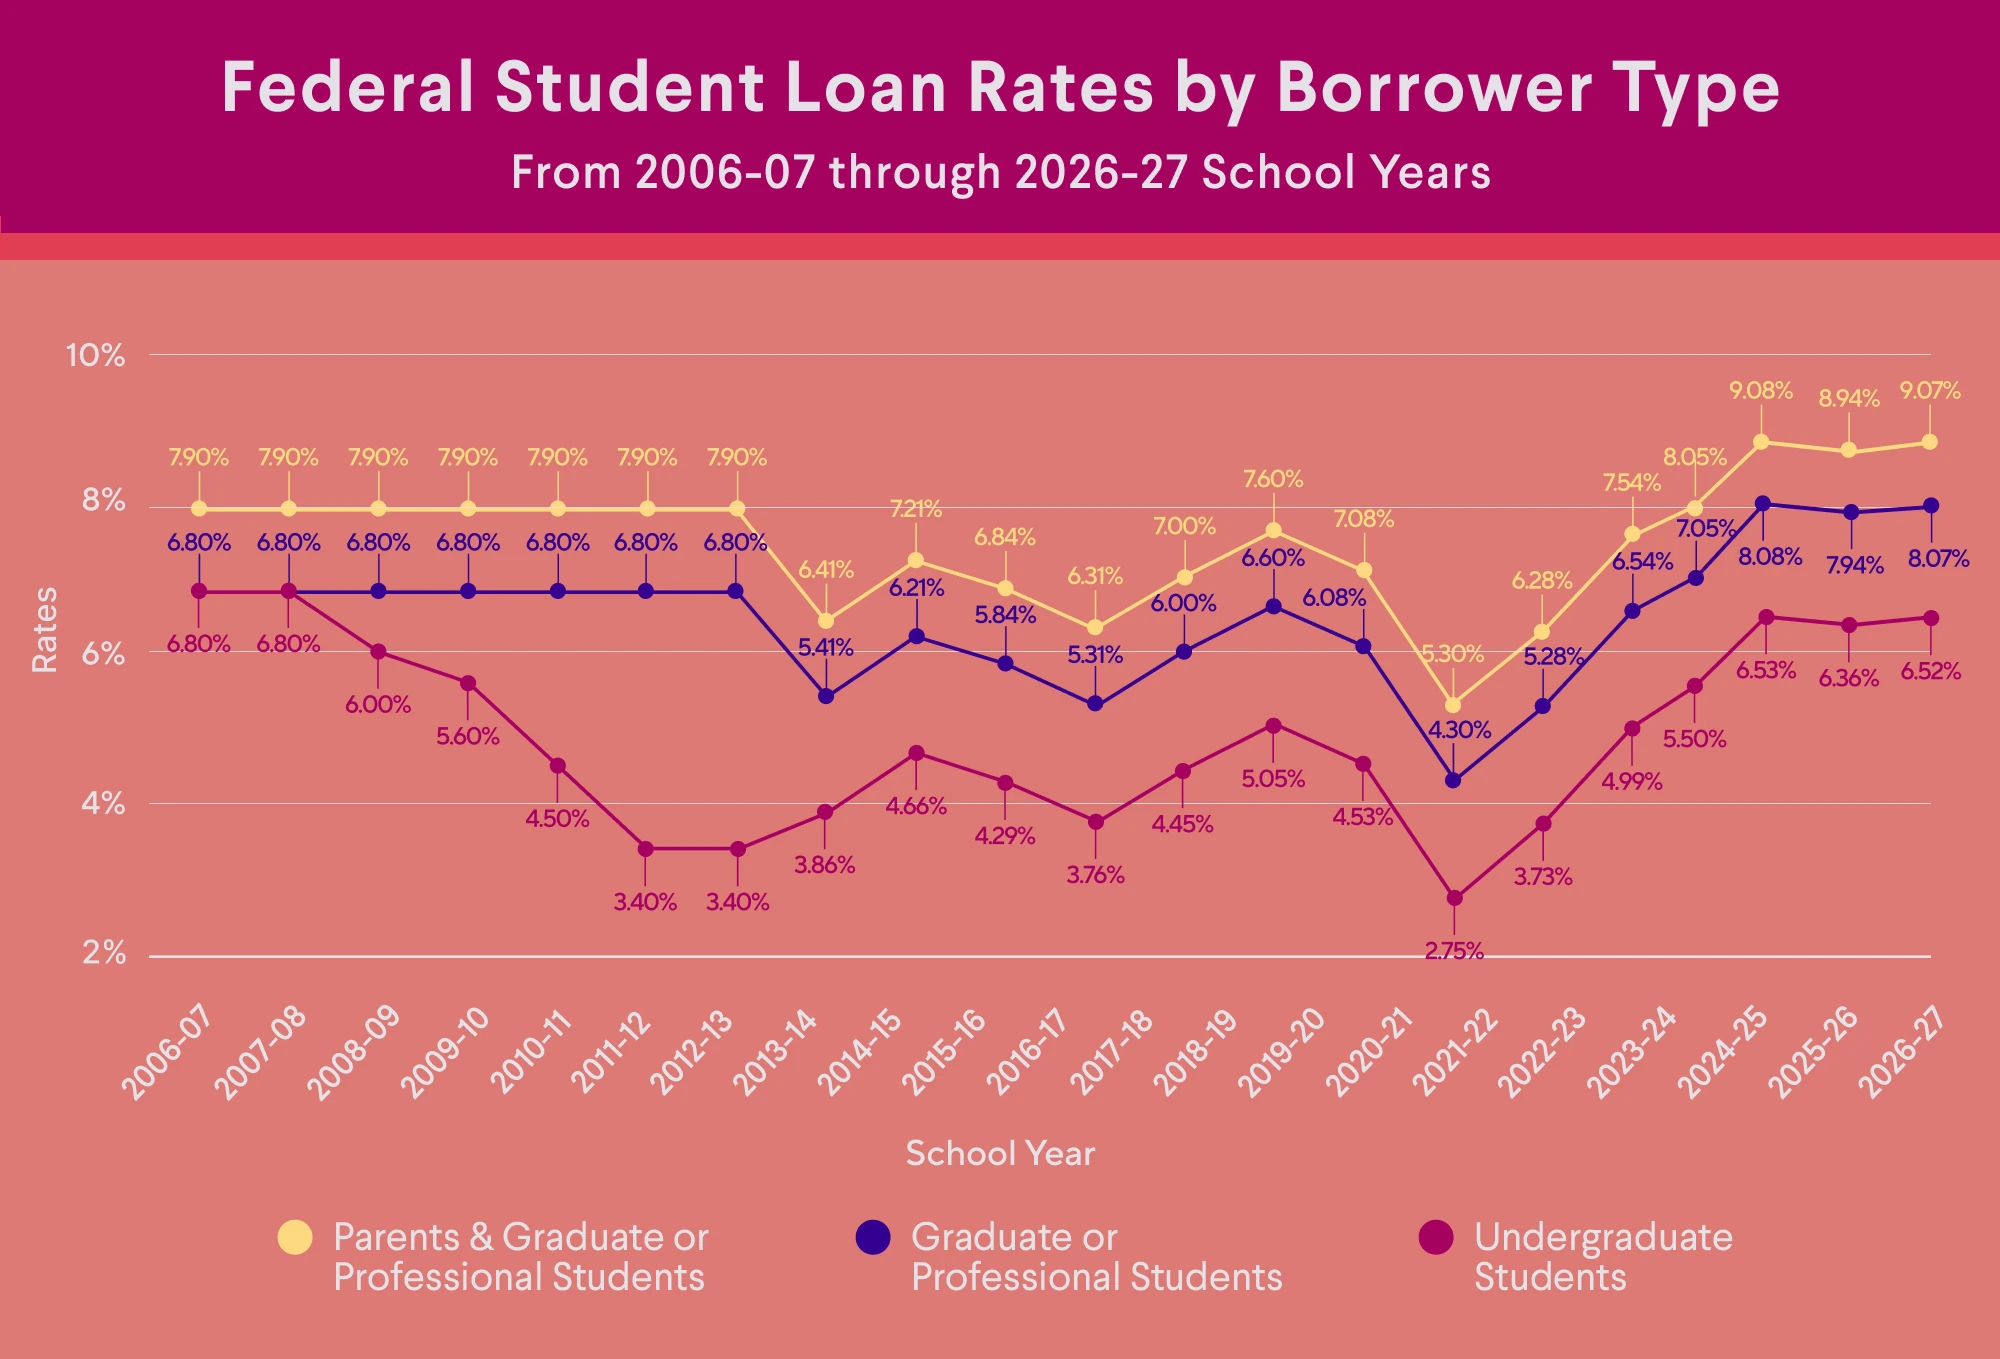
Federal and private student loans, like any loans, have an interest rate that impacts the total cost of the loan. So what is the average student loan interest rate? For the 2026-27 school year, federal student loan rates range from 6.52% to 9.07%, depending on the loan type, while private student loan rates vary by lender. In this guide, we’ll look at the interest rates of new federal student loans, as well as the range of rates for private student loans.

Key Points

•   Federal student loan interest rates for 2026-27 are 6.52% for undergraduates, 8.07% for graduate students, and 9.07% for PLUS loans.

•   Private student loan interest rates vary widely by lender and are based largely on the borrower’s credit profile.

•   Federal interest rates are fixed rates that are set annually using formulas tied to the 10-year Treasury note and a statutory add-on percentage.

•   Lenders set their own rates for private student loans. The interest rate on these loans may be fixed or variable.

•   Interest rates for federal loans have increased from the previous year, while private loans have a wide range of rates influenced by market conditions.

What Is the Average Student Loan Interest Rate?

The interest rate on a student loan varies based on the type of student loan. Federal student loans issued after July 1, 2006, have a fixed interest rate. The rates on newly disbursed federal student loans are determined annually by formulas specified in the Higher Education Act of 1965 (HEA).

These are the federal student loan interest rates for the 2026-27 school year:

•   6.52% for Direct Subsidized or Unsubsidized loans for undergraduates

•   8.07% for Direct Unsubsidized loans for graduate and professional students

•   9.07% for Direct PLUS loans for parents

All three of those rates have risen from the 2025-26 school year, and the undergraduate rate has more than doubled since the 2020-21 school year.

As of July 1, 2026, new graduate and professional borrowers can no longer take out Grad PLUS loans. Students who borrowed for their current program before that date may be able to keep borrowing Grad PLUS loans for a limited time.

Federal Student Loan Rates by Borrower Type

Source: Studentaid.gov

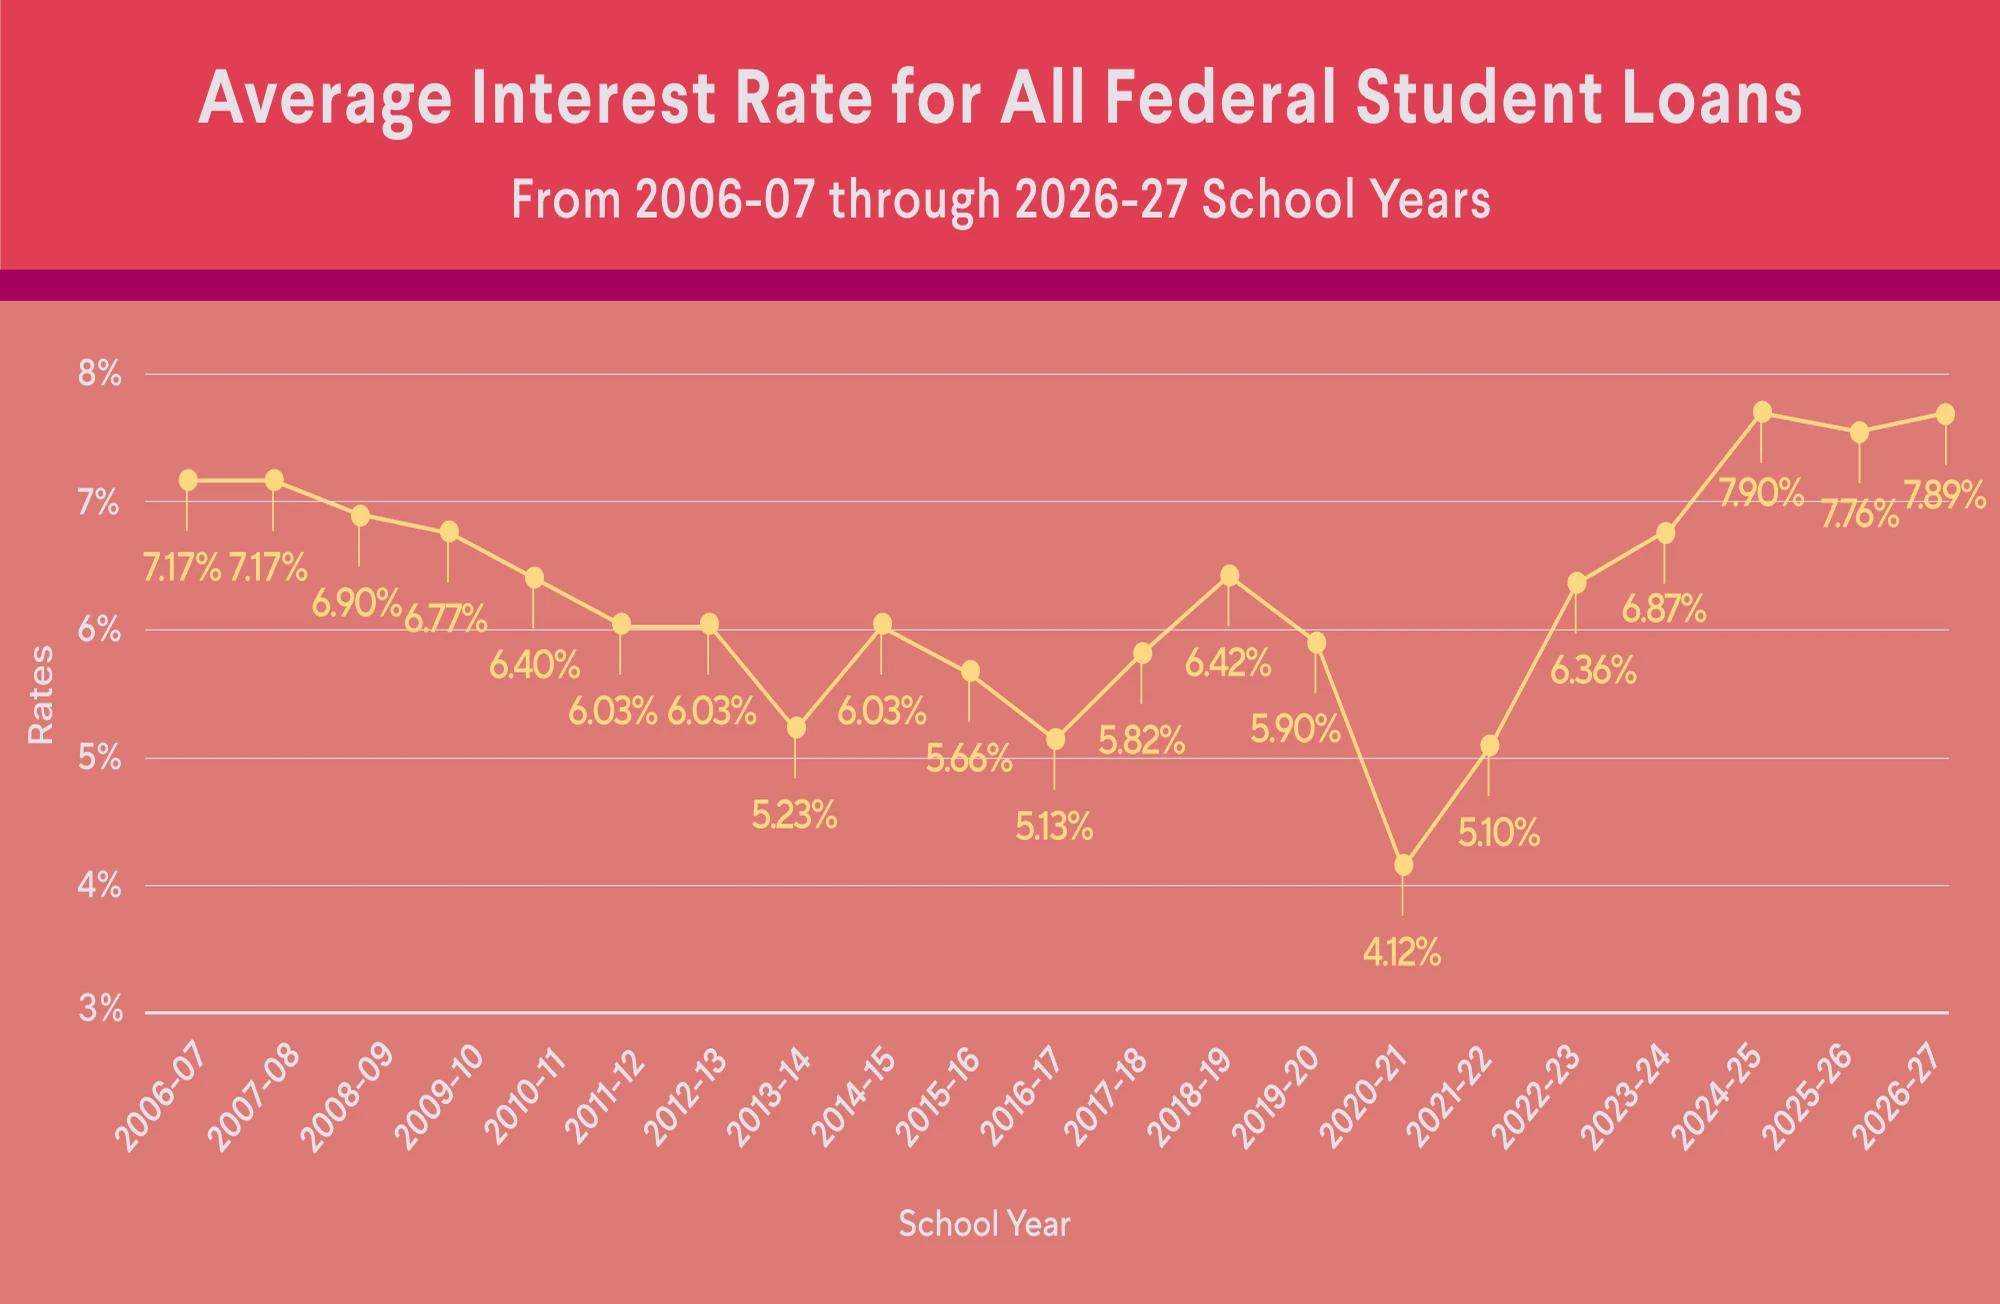
This means that the average student loan interest rate for the three main types of federal student loans is 7.89%, based on a simple average of the three rates.

Average Interest Rate for All Federal Student Loans

Source: Studentaid.gov

Private student loan interest rates vary by lender, and each has its own criteria for which rates borrowers qualify for. Private student loans can have either fixed interest rates that remain the same over the life of the loan, or variable rates that may start lower than a fixed interest rate but may change over time, based on market changes.

Private loans require a credit check, and lenders may offer different interest rates if you have strong credit or a cosigner on your student loan. The interest rates on private student loans can vary widely, depending on the lender, the type of loan, and on individual financial factors including the borrower’s credit history. Few borrowers qualify for the lowest advertised rates, which typically already factor in discounts such as one for enrolling in automatic payments.

Recommended: Do Student Loans Have Simple or Compound Interest?

How Are Interest Rates Determined?

As mentioned, the interest rates on federal student loans are set annually by formulas specified in the HEA. The rates are tied to the financial markets — federal law sets them based on the 10-year Treasury note and a statutory add-on percentage with a maximum rate cap.

Federal student loans first disbursed on or after July 1, 2006, have fixed interest rates. Although federal student loans are serviced by private companies or nonprofits selected by the federal government, these loan servicers have no say in the federal interest rate offered.

For private student loans, the lenders set their own rates, which may be influenced by broader market conditions. The rates quoted for student loans vary based on each applicant’s individual situation — though generally the better a potential borrower’s credit history is, the better rate they may be able to qualify for.

To learn more about private and federal student loans, check out our student loan help center.

How Student Loan Interest Is Calculated and Applied

Interest on federal student loans typically accrues daily. To calculate the interest as it accrues, the following formula can be used:

Interest amount = (outstanding student loan principal balance × interest rate factor) × days since last payment

In other words, you will multiply your outstanding loan balance by the “interest rate factor,” which is used to calculate the amount of interest that accrues on a student loan. Then, multiply that result by the days since you last made a payment.

To calculate the interest rate factor, you can divide the interest rate by the number of days in the year (365 or 365.25, depending on the servicer). For example, let’s say you have an outstanding student loan balance of $10,000, an interest rate of 4.75%, and it’s been 30 days since your last payment. Here’s how to calculate your interest:

$10,000 x (4.75%/365) = $1.30 daily interest charge
$1.30 x 30 days = $39
Interest amount $39

Many private student loans will also accrue interest on a daily basis. However, the lender ultimately sets the terms. Consider reviewing the lending agreement to confirm.

Recommended: Do Student Loans Count as Income?

How to Evaluate Student Loan Interest Rates

When you take out a federal student loan, you’ll receive a fixed interest rate. This means that your interest rate will stay the same for the term of the student loan. In addition, all of the terms, conditions, and benefits are determined by the government. Federal student loans also provide some additional perks that you may not find with private lenders, like deferment. Some deferment options won’t be available for federal loans made on or after July 1, 2027.

Private student loans can have higher interest rates and potentially fewer perks than federal student loans. You may want to take advantage of all federal student loans you qualify for before comparing private loan options.

One thing to keep in mind is that interest you pay on federal or qualifying private student loans may allow you to take the student loan interest deduction on your taxes.

What Is a Good Fixed Interest Rate for Student Loans?

The lower the interest rate, the less a borrower may owe over the life of the loan, which could help individuals as they work on other financial goals. If you’re taking out federal loans, the student loan interest rate is set by federal law, so you don’t have a choice for what is and isn’t a reasonable interest rate.

When it comes to private student loans, it may help to shop around and compare your options to find a suitable financing solution. Since every lender offers different terms, rates, and fees, getting quotes from multiple lenders may help you select an option that fits your personal needs. Keep in mind that the rate you receive on a private student loan is largely dependent on your credit score and other factors, whereas federal student loan interest rates are based on HEA formulas.

Also keep in mind that private student loans do not have the same borrower protections as federal student loans, including deferment options. Borrowers may want to consider them only after exhausting all federal aid options.

Ways to Lower Your Student Loan Interest Rate

The interest rate on federal student loans, while fixed for the life of the loan, changes from year to year for new loans. For example, the rates for Direct Subsidized and Unsubsidized loans for undergraduates more than doubled from 2.75% in 2020-21 to 6.52% in 2026–27.

To adjust the rate on an existing federal or private student loan, borrowers generally have two options. They can refinance student loans, which may lower the rate, or consolidate federal loans, which won’t.

Borrowers who refinance a federal loan with a private lender lose access to federal borrower protections such as income-driven repayment plans, federal deferment, and Public Service Loan Forgiveness.

The federal government does offer a Direct Consolidation Loan, which allows borrowers to consolidate their federal loans into a single loan. This will maintain many federal borrower protections but won’t necessarily lower the interest rate. Borrowers who consolidate on or after July 1, 2026, can only choose between the new Tiered Standard plan and the Repayment Assistance Plan (RAP). When federal loans are consolidated into a Direct Consolidation Loan, the new interest rate is a weighted average of your original federal student loans’ rates, rounded up to the nearest one-eighth of 1%.

Refinancing federal or private student loans with a private lender may allow qualifying borrowers to secure a lower interest rate or preferable loan terms. You may pay more interest over the life of the loan if you refinance with an extended term.

To see how refinancing could work for your student loans, consider using this student loan refinance calculator.

Fixed vs. Variable Interest Rates: Which Is Better?

Whether fixed or variable interest rates are better depends on a borrower’s specific situation. For many borrowers, fixed rates may be a better option because they are stable and predictable. Your payments won’t change, and you won’t have to worry about rate hikes. Borrowers may want to consider a private student loan with a fixed interest rate if interest rates are rising overall and they anticipate needing a number of years to repay their loan.

Because variable interest rates fluctuate with the market, they can be unpredictable. That means your payments can potentially change from one month to the next.

The Takeaway

The average student loan interest rate varies depending on the loan type. The interest rate for federal Direct Unsubsidized and Subsidized loans is set annually by federal law and fixed for the life of the loan.

The interest rate on private student loans is determined by a variety of factors including the borrower’s credit history and may vary widely by lender.

Looking to lower your monthly student loan payment? Refinancing may be one way to do it — by extending your loan term, getting a lower interest rate than what you currently have, or both. (Please note that refinancing federal loans makes them ineligible for federal forgiveness and protections. Also, lengthening your loan term may mean paying more in interest over the life of the loan.) SoFi student loan refinancing offers flexible terms that fit your budget.

With SoFi, refinancing is fast, easy, and all online. We offer competitive fixed and variable rates.

FAQ

How often do student loan interest rates change?

The rates on federal student loans are determined and set annually by formulas specified in the Higher Education Act of 1965. Private student loan rates vary by lender, and they may be fixed or variable. Private loans with variable rates can change based on market changes.

How do federal student loan interest rates compare to private loans?

The interest rate on federal student loans is often lower than the rates for private student loans. The rate you may qualify for with a private loan depends on your circumstances. If you have strong credit or a loan cosigner who has strong credit, you may be able to get a private loan with a lower interest rate.

Keep in mind that federal student loans have fixed interest rates, which means the interest rate and your monthly payment won’t change. Private student loans may have fixed or variable rates, and variable rates can go up or down with market changes.

Can I negotiate my student loan interest rate?

Federal student loans have fixed rates that are nonnegotiable. With a private student loan, your lender may have options if you’re struggling to make payments or dealing with financial hardship, though a lower interest rate isn’t guaranteed. Consider contacting your private lender and explain the situation.

What factors determine my student loan interest rate?

Federal student loans have a fixed interest rate that is determined and set each year based on formulas specified in the Higher Education Act of 1965. With private student loans, each lender sets their own rates. Private loans require a credit check, and the interest rates vary based on an applicant’s credit and other factors. Generally speaking, the stronger a borrower’s credit is (or if they have a loan cosigner with strong credit), the lower the rate they may be able to qualify for.

Is it better to choose a fixed or variable interest rate for student loans?

For many borrowers, fixed rates may be a better option because they are stable and predictable, which means the monthly payments won’t change over the life of the loan. If you are planning to repay your loan over a period of years, you may want to consider a private student loan with a fixed interest rate.

Variable interest rates fluctuate with the market, which makes them unpredictable. As a result, your payments can go up (or down), and may be harder to budget for.


About the author

Ashley Kilroy

Ashley Kilroy

Ashley Kilroy is a seasoned personal finance writer with 15 years of experience simplifying complex concepts for individuals seeking financial security. Her expertise has shined through in well-known publications like Rolling Stone, Forbes, SmartAsset, and Money Talks News. Read full bio.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOSLR-Q326-010

Read more
TLS 1.2 Encrypted
Equal Housing Lender