Someone writes down notes at a desk while using a laptop computer.

How to Calculate Dividend Yield: Meaning & Formula

Dividend yield is a financial ratio that shows how much a company pays in dividends each year relative to its stock price. It’s expressed as a percentage and helps investors evaluate income potential from dividends.

Dividend yield concerns how much an investor potentially realizes from their investments over the course of a year as a result of dividends. Dividends, which are payouts to investors as a share of a company’s overall profit, could help investors generate returns, and some investors even formulate entire strategies around maximizing dividends.

But it’s important to have a good understanding of dividends, dividend yields, and other related concepts before going too far into the weeds.

Key Points

•   Dividend yield represents the annual dividend paid to shareholders relative to the stock price, expressed as a percentage, which helps investors assess potential returns.

•   Investors can calculate dividend yield by dividing the annual dividend per share by the stock’s current price, providing insight into a company’s attractiveness as an investment.

•   A higher dividend yield may signal an established company, but it may also indicate slower growth or potential financial troubles, requiring careful evaluation.

•   Considering the history of dividend growth and the dividend payout ratio could provide additional insights into a company’s financial health and dividend sustainability.

•   Understanding the difference between dividend yield and dividend rate is essential, as dividend yield is a ratio while dividend rate is expressed in dollar amounts.

What Does Dividend Yield Mean?

A stock’s dividend yield is how much the company annually pays out in dividends to shareholders, relative to its stock price. The dividend yield is a financial ratio (dividend/price) expressed as a percentage, and is distinct from the dividend itself.

Dividend payments are expressed as a dollar amount, and supplement the return a stock produces over the course of a year. For an investor interested in total return, learning how to calculate dividend yield for different companies might help to decide which company may be a better investment.

But bear in mind that a stock’s dividend yield will tend to fluctuate because it’s based on the stock’s price, which rises and falls. That’s why a higher dividend yield may not be a sign of better value. This can all be important to understand if you plan to buy stocks online or otherwise start investing.

For more background, it may be helpful to review a beginner’s guide to the stock market.

How Does Dividend Yield Differ From Dividends?

It’s important to really drive home the difference between dividend yield and dividends in general.

Dividends are a portion of a company’s earnings paid to investors and expressed as a dollar amount. Dividends are typically paid out each quarter (although semi-annual and monthly payouts are common). Not all companies pay dividends.

Dividend yield, on the other hand, refers to a stock’s annual dividend payments divided by the stock’s current price, and expressed as a percentage. Dividend yield is one way of assessing a company’s earning potential.

How to Calculate Dividend Yield

Calculating the dividend yield of an investment is useful for investors who want to compare companies and the dividends they pay. For investors looking for investments to help supplement their cash flow, or even to possibly live off dividend income, a higher dividend yield on a stock would be more attractive than a lower one.

It may be helpful to experiment with a stock profit calculator to try and develop a deeper understanding of how this may affect overall potential returns.

What Is the Dividend Yield Formula?

The dividend yield formula is more of a basic calculation than a formula: Dividend yield is calculated by taking the annual dividend paid per share, and dividing it by the stock’s current price.

Annual dividend / stock price = Dividend yield (%)
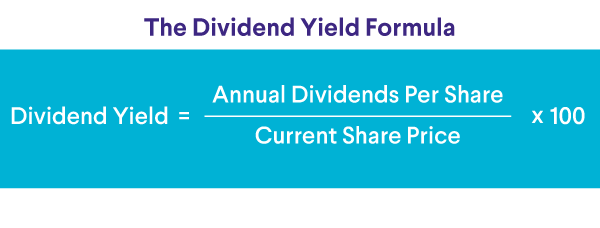
Dividend Yield Formula

How to Work Out Dividend Yield Step-by-Step

Investors can calculate the annual dividend of a given company by looking at its annual report, or its quarterly report, finding the dividend payout per quarter, and multiplying that number by four. For a stock with fluctuating dividend payments, it may make sense to take the four most recent quarterly dividends to arrive at the trailing annual dividend.

It’s important to consider how often dividends are paid out. If dividends are paid monthly vs. quarterly, you want to add up the last 12 months of dividends.

This is especially important because some companies pay uneven dividends, with the higher payouts toward the end of the year, for example. So you wouldn’t want to simply add up the last few dividend payments without checking to make sure the total represents an accurate annual dividend amount.

Example of Dividend Yield

If Company A’s stock trades at $70 today, and the company’s annual dividend is $2 per share, the dividend yield is 2.85% ($2 / $70 = 0.0285).

Compare that to Company B, which is trading at $40, also with an annual dividend of $2 per share. The dividend yield of Company B would be 5% ($2 / $40 = 0.05).

In theory, the higher yield of Company B may look more appealing to some investors. But investors can’t necessarily determine a stock’s worth by yield alone.

Start investing with up to $1,000 in stock.

Open and fund a SoFi Active Invest account and get up to $1,000 in stock.*


*Customer must fund their Active Invest account with at least $50 within 45 days of opening the account. Probability of customer receiving $1,000 is 0.028%. See full terms and conditions. Screen images simulated.

Dividend Yield: Pros and Cons

thumb_up

Pros:

•   May help with company valuation.

•   May indicate how much dividend income investors might expect.

thumb_down

Cons:

•   Dividend yield could indicate a more established, but slower-growing company.

•   Higher yield may mask deeper problems.

•   Yield doesn’t tell investors the type of dividend (ordinary vs. qualified), which could impact taxes.

For investors, there are some advantages and disadvantages to using dividend yield as a metric that helps inform investment choices.

Pros

•   From a valuation perspective, dividend yield may be a useful point of comparison. If a company’s dividend yield is substantially different from its industry peers, or from the company’s own typical levels, that could be an indicator of whether the company is trading at the right valuation.

•   For some investors, the primary reason to invest in dividend stocks is for income. In that respect, dividend yield could be an important metric. But dividend yield might change as the underlying stock price changes. So when using dividend yield as a way to evaluate income, it’s important to be aware of company fundamentals that provide assurance as to company stability and consistency of the dividend payout.

Cons

•   Sometimes a higher dividend yield could indicate slower growth. Companies with higher dividends are often larger, more established businesses. But that could also mean that dividend-generous companies are not growing very quickly because they’re not reinvesting their earnings. You can also learn more about dividend reinvestment plans.

Smaller companies with aggressive growth targets are less likely to offer dividends, but rather spend their excess capital on expansion. Thus, investors focused solely on dividend income could miss out on some faster-growing opportunities.

•   A high dividend yield could indicate a troubled company. Because of how dividend yield is calculated, the yield is higher as the stock price falls, so it’s important to evaluate whether there has been a downward price trend. Often, when a company is in trouble, one of the first things it is likely to reduce or eliminate is that dividend.

•   Investors need to look beyond yield to the type of dividend they might get. An investor might be getting high dividend payouts, but if they’re ordinary dividends vs. qualified dividends they’ll be taxed at a higher rate. Ordinary dividends are taxed as income; qualified dividends are taxed at the lower capital gains rate, which typically ranges from 0% to 20%. If you have tax questions about your investments, it may be helpful to consult with a tax professional.

The Difference Between Dividend Yield and Dividend Rate

A dividend is a way for a company to distribute some of its earnings among shareholders, as noted earlier. Dividends might be paid monthly, quarterly, semi-annually, or even annually (although quarterly payouts tend to be common in the U.S.). Dividends are expressed as dollar amounts. The dividend rate is the annual amount of the company’s dividend per share.

A company that pays $1 per share, quarterly, has an annual dividend rate of $4 per share.

The difference between this straight-up dollar amount and a company’s dividend yield is that the latter is a ratio. The dividend yield is the company’s annual dividend divided by the current stock price, and expressed as a percentage.

What Is a Good Dividend Yield?

dividend yield of sp500 vs dividend aristocrats

Two companies with the same high yields are not created equally. While dividend yield is an important number for investors to know when determining the annual cash flow they might expect from their investments, there are deeper indicators that investors may want to investigate to see if a dividend-paying stock will continue to pay in the future.

A History of Dividend Growth

When researching dividend stocks for a self-directed investment account, one place to start is by asking if the stock has a history of dividend growth. A regularly increasing dividend is an indication of earnings growth and typically a good indicator of a company’s overall financial health.

The Dividend Aristocracy

There is a group of S&P 500 stocks called Dividend Aristocrats, which have increased the dividends they pay for at least 25 consecutive years. Every year the list changes, as companies raise and lower their dividends.

As of writing, there are 69 companies that meet the basic criteria of increasing their dividend for a quarter century straight. They include big names in energy, industrial production, real estate, defense contractors, and more, which often resembles a list of blue chip stocks.

Dividend Payout Ratio (DPR)

Investors could calculate the dividend payout ratio by dividing the total dividends paid in a year by the company’s net income. By looking at this ratio over a period of years, investors may learn to differentiate among the dividend stocks in their portfolios.

A company with a relatively low DPR is paying dividends, while still investing heavily in the growth of its business. If a company’s DPR is rising, that’s a sign the company’s leadership likely sees more value in rewarding shareholders than in expanding. If its DPR is shrinking, it’s a sign that management sees an abundance of new opportunities abounding. In extreme cases, where a company’s DPR is 100% or higher, it’s unlikely that the company will be around for much longer.

Other Indicators of Company Health

Other factors to consider include the company’s debt load, credit rating, and the cash it keeps on hand to manage unexpected shocks. And as with every equity investment, it’s important to look at the company’s competitive position in its sector, the growth prospects of that sector as a whole, and how it fits into an investor’s overall plan. Those factors will ultimately determine the company’s ability to continue paying its dividend.


Test your understanding of what you just read.


The Takeaway

Dividend yield is a simple calculation: You divide the annual dividend paid per share by the stock’s current price. Dividend yield is expressed as a percentage, versus the dividend (or dividend rate) which is given as a dollar amount. The dividend yield formula may be a valuable tool for investors, and not just ones who are seeking cash flow from their investments.

Dividend yield could help assess a company’s valuation relative to its peers, but there are other factors to consider when researching stocks that pay out dividends. A history of dividend growth and a good dividend payout ratio (DPR), as well as the company’s debt load, cash on hand, and credit rating could help form an overall picture of a company’s health and probability of paying out higher dividends in the future.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

Can a stock’s dividend yield be negative?

Dividend yield cannot be negative, as that would effectively be shareholders paying a tax or fee – a stock may have no dividend yield, however. But if yield is below zero, then there is no yield at all.

Why do some profitable companies pay no dividends?

There can be a variety of reasons that profitable companies choose not to pay or issue dividends, but generally, it’s because they’re reinvesting earnings and profits in an effort to fuel further growth or expansion.

Are high dividend yield stocks always safe investments?

There is no such thing as a safe investment, but stocks with high dividend yields tend to be older or more established and stable, which some investors may translate as being associated with lower relative risk.

How often do companies update their dividend yields?

Dividend yields are often updated continuously, and in real-time, though it depends on the specific company or stock.

Does a stock split affect the dividend yield?

A stock split should not affect dividend yields as dividend per share and the actual share price should change or adjust proportionately.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
S&P 500 Index: The S&P 500 Index is a market-capitalization-weighted index of 500 leading publicly traded companies in the U.S. It is not an investment product, but a measure of U.S. equity performance. Historical performance of the S&P 500 Index does not guarantee similar results in the future. The historical return of the S&P 500 Index shown does not include the reinvestment of dividends or account for investment fees, expenses, or taxes, which would reduce actual returns.

SOIN-Q326-085

Read more
Presentation Of Chart With Pieces Of Doughnut

How to Buy Stock: Where and How Do You Purchase Stocks?

A stock is a share of ownership in a company. Theoretically, individuals may buy stock in a publicly traded company as long as they have access to an investment account.

In addition to buying shares of stock directly, it’s also possible to own stock through pooled investments, such as mutual funds or exchange-traded funds (ETFs). Investors who can’t afford a full share of stock in some higher-priced companies might choose to invest in a product known as fractional shares.

Read on to learn more about how to buy stock.

Key Points

•   Investors may buy or sell a stock in publicly traded companies via a public stock exchange.

•   Private companies may also issue shares of stock, but these are not available on public stock exchanges.

•   To buy a stock, an investor needs a brokerage account or a retirement account.

•   An investor might open an account at a full-service brokerage firm, a discount brokerage, an online platform, or a robo-advisor platform.

•   It’s possible to buy stocks through pooled investments like mutual funds and exchange-traded funds ( ETFs), or to invest in a fraction of a share of stock.

Where Can I Purchase Stock?

Individuals can purchase stocks through a brokerage account or a retirement account like an individual retirement account (IRA). You can set up an account at a full-service brokerage firm, which offers a variety of financial services including investment advisors; a discount brokerage that has fewer services and charges lower fees than a full-service brokerage; and an online brokerage that offers online trading and may charge even lower (or no) fees.

Once you choose the type of brokerage you want, set up an account, and fund it (typically, by transferring money into it from your bank account), you can begin buying stocks, including trading stocks online.

When choosing a brokerage, investors can compare the different options to help decide which one will best fit their needs. They can check into the investment fees brokerages may charge, such as maintenance fees, transaction fees, and commissions. Also, it’s wise to find out if there’s a minimum balance to start buying stocks. At some online brokerages, investors can get started with as little as $1 to $5.

How Do You Buy Stocks in 5 Steps?

There are generally five basic steps to buying stocks from start to finish. Here’s what they involve.

Step One: Think About What You Want to Buy

To start, investors may want to decide whether they’re interested in buying full shares of individual stocks, fractional shares of a stock, or investing in a fund, such as a mutual fund or exchange-traded fund (ETF).

Individual Stocks

A stock represents a share of ownership in a publicly traded company. Many companies offer both common and preferred stock.

•   Preferred stock generally does not come with voting rights, but dividend payments on these shares are prioritized over common stock dividend payments.

•   Common stock comes with voting rights. These shares may be more volatile, but might provide higher long-term returns. Common stock only pays dividends after preferred stock dividends are paid.

Stocks may provide a return on investment in two ways. The first is through potential price appreciation (though this is never guaranteed). The second is through dividend payments to shareholders, if applicable.

Ideally, shareholders may be able to benefit from a company’s share value increasing over time, as the company’s earnings and market presence expand. However, it’s very difficult to predict which stocks — and which businesses — will be successful in the future.

Individual stocks may be volatile and riskier than other types of investments, such as diversified index funds like the S&P 500 — although they may also provide the potential for higher rewards.

Fractional Shares

Fractional shares of stock offer investors the chance to buy a percentage of a share of stock, rather than owning a full share. Previously, fractional shares were available only to institutional investors, but now retail investors can also buy them, assuming their brokerage offers them.

Owning a fractional share of a stock allows investors to realize gains, losses, and even dividend payments proportional to the fractional ownership amount.

One reason an investor might choose fractional shares investing is to manage cost. Shares of certain companies can be expensive. For example a share of stock of a company worth $1,000 might be available to investors as a fractional share for $100 (a 0.1% share).

Funds

A fund, whether it’s an ETF or a mutual fund, might be thought of as a bundle of investments. Often, these funds invest in stocks, but they may also hold bonds, real estate, or cash. For example, it’s possible to buy an S&P 500 mutual fund or ETF that holds the stocks of the top 500 publicly traded companies in the U.S.

An investment in an ETF or mutual fund that invests in a wide range of stocks is generally considered less risky than owning individual stocks because funds generally offer broad market exposure and may help an investor diversify their portfolio. However, as with all investments, there is risk involved in investing in funds. Diversification doesn’t guarantee profits and it’s possible to lose money.

Start investing with up to $1,000 in stock.

Open and fund a SoFi Active Invest account and get up to $1,000 in stock.*

Prefer mobile? Download the app:

*Customer must fund their Active Invest account with at least $50 within 45 days of opening the account. Probability of customer receiving $1,000 is 0.028%. See full terms and conditions. Screen images simulated.

Step Two: Determine What Type of Account to Open

The next decision for an investor is whether to open a brokerage account or a retirement account.

There are several differences between a brokerage account and a retirement account, with one fundamental difference being the tax treatment of assets in these accounts.

•   Brokerage accounts allow investors to buy and sell securities. They are typically taxable accounts. There are no contribution limits or withdrawal penalties with brokerage accounts.

•   Retirement accounts are tax-advantaged accounts that can hold investments and savings. Tax-deferred accounts (like traditional IRAs) typically defer taxes on investment gains until retirement. With after-tax accounts, like Roth IRAs, qualified withdrawals are tax-free in retirement. However, retirement accounts have annual contribution limits as well as strict withdrawal rules.

Investors may choose to open a brokerage account if they’re already covered by a retirement plan through work like a 401(k). If they opt for a retirement account, investors could open a Roth IRA or a traditional IRA, or a SEP IRA if they’re self-employed.

Recommended: Understanding Dollar-Cost Averaging

Step Three: Decide Where to Open an Account

When it comes to deciding where to open an account, investors have plenty of options, including these:

•   Discount brokerage: One option is to open an account at a low-cost or discount brokerage. Depending on the firm, there may be account and trading fees, but these fees tend to be much lower than those charged by full-service brokerage firms.

•   Online trading platform: Another popular option is to use an online investment platform, where investors can buy shares of stocks and ETFs right from an app. Online trading platforms may offer low or no fees. These days, there is a great deal of overlap between discount and online brokerages, as the former moves increasingly online.

•   Robo-advisor platforms. These services offer automated investment portfolios that typically consist of low-cost ETFs or index funds rather than individual stocks. Robo-advisor platforms may help investors manage a portfolio over time through automated asset allocation and portfolio rebalancing.

•   Full-service brokerage firm: These firms tend to offer expanded services, such as advisors, brokers, and wealth management advisors who can help individuals execute trades, monitor their investments, and more. These services tend to come with much higher costs.

Once an investor has chosen a brokerage or platform, they can typically open an account online by providing information like their Social Security number, date of birth, address, and employment details.

Step Four: Fund Your Account With Cash

The next step in buying stock is to fund the account with cash. Depending on the institution, investors may be able to set up a link to an existing bank account to deposit money into their investment account.

Investors may also be able to sign up for an automated monthly transfer. In this way, money is deposited in the investment account regularly (without the need to remember to do so).

Another funding option is to use a brokerage’s cash management account, which usually offer a combination of checking and savings account features, and are linked to investment accounts.

Step Five: Place a Trade to Purchase Stock

Once the account is funded, an investor can navigate to the area of the dashboard or app that says either buy, sell, or trade.

Here, investors can indicate what stock they would like to buy and specify how many shares, typically using the ticker symbol (a short abbreviation for each stock or fund name).

If buying a stock or an ETF, investors may also need to indicate the order type, though the default is typically a market order — an instruction to buy or sell immediately at the best available current price. Both stocks and ETFs trade on an exchange, like the New York Stock Exchange or the Nasdaq. On these exchanges, prices fluctuate throughout the day. Mutual funds do not trade on an open exchange and their value is calculated once per day.

Recommended: Dividend Yield: What It Is

Understanding Market vs Limit Orders

There are different stock market order types. When purchasing stock, new investors may want to stick to the basics: either a market order or a limit order.

•   A market order will be executed as soon as possible, at the best available price. The order can fill quickly, but it may not be instantaneous. Therefore, the price could change slightly from the original quote. If an investor places a market order, they may want to have a slight cash cushion to protect from any erratic changes in price. If placing a market order while the market is closed, the order is typically filled at the market’s open, at whatever the prevailing price per share is at that time.

•   A limit order focuses on pricing precision. With a limit order, investors name the parameters for the order. For example, an investor could say that they only want to purchase a stock if it falls below $70 per share. Therefore, the order is placed if the stock falls below $70 per share. This means it’s possible a limit order won’t get filled if it doesn’t reach the investor’s pre-selected price parameters, but it also means the investor won’t pay more than they planned to.

Finally, an investor can execute the trade by pressing the “buy” button. Once the trade is executed, the investor then owns the stock.

The Takeaway

With today’s evolving technology, it’s relatively easy for individuals to buy stock. They might open an investment account at a brokerage or online platform of their choice, for example, and buy shares of company stock directly on a stock exchange.

Investors may also choose to buy a bundle of stocks or other assets through a mutual fund or ETF, or invest in fractional shares, in which they buy a percentage of a single share of stock. Each investor can determine what investments make the most sense for their specific financial situation and goals.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What is the minimum amount of money needed to buy stock?

An investor can often start buying stocks with very little money. Some brokerages allow individuals to begin investing, with as little as $1 to 5, for example. Many brokerage platforms also offer fractional investing that may allow investors to buy fractions of a share of stock for just a few dollars, depending on the price of the stock.

How do I buy stocks without a broker?

You can buy stocks without a traditional broker through an online trading platform. To do this, you could set up an investment account with a brick and mortar financial services firm, discount broker, or an online brokerage. Once you set up your account and fund it, you could start researching and buying stocks. If you wish to buy stocks directly on your own, you may explore direct stock plans or dividend reinvestment plans (DRIPs) offered by some companies.

How do you make money from owning stocks?

You have the potential to make money from owning stocks if you’re able to sell them for a higher price than you bought them for, though price appreciation is never guaranteed and it’s possible prices may decline instead. You may also make money from owning stocks if the company pays dividends, which is when a company periodically distributes a portion of their net earnings to shareholders. However, not all companies pay dividends.

Are there fees associated with purchasing stock?

There may be fees involved with purchasing stock, such as commission, transaction, and maintenance fees, depending on the type of brokerage or investment platform an investor uses. Full-service brokerage firms typically charge the highest fees, while discount brokerages usually charge less, and some online brokers have low or no fees.

Do you have to pay taxes on your stock investments?

When you sell a stock in a taxable brokerage account and make a profit on it, those earnings are generally subject to capital gains tax. The rate at which you’re taxed depends on how long you held the stock before selling it. Typically, if you held the stock for a year or less (short-term), you will be taxed at your ordinary income tax rate. If you held the stock longer than a year (long-term), you’ll be taxed at a rate ranging from 0%, 15%, or 20%, depending on your taxable income and filing status. Dividends from a stock are also generally taxable.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.
Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOIN-Q326-079

Read more
days of the month on pieces of paper.

Settlement Date vs Trade Date & How Long Settling Takes

The day a trader’s buy or sell order is executed in the market is known as the trade date. The settlement date is when the security and cash legally change hands, making the investor the official owner of the asset.

The period of time between the trade date (designated as “T”) and the settlement date varies by asset class. Following a regulatory update by the U.S. Securities and Exchange Commission (SEC), the standard settlement window for most securities — including stocks, bonds, and exchange-traded funds (ETFs) — moved from two business days (T+2) to a single business day (T+1).

Understanding this timeline is important for investors, as officially owning a security or waiting for transaction cash to clear directly impacts subsequent trading decisions and account cash management.

Key Points

•   The trade date is when the investor executes a trade; the settlement date is when the security legally changes hands.

•   Historically, paper trades were common, and the gap between the trade and settlement dates generally took five days, or T+5.

•   In 2017, the time between trade and settlement shifted to T+2, thanks to advances in technology.

•   In May of 2024, the SEC issued a new rule that most trades should settle within one business day (or T+1).

•   Given recent technological developments, some people believe T+0, or real-time settlement, is possible.

What Is a Settlement Date in Investing?

In investing, the settlement date is the specific day a transaction becomes final and the investor takes legal ownership of a security. For years, the standard settlement cycle for most assets was two business days after the trade date, known as T+2. However, following a regulatory shift by the SEC in May 2024, the financial markets transitioned to an accelerated timeline, compressing the standard settlement window down to just one business day (T+1).[1]

Types of Settlement Dates

Depending on the type of security involved in a trade or transaction, settlement dates may vary. That said, you can generally expect a settlement date to be one business day following the sale or purchase of a stock, bond, or ETF. This is sometimes referred to as “T+1,” meaning “trade date, plus one day” to settle.

While certain specialized transactions, such as primary market underwritings for newly issued debt, may utilize custom or extended settlement timelines, standard “regular way” trades for corporate, municipal, and government bonds now all adhere to this uniform T+1 standard.

Note that the time to settle is the same whether you’reinvesting online or through a traditional brokerage.

Trade and Settlement Dates Explained

To recap, the trade date is the specific day an investor’s buy or sell order is executed in the market. Once the order is filled, the price is locked in, and the investor assumes full market risk for the position. For example, if a stock order executes on a Tuesday, that Tuesday is the official trade date.

Following execution, the transaction undergoes an institutional clearing process. Under current regulatory standards, standard transactions for stocks, bonds, and ETFs require exactly one business day to complete. Therefore, a trade executed on Tuesday will legally settle on Wednesday, provided it is not a market holiday.

Why Is There a Delay Between Trade and Settlement Dates?

Given modern technology, it seems reasonable to assume that everything should happen instantaneously. But settlement rules go back decades, to the creation ofthe Securities and Exchange Commission (SEC) in 1934, when all trading happened in person, and on paper.

Back then, a piece of paper representing shares of a security had to be in the possession of traders in order to prove they actually owned theshares of stock. Paper transactions sometimes took as long as five business days after the trade date, or T+5.

Recommended: A Brief History of the Stock Market

Start investing with up to $1,000 in stock.

Open and fund a SoFi Active Invest account and get up to $1,000 in stock.*


*Customer must fund their Active Invest account with at least $50 within 45 days of opening the account. Probability of customer receiving $1,000 is 0.028%. See full terms and conditions. Screen images simulated.

What Is the T+1 Rule?

The T+1 rule refers to the fact that it now takes one day for a trade to settle. For example, if a trade is executed on Tuesday, the settlement date will be Wednesday.

Note that weekends and holidays are excluded from the T+1 rule. That’s because in the U.S.,stock exchanges are open from 9:30am to 4:00pm Eastern time Monday through Friday.

Before the T+1 rule took effect in 2024, the general rule for settlement dates was T+2.

What Investors Need to Know About T+1

The T+1 settlement rule applies uniformly to the trading of stocks, exchange-traded funds (ETFs), and some mutual funds. Bonds — including corporate, municipal, and government debt — also follow this identical timeline, meaning that standard “regular way” transactions across all these major asset classes clear and settle in exactly one business day.

Understanding the difference between the trade date and the settlement date is especially important for investors utilizing a cash account. In a cash account, investors can only trade using fully settled funds that are physically present in the account. In contrast, margin accounts allow investors to borrow funds directly from the brokerage firm to leverage trades or bypass settlement waiting periods by using their existing portfolio as collateral.

Because of these timelines, investors will often see two distinct figures describing the cash balance in their brokerage account: the settled balance and the unsettled balance. Settled cash refers to fully cleared funds that are immediately available for trading or withdrawal. Unsettled cash refers to the proceeds from a recent sale that have not yet legally cleared, but are scheduled to become fully settled on the following business day.

Are T+0, or Real-Time Settlement Dates Possible?

Many market experts are already looking beyond T+1, pushing for the settlement process to move even faster to improve trading conditions.

The momentum to shorten the settlement timeline gained traction following the extreme market volatility of 2020 and 2021. During the famous “meme stock” frenzies, the multi-day settlement delay exposed severe financial risks, forcing clearinghouses to demand billions in collateral from retail brokers. This structural bottleneck is what prompted regulators to accelerate the shift to a one-day cycle.

Moving all the way to T+0, or true real-time settlement, would require formal SEC approval and a large technological overhaul across dozens of Wall Street institutions. However, the instant transactions made possible in the cryptocurrency market by blockchain technology have permanently shifted the conversation, suggesting that real-time traditional securities markets may be a realistic goal for the future.

Potential Violations of the Trade Date vs Settlement Date

Knowing the difference between trade date vs. settlement date can allow investors to avoid potentially costly trading violations.

The consequences of these violations can differ according to which brokerage an investor uses, but the general concept still applies. Violations all have one thing in common: They involve the attempted use of cash or shares that have yet to come under ownership in an investor’s account.

Cash-Liquidation Violation

To buy a security, brokerages typically require investors to have enough settled cash in an account to cover the cost. Trying to buy securities with unsettled cash can lead to a cash-liquidation violation, asliquidating a security to pay for another requires settlement of the first transaction before the other can happen.

Let’s look at a hypothetical example: Say Mira wants to buy $1,000 worth of ABC stock. On Monday, Mira has no settled cash in her account, but she goes ahead and places the buy order anyway. Under the T+1 rule, her purchase of ABC is scheduled to legally settle on Tuesday.

On Tuesday, needing to cover the cost of her purchase, Mira raises funds by selling $1,200 worth of XYZ stock that she already owned.

However, because she sold the XYZ stock on Tuesday, those proceeds will not settle until Wednesday. Since her ABC purchase settled on Tuesday and she lacked the settled cash to cover it on that exact day, a cash-liquidation violation occurred. Investors who face this kind of violation three times in one year can have their accounts restricted for up to 90 days.

Freeriding Violation

A freeriding violation occurs when an investor buys a stock or ETF and then sells that exact same security to pay for the initial purchase before ever depositing the cash required to cover the buy order. Essentially, the investor is trying to pocket a profit without ever risking their own money.

For example, say Jay buys $1,000 worth of ABC stock on Tuesday morning with $0 in his cash account. Under the T+1 rule, Jay must deposit $1,000 in settled cash by Wednesday to pay for the trade. However, later on Tuesday afternoon, ABC stock jumps in value, and Jay sells the shares for $1,100.

Because Jay used the proceeds of the sale to cover the cost of the original purchase instead of depositing his own cash, he committed a freeriding violation. Under Federal Reserve Regulation T, incurring just one freeriding violation results in an immediate 90-day restriction, forcing the investor to trade exclusively with fully settled cash.

Good-Faith Violation

For example, say an investor sells $1,000 worth of ABC stock on Tuesday morning. Later that afternoon, they use those unsettled proceeds to buy $1,000 worth of XYZ stock. This is perfectly legal.

However, if XYZ stock suddenly spikes on Tuesday afternoon and the investor sells the XYZ shares that same day, they will incur a good-faith violation. This is because they sold XYZ before the cash used to buy it (the proceeds from the ABC sale) officially settled on Wednesday morning.

With these examples in mind, it’s not hard for active traders to run into problems if they don’t understand cash-account trading rules, all of which derive from trade date vs. settlement date. Having adequate settled cash in an account can help avoid issues like these.

Settlement Date Risks

Given that a lag exists between the trade date and settlement date, there are risks for traders and investors to be aware of — namely, settlement risk and credit risk.

Settlement Risk

Settlement risk occurs when one party in a transaction fails to deliver on their end of the deal — either by failing to hand over the security or failing to pay for it on the settlement date. In a default scenario, the counterparty faces the risk of financial loss or losing their assets without receiving the agreed-upon payment.

For standard trades on major U.S. stock exchanges, central clearinghouses step in to legally guarantee transactions, effectively eliminating this risk for everyday retail investors. However, settlement risk remains a significant factor in over-the-counter (OTC) markets and foreign exchanges, where competing time zones, cross-border banking delays, and differing regulatory systems make simultaneous settlement much harder to synchronize.

Credit Risk

Credit risk involves potential losses suffered due to a counterparty’s inability to meet their long-term financial obligations. However, when a specific trade is executed and a buyer’s funds are not transferred before the settlement date, this credit risk manifests as settlement risk. When this happens, it causes an immediate interruption in the clearing process and can result in the transaction being canceled altogether.

History of Settlement Dates

The SEC makes the rules regarding how stock markets operate, including trades, and evenwhat a broker does in regard to retail investing. As such, the SEC is tasked with creating the clearance and settlement system — a power it was granted back in the mid-1970s.

Prior to the SEC’s involvement, exchanges and transfers of security ownership were left up to participants, with sellers delivering stock certificates through the mail or even by hand in exchange for payment. That could take a long time, and prices could move a lot, so the SEC came in and set the settlement date at five business days following the trade date.

But as technology has progressed, transactions have been able to execute faster. In 1993, the SEC changed the settlement date to three business days, and in 2017, it was changed to two days. In 2024, it was officially made T+1.

The Takeaway

The trade date is the day an investor or trader books an order to buy or sell a security, and the settlement date is when the legal exchange of ownership actually happens. For many securities in financial markets, the T+1 rule now applies, meaning the settlement date is usually one business day after the trade date — not including weekends or holidays. An investor therefore will not legally own the security until the settlement date.

While there’s been chatter that the settlement process needs to speed up to real-time settlement, it’s still important for investors and traders to know these rules so they don’t make violations that lead to restricted trading or other penalties.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What’s the difference between trade date and settlement date?

The trade date is the day an investor’s buy or sell order is executed in the market. The settlement date is when the cash and securities legally change hands, making the investor the official owner of the asset. Under current SEC regulations, standard settlement occurs exactly one business day after the trade date (known as T+1).

Is the settlement date the issue date?

No, these are fundamentally different concepts, though they can occasionally overlap. The issue date is the day a brand-new security (like a newly minted bond or an IPO stock) is first created and made available to the public. The settlement date applies to every subsequent trade of that asset on the secondary market, representing the day-to-day completion of individual buy and sell transactions.

Why does it take one day to settle a trade?

Even though electronic trading feels instant, the one-day window is a necessary buffer for the broader financial system. Behind the scenes, individual brokerages, clearinghouses (like the DTCC), and institutional banks must spend that day matching trade details, verifying account funding, moving cash across central banking net systems, and legally transferring security titles between counterparties.

Article Sources


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.

SOIN-Q426-080

Read more
String and thumb tacks create a “T” shape on a blue background.

What is Regulation T? Reg T Margin Requirements & Calls

Regulation T, often shortened to “Reg T,” refers to Federal Reserve Board rules that dictate how much credit broker-dealers might extend to investors via margin accounts. Reg T also governs certain cash transactions. Trading on margin is a high-risk strategy that involves qualified investors borrowing funds from their brokerage, usually in an effort to place bigger trades.

In margin trading, Regulation T allows investors to borrow up to 50% of a trade, with cash or equity covering the other 50% (a.k.a., initial margin). An investor who fails to meet the initial margin requirements may be subject to a Reg T call, which is one type of margin call. Understanding Regulation T, and Regulation T calls, is important when trading securities on margin.

Key Points

•   Regulation T (Reg T) is a Federal Reserve Board rule that limits the credit brokerages might extend to investors for margin trading; it also covers certain cash transactions.

•   Margin trading enables investors to borrow money from their brokerage to take bigger positions, using their account assets as collateral.

•   Reg T establishes the initial margin requirement, limiting the amount an investor could borrow to a maximum of 50% of the security’s purchase price.

•   The regulation functions as a risk management tool to limit potential losses for investors and ensure they contribute some of their own capital to the trade.

•   A Reg T call is issued when an investor fails to meet the 50% initial margin requirement, restricting further trades until the deposit is made or securities are sold off by the brokerage.

Understanding Regulation the T Framework

Regulation T is issued by the Federal Reserve Board, pursuant to the 1934 Securities Exchange Act. The purpose of Reg T is to regulate how brokerage firms and broker dealers extend credit to investors in margin trading transactions. Specifically, regulation T governs initial margin requirements, as well as payment rules that apply to certain types of securities transactions.

Increase your buying power with a margin loan from SoFi.

Borrow against your current investments at 5.00% to 9.75% based on loan size* and start margin trading.

*For full margin details, see terms.


How Reg T Works

Regulation T’s main function is to limit the amount of credit a brokerage might extend. It’s also used to regulate prohibited activity in cash accounts, which are separate from margin accounts.

For example, an investor cannot use a cash account to buy a stock then sell it before the trade settles under Reg T rules, a violation known as freeriding. It may be beneficial to review the basics of leveraged trading to deepen your understanding, too.

Regulation T works by establishing certain requirements for trading on margin. Specifically, there are three thresholds investors are required to observe when margin buying, one of which, called initial margin, is directly determined by Regulation T.

Minimum Margin Requirement

One of the thresholds required for margin trading is minimum margin, which represents the amount an investor must deposit with their brokerage before opening a margin account. Under FINRA rules, this amount must be $2,000 or 100% of the purchase price of the margin securities, whichever is less. Keep in mind that this is FINRA’s rule, and that some brokerages may require a higher minimum margin.

Maintenance Margin Requirements

Another threshold, maintenance margin, represents the minimum amount of margin equity that must be held in the account at all times. If you don’t know what margin equity is, it’s the value of the securities held in your margin account less the amount you owe to the brokerage firm.

FINRA sets the minimum maintenance margin at 25% of the total market value of margin securities though brokerages could establish higher limits.

Initial Margin Requirements

The third margin threshold, called initial margin, is covered by Reg T and represents the amount an investor is allowed to borrow. Regulation T sets the maximum at 50% of the purchase price of margin securities. Again, brokerage firms may require investors to make a larger initial margin deposit, which may vary depending on the type of asset or level of risk involved.

Recommended: What Is Leveraged Trading?

Why Regulation T Exists

Margin trading could be risky, and Regulation T is intended to limit an investor’s potential losses. If an investor were able to borrow an unlimited amount of credit from their brokerage account to trade, they could potentially realize much larger losses over time if their investments fail to pay off.

Regulation T is also designed so that investors have some skin in the game, so to speak, by requiring them to use some of their own money to invest. This could be seen as an indirect means of risk management, since an investor who’s using at least some of their own money to trade on margin may be more likely to calculate risk/reward potential and avoid reckless decision-making.

Example of Regulation T in Practice

Regulation T establishes a 50% baseline for the amount an investor is required to deposit with a brokerage before trading on margin. For example, say you want to open a margin account. You make the minimum margin deposit of $2,000, as required by FINRA.

Next, you want to purchase 100 shares of stock valued at $100 each, which result in a total purchase price of $10,000.

Under Regulation T, the most you’d be able to borrow from your brokerage to complete the trade is $5,000. You’d have to deposit another $5,000 of your own money into your brokerage account to meet the initial margin requirement. Or, if your brokerage sets the bar higher at 60% initial margin, you’d need to put up $6,000 in order to borrow the remaining $4,000.

What Is a Reg T Call?

Understanding the initial margin requirements is important for avoiding a Regulation T margin call. In general, a margin call happens when you fail to meet your brokerage’s requirements for trading in a margin account. Reg T calls occur when you fall short of the initial margin requirements. This could happen, for instance, if you’re trading options on margin or if you have an ACH deposit transaction that’s later reversed.

Regulation T margin calls are problematic, especially for self-directed investing, because you can’t make any additional trades in your account until you deposit money to meet the 50% initial margin requirement. If you don’t have cash on hand to deposit, then the brokerage could sell off securities in your account until the initial margin requirement is met.

Brokerages don’t always have to ask your permission to do this. They may not have to notify you first that they intend to sell your securities either. That’s why it’s important to fully understand the Reg T requirements to ensure that your account is always in good standing with regard to initial margin limits.

How to Handle a Reg T Call

If you receive a Reg T margin call, it’s important to respond quickly. While federal regulations allow a maximum window (typically up to three business days from the trade date) to satisfy the call, many brokerages enforce stricter “house rules” that require a faster response. To resolve a Reg T call, you generally have two main choices:

•   Deposit Settled Cash: The cleanest and fastest way to meet the call is to wire or transfer settled cash directly into your account to cover the full dollar amount of the deficit.

•   Deposit Margin-Eligible Securities: You can transfer fully paid, marginable securities from another brokerage account. Keep in mind that marginable stocks typically only provide a certain percentage of their market value toward the requirement, so you typically need to deposit securities worth more the cash deficit, as determined by the brokerage.

•   Selling Securities in Your Account: While this is an option, investors must typically sell securities with a value that’s substantially higher than the value of the call, depending on the house requirement.

Recommended: Stock Market Basics

The Takeaway

Regulation T is used to determine initial margin requirements — i.e., the amount of cash or equity an investor must keep available in their account, relative to the amount they’ve borrowed. Margin trading may be profitable for investors, though it’s important to understand the risks involved. Specifically, investors need to know what could trigger a Regulation T margin call, and what that might mean for their portfolios.

An investor who fails to meet the initial margin requirements may be subject to a Reg T call, which is problematic because they are restricted from making additional trades until they deposit the 50% initial margin requirement. If the investor doesn’t have cash on hand to deposit, then the brokerage can sell off securities in the account until the initial margin requirement is met.

If you’re an experienced trader and have the risk tolerance to try out trading on margin, consider enabling a SoFi margin account. With a SoFi margin account, experienced investors can take advantage of more investment opportunities, and potentially increase returns. That said, margin trading is a high-risk endeavor, and using margin loans can amplify losses as well as gains.

Get one of the most competitive margin loan rates with SoFi, from 5.00% to 9.75%*

FAQ

Does Regulation T apply to cash accounts?

Regulation T does apply to cash accounts in that it dictates how transactions and payments are handled. Specifically, there are rules related to making full payments for securities from cash accounts (no borrowed funds), and no free-riding, or buying and then selling a security before you’ve paid for it in full.

What is the difference between Reg T and maintenance margin?

Reg T dictates initial margin, or the percentage of a purchase price investors need to pay with their own money to open a position. Maintenance margin, on the other hand, refers to the minimum equity investors need to keep in their account after the purchase. They’re somewhat related, but distinct.

Can you buy options on margin under Regulation T?

Options contracts cannot be purchased on margin. Margin rules for options trading differ from those that apply to buying stocks or futures on margin. Options traders must pay the full premium to buy options contracts. Options margin is still required, but it’s provided by investors as collateral for a trade rather than a percentage of the purchase price.

What happens if you ignore a Reg T call?

If an investor ignores a Reg T call, it’s possible that their brokerage will sell off or liquidate their securities in their account in order to cover the shortfall, and could also bar them from trading in the future.

How often do Regulation T requirements change?

Regulation T requirements are amended on occasion, and were most recently changed in April 2026, related to specific designations and minimum equity thresholds.


Photo credit: iStock/loveguli


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOIN-Q326-086

Read more
Guide to Personal Loan Agreements

How to Write a Personal Loan Agreement

Your personal loan agreement is the document that contains everything you need to know about the deal you’re making with your lender, including your rights and responsibilities as well as theirs. It’s a fairly long and complex form, but breaking it down can make it easier to understand.

Here, take a closer look at personal loan agreements and how to draw up a personal loan agreement should you decide to do it yourself.

Key Points

•   A personal loan agreement outlines terms and conditions, providing legal protection for both the lender and the borrower.

•   Key elements include parties, loan amount, interest rate, repayment terms, default provisions, governing law, and signatures.

•   Steps to write a personal loan agreement include choosing to DIY or work with a lawyer, gathering details, agreeing on terms, listing payment and legal details, and signing.

•   Additional documents for loan approval typically include proof of identity, income verification, and proof of address.

•   A personal loan agreement is legally binding and enforceable in court if obligations are not met.

Personal Loan Agreements Defined

A personal loan agreement, as mentioned above, is a document that details exactly what is being agreed to on both sides of a personal loan: lender and borrower. At the very least, it will state how much money is being loaned and the terms and conditions of the borrower’s repayment responsibilities.

But what about a personal loan that is not with a traditional lender? Private lenders can be individuals or organizations that make loans to individuals, sometimes without the qualification requirements of traditional lending institutions. A private personal loan agreement is drafted as part of a private personal loan, one made between a private lender and a borrower.

Any personal loan agreement is a legally binding document, so it’s important to understand it in full before you apply your signature.

Key Elements of a Personal Loan Agreement

Say you’ve applied for a personal loan. If you qualify, you’ll move along to a personal loan agreement. Among the key elements of a personal loan agreement are:

•   Parties involved: These include the lender and borrower, including their legal names and addresses.

•   Loan amount: This is the amount of money being borrowed, also known as the principal.

•   Interest rate: This is typically expressed as an annual percentage rate (APR), which reflects the total cost of borrowing over a year. If you don’t understand APR vs interest rate differences, this is a good time to learn.

•   Repayment terms: These include how and when the loan will be repaid, including the payment schedule, payment frequency, and loan term.

•   Default provisions: These are the consequences of failing to make payments, such as late fees and potential actions the lender can take. Also, you may want to be sure severability clauses are spelled out, stating what happens if one aspect of the agreement is deemed unenforceable.

•   Governing law: This specifies which jurisdiction’s laws will govern the agreement in the event that there are disputes.

•   Signatures and date: These are needed from both the lender and borrower.

You might also include details on any loan collateral, late and early payment (prepayment) penalties, and guarantors or cosigners, as needed.

Secured vs Unsecured Personal Loans

Most personal loans are unsecured, meaning no collateral is required from the borrower. But at times, a personal loan can be secured by property, such as a car. Collateral can also be an asset such as a savings account or certificate of deposit. Collateral might be required if a borrower has a less-then-stellar credit score.

When a loan is secured with collateral, the lender can take possession of the collateral if the borrower fails to make their loan payments.

Why Is a Loan Agreement Needed?

A personal loan agreement is essentially a protective document. It protects both the lender and the borrower by laying out, in clear terms, exactly what is being agreed to. If either party fails to uphold the agreement, action can be taken — such as the lender seizing any assets offered as collateral or sending the account to collections — both of which, obviously, would be bad for the borrower.

But the document works both ways. Lenders, too, are subject to lender liability and can be taken to court if they fail to uphold their end of the loan agreement. Although these cases are far less common than borrower default, the loan agreement is a document that can be used for the borrower’s protection as well.

How to Write a Personal Loan Agreement in 5 Steps

If you’ve been wondering how to draw up a personal loan agreement, here are the usual steps:

1. Decide Whether to DIY It or Hire a Lawyer

Loan paperwork is often created by the lending institution. For private loans, depending on the specifics of your loan and situation, you could write up a simple agreement by hand or draft it on your computer and then print it out for signing if you are working toward a private loan. Or you might download a template from a reputable site, which can be a popular option. Both are often at no cost or sometimes a small fee.

However, if the loan is complicated or you don’t want to handle the agreement yourself, you could look into hiring a lawyer to draw up the paperwork. Either way, a personal loan agreement will be a legally binding arrangement. Hiring a lawyer will likely be a costlier proposition.

2. Gather the Necessary Personal Details

You will need the legal names and addresses of both parties. This ensures the lender can’t ask you for anything beyond the borrowed principal (plus interest, which will also be listed).

3. Agree to and Spell Out the Loan Terms

The loan agreement should list the payments that will be expected each month and the expected date of the conclusion of the loan term. You can use a personal loan calculator to see what the monthly amount should be.

The interest rate for the personal loan should also be on the personal loan agreement, likely expressed as an APR, which shows what percentage of the loan principal you’ll end up paying back in the course of one year, including interest and any additional fees that may be packaged into the loan. What is a high interest rate vs. a low one will depend on the market so keep an eye on published rates.

The interest rate will vary based on your credit score and other financial factors. If you have decent credit, you’ll likely be able to qualify for a personal loan. But generally speaking, the higher your score, the lower your rate.

Recommended: Personal Loans Glossary

4. List Payment and Legal Details

A personal loan agreement should also include the following, as noted above:

•   The loan agreement may list which types of payment are acceptable, such as check, bank transfer, or credit card.

•   The personal loan contract should also list specific repayment conditions, including when payment is due and whether or not additional principal can be applied without penalty.

•   A complete personal loan agreement should include details on how any disputes will be handled between the parties involved.

•   Some personal loan documents may include the option to change your loan’s term (the period over which the loan is repaid).

•   Personal loan contracts in the United States should stipulate which state’s laws will be used to govern and interpret the agreement if the borrower lives in a different state than the lender is headquartered.

•   The contract should have a severability clause that states that even if one part of a contract is found to be unenforceable or otherwise rendered null and void, the remainder of the agreement will still hold.

•   The contract should list any penalties associated with the personal loan, such as late fees that may be assessed, at what point the loan will go into arrears or default, or other scenarios.

5. Sign the Document

Finally, the contract for loaning money must be signed by the borrower and the lender in order to be made legally binding.

Recommended: Comparing Personal Loans vs Business Loans

Other Personal Loan Documents

Along with the signed personal loan agreement, other typical personal loan requirements include the following:

Proof of Identity

Your driver’s license or some equivalent form of photo ID will likely be necessary in order to verify your identity.

Income Verification

Lenders will consider your income when qualifying you for a loan. After all, they have good reason to be interested in whether or not you’ll be able to repay the debt. Along with asking you to list your annual income, verifying documents such as tax returns may also be required.

Proof of Address

In order to prove your residence, and therefore eligibility for any type of personal loan, you may need to provide utility statements, bank statements, or other official documents.

The Takeaway

If you’re considering a personal loan, reading the loan agreement in depth is a good way to understand for sure what you’re agreeing to. That loan agreement will contain many details about funds borrowed and how they will be repaid, and it serves to protect both the lender and the borrower.

Think twice before turning to high-interest credit cards. Consider a SoFi personal loan instead. SoFi offers competitive fixed rates and same-day funding. See your rate in minutes.

SoFi’s Personal Loan was named a NerdWallet 2026 winner for Best Personal Loan for Large Loan Amounts.

FAQ

Does a personal loan agreement need to be notarized?

No, a personal loan agreement does not need to be notarized to be legally binding. It simply needs to be signed by each party to the agreement.

What is a private personal loan agreement?

A private personal loan agreement is the binding legal contract between a borrower and a private lender for a personal loan. Depending on the specifics of your situation, this document can be written by hand, drafted on a computer, or created using a downloaded template.

Why do you need a loan agreement?

The personal loan agreement serves to outline the specific terms of the loan and protect both parties in case either fails to uphold the agreement. It establishes legally enforceable terms for the lender while safeguarding the borrower by ensuring the lender cannot demand payments beyond the agreed-upon principal, interest, and fees.

Can a personal loan agreement be legally enforced?

Yes, a written and signed agreement for a loan can be legally enforced. It’s a binding contract.

What happens if a borrower defaults on a personal loan agreement?

If a borrower defaults on a personal loan, they will face negative impacts on their credit score, potential legal action from the lender, and they might find that their account is turned over to collections. They might also be charged late fees and a higher interest rate on the remaining balance due.


Photo credit: iStock/Chaay_Tee


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

This article is not intended to be legal advice. Please consult an attorney for advice.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOPL-Q426-008

Read more
TLS 1.2 Encrypted
Equal Housing Lender