Someone standing and smiling outside on a busy street.

Ultimate Guide to Retirement Planning for Millennials

As millennials enter their 30s and 40s, retirement suddenly doesn’t seem as far off as it once did. In fact, many millennials hope to retire early, according to one recent survey — meaning years before the traditional retirement age of 65.

American adults, including millennials, believe they’ll need $1.46 million to be comfortable in retirement, according to a 2026 study by Northwestern Mutual. But they’ve got a long way to go to reach that number: Just 28% of millennials have saved at least 4x their current annual income for retirement, and 20% of millennials have saved less than 1x their income, the research found.

No matter what your specific retirement goal is, ramping up millennial retirement savings now could pay off. The sooner an individual starts saving for retirement, the more time their money potentially has to grow. Read on for ways to kickstart retirement savings — and some common mistakes to avoid — in our millennial’s guide to retirement planning.

Key Points

•   Saving early and consistently for retirement may help millennials take advantage of compounding returns and meet long-term financial goals.

•   Creating a budget helps manage expenses and allocate funds for retirement.

•   Retirement savings account options include a workplace 401(k), an IRA, or a brokerage account.

•   Understanding risk tolerance may help investors make informed investment decisions.

•   Diversifying investments is a way to spread money out across a range of assets to potentially reduce the risk of losses.

Why Retirement Planning Matters for Millennials

Since young adulthood, millennials have faced a series of financial challenges. They have an average of $32,911 in student loan debt, according to the Education Data Initiative. They often struggled to find jobs during the Great Recession, and when they did land a position, their wages typically stagnated. Then, during their peak earning years, the Covid pandemic hit, and a large chunk of the economy slowed or shut down.

In addition, home prices have skyrocketed since 2020, putting homeownership out of reach for many millennials. Rents have also risen sharply, taking a chunk of their paychecks. Add to that increases in the cost of living across the board and rising credit card debt, and it’s no wonder millennials find themselves falling behind.

Faced with so many financial pressures, millennials may feel that saving for retirement is less of a priority because it’s far in the future. But that’s a misconception. In order to amass enough retirement savings, an individual generally needs to routinely put money away for at least 25 years, and ideally, even longer. Starting now on a millennial retirement savings plan could make all the difference.

Setting Your Retirement Goals: What Does Your Future Look Like?

According to the SoFi Retirement Survey, 75% of Americans don’t know how much they’ll need to retire. Before you can understand how much to save for your post-work years, you need to figure out what you’d like your retirement to look like. Do you hope to travel? Would you like to relocate to another part of the country — or move to a different country altogether? Or are you planning to downsize and move to a smaller home in the same general area?

Envisioning the lifestyle you hope to have in retirement can help you calculate what your retirement costs might be.

How to Determine How Much You Need to Retire

There isn’t one millennial retirement savings amount that will work for everyone. How much you need to retire depends on your unique situation. However, there are several rules of thumb you may want to consider as ballpark estimates.

•   The 4% rule: The 4% rule suggests that retirees can withdraw 4% of their savings in the first year of retirement, and then adjust that amount for inflation in subsequent years, to help ensure their savings will last for 30 years. You can also use this rule to help figure out how much you may need to set aside for retirement. To do this, you estimate what your annual retirement costs will be and divide that number by 4%. For example, if you believe your annual retirement expenses will be $60,000, dividing that number by 0.04 would result in $1.5 million. That would be your retirement savings goal.

•   The 80% rule: This rule says retirees should aim to replace 80% of their pre-retirement income to maintain a similar standard of living. So if you’re earning $120,000, you would aim to have enough retirement income, from savings and other sources like Social Security, to generate $96,000 per year.

•   Age-based savings rule: Another guideline offers rough targets for retirement savings based on your age as follows:

By age … You should have saved …
30 1x your salary
35 2x your salary
40 3x your salary
45 4x your salary
50 6x your salary
55 7x your salary
60 8x your salary
67 10x your salary

Remember, each of these three rules offers only rough amounts or guidelines for the amount you’ll need to save. But they can give you a starting point for estimating your retirement savings.

Average Retirement Age for Millennials

The average retirement age in the U.S. is 61, according to a 2026 poll by Gallup. As noted earlier, many millennials hope to retire earlier. That means the oldest millennials, who are 45 in 2026, have approximately 15 years or less to save for retirement.

Understanding Your Retirement Savings Options

Whether you’re just starting to save for retirement as a millennial, or you’ve already started saving but want to kick your efforts up a notch, there are a number of different types of retirement plans you can consider.

Employer-Sponsored Plans (401(k), 403(b))

You can sign up for an employer-sponsored retirement plan if your workplace offers one. This might be a 401(k) plan if your company is for-profit, or a 403(b) if your employer is a nonprofit.

With employer-sponsored plans, you decide how much you want to contribute, and your contributions are typically automatically deducted from your paycheck. This can help you save without even thinking about it. Individuals under age 50 can contribute up to $24,500 in a 401(k) in 2026.

Additionally, your employer may offer a 401(k) match, which means they match your contributions up to a certain percentage. That’s basically “free money,” so if your workplace offers 401(k) matching, it’s a good idea to participate.

You may be able to direct how you want to invest the money you contribute to your 401(k) by choosing from a number of options offered by the plan, which may include stocks, bonds, and mutual funds, and exchange-traded funds (ETFs).

For those who are self-employed, there are solo 401(k) plans to help them save for retirement. The way these plans work is similar to a traditional 401(k), but solo 401(k)s are specifically for individuals who run a business by themselves or only employ their spouse.

Nonprofits may offer their employers a 403(b) plan, which is also similar to a 401(k). As with a 401(k), your employer may or may not offer matching contributions. However, your investment options with a 403(b) may be more limited than the investment options in a 401(k).

Individual Retirement Accounts (IRAs)

Another option for saving for retirement is an individual retirement account, or IRA. Freelancers or contract workers may want to consider opening an IRA, and so might millennials who don’t have a workplace retirement plan, or who have maxed out their employer-sponsored plan and want to save even more. (Keep in mind: If you already have a 401(k), you may or may not be eligible for tax-advantaged contributions to an IRA in any given tax year, depending on your income.)

There are different types of IRAs, but two of the most common are Roth and traditional IRAs. Each has the same annual contribution limits, which is $7,500 in 2026 for those under age 50.

Both traditional IRAs and Roth IRAs are tax-advantaged accounts, but they work differently. With a traditional IRA, you make pre-tax contributions. You can deduct the contributions in the year you make them, as long as you meet certain conditions. When you withdraw your savings from a traditional IRA in retirement, you pay taxes on the withdrawals.

With a Roth IRA, your contributions are made with after-tax dollars. You can’t deduct your contributions, but your potential earnings grow tax-free in the account, and your qualified withdrawals in retirement are tax-free. Roth IRAs do have income limits ($153,000 for those who are single in 2026 and $242,000 for those who are filing jointly) to make a full contribution.

There are specific withdrawal rules for traditional and Roth IRAs. For example, withdrawals from a traditional IRA before age 59 ½ typically incur income taxes and a 10% penalty. Withdrawals of Roth IRA contributions can be made anytime and they are tax- and penalty- free. However, any earnings withdrawn before age 59 ½ may be subject to income taxes and a 10% penalty.

Brokerage Accounts for Retirement Savings

There is no single best way to save for retirement; sometimes an approach that includes different kinds of retirement savings accounts may be worth exploring.

For example, millennials who have an IRA or a 401(k) may also want to consider opening an investment account, such as a taxable brokerage account, to invest in the market.

Once an individual opens a brokerage account and deposits money into it, they can start investing. They might choose to buy stocks, mutual funds, ETFs, or other securities, for instance. There are a wide range of investment options with a brokerage account and no contribution limits.

Just be aware that because brokerage accounts are taxable, selling investments can result in gains or losses, which generally have tax implications. Interest and dividends earned may also be taxable. You can consult with a tax professional to learn more.

Key Steps to Start Your Retirement Plan

One of the most important moves you can make to save for retirement is getting started. Here are some ways to put your millennial retirement savings plan into action to help secure your financial future.

Create a Budget and Track Your Spending

Making a budget, and then sticking to it, can help you reduce expenses and free up money you can put toward retirement.

To make a monthly budget, gather all your bills (including mortgage or rent, utilities, credit card bills, student loan payments, and car payments) so that you can add up your typical monthly expenses. Next, calculate your average monthly income. Besides your regular job, include any side gigs you may have.

Once you have those figures and you can clearly see what you’re paying out and taking in, you can create a monthly budget. Look for any expenses you may be able to eliminate or reduce, such as streaming services, gym memberships, or eating out at restaurants.

Start Saving Early and Consistently

The sooner you start saving for retirement, the more time your money potentially has to grow. One reason for this is the power of compounding returns. This refers to the process where investment earnings are reinvested to generate further earnings. This creates a snowball effect, where returns are earned not only on the initial investment (principal) but also on the accumulated returns from previous periods, potentially leading to exponential growth over time.

This is one key reason people are encouraged to invest as young adults. The longer money is invested, the more it may compound.

Understand Your Risk Tolerance

Investing money inherently involves risk. That means you’ll need to determine what your risk tolerance is.

Risk tolerance is the amount of risk you are willing to assume to achieve your financial goals. Typically there are three main categories of risk tolerance: conservative, moderate, and aggressive.

To help figure out what your tolerance for risk is, consider:

•   How much money you have to invest and whether you expect your salary to increase over the coming years. If you do expect your income to go up, your risk tolerance may be higher since it might be easier to recover from any losses.

•   What your expenses are now and what they’re likely to be in retirement. If you are looking at higher expenses in retirement, your risk tolerance might be lower, and vice versa.

•   How you feel about the stock market. If volatility makes you nervous, you may want to assume lower investment risk, for example.

•   When you want to retire. If you hope to retire early, you may want to be more conservative with your investment strategy.

Diversify Your Investments

When investing, it’s generally considered wise for an individual not to put all their investments into one basket. If they do, it could make them vulnerable to losses. For instance, if they invest in stocks that are all in the same area or sector — energy, say — and a negative event causes those stocks to drop, the value of their entire portfolio could plummet as a result.

Diversifying a portfolio means investing in different kinds of asset classes, such as stocks, bonds, mutual funds, and money market funds, for instance. From there, an investor could invest in different types of assets in each asset class. So they might choose medium- and large-cap stocks and a variety of different kinds of bonds, for example. That way, if one sector or type or investment drops in value, the other investments they have may hold steady or even go up to help balance things out.

While diversification is not a way to avoid risk, it does spread your money out across a range of assets in a way that may be beneficial.

Consider Professional Financial Planning

If you don’t feel confident about investing for retirement on your own, or you need help making a financial plan for your future, you may want to consider a financial advisor who could help you map out your saving and investing strategy. Talk with friends or family members whose opinion you trust to get a recommendation. Then meet with the advisor to make sure you’ll feel comfortable with them. You may want to speak with a few financial advisors to determine which one is right for your needs.

Ask upfront how the advisor is compensated. Some advisors charge a flat fee or an hourly rate, and some earn commissions or combinations of fees and commissions.

Regularly Review and Adjust Your Plan

It’s generally a good idea to periodically review and, if needed, adjust your retirement savings plan. Life circumstances can change — such as getting a new job, marriage, having children, or facing health issues — which can impact your financial needs and goals.

Market conditions also fluctuate, affecting the performance of investments. Rebalancing a portfolio as needed may help manage risk and keep your strategy aligned with your retirement timeline. Changes in tax laws or retirement account rules (like contribution limits) could also impact your plan. Staying informed and adjusting accordingly may help you avoid penalties and make the most of your benefits.

Regular reviews also allow you to monitor your overall progress and make POTENTIAL changes if you are falling behind, such as increasing contributions or changing the mix of investments in your portfolio.

Common Retirement Planning Mistakes Millennials Should Avoid

As you work on your retirement plan, watch out for these five common blunders that might set back your savings strategy.

Delaying Saving for Retirement

Waiting too long to save for retirement is one of the biggest mistakes people make. In a 2026 survey by the TIAA Institute, 76% of retirees said they regret not starting to save for retirement earlier in their lives, and 71% said they wished they had saved more for retirement.

Starting the savings process early is critical because, as noted above, the power of compounding returns may help you build wealth over time. Generally, the sooner millennials begin saving and investing money for the future, the better.

Not Taking Advantage of Employer Matching

The employer match on a workplace retirement plan like a 401(k) is essentially bonus money. If you’re not taking advantage of it, you’re missing out.

If possible, contribute at least enough to your 401(k) to get the match. To get an idea of how employer matching could benefit you, consider this example:

Let’s say your annual salary is $60,000 and your employer offers $0.50 per dollar on the first 6% of your pay (a common formula). When you contribute $3,600 (6% of your salary), your employer kicks in $1,800, for a total of $5,400.

Withdrawing From Retirement Accounts Early

Taking early withdrawals from retirement accounts like IRAs and 401(k)s before age 59 ½ typically means incurring taxes and penalties. Not only does this cost you money, but you’re also losing out on the potential compound growth you might have had if the money had remained in your account. That could significantly set back your retirement savings.

While there are some specific situations where you can tap a retirement account early without penalties (such as financial hardship or buying your first home), it’s best not to withdraw money early from a retirement account if possible.

Being Too Conservative or Too Aggressive With Investments

As mentioned earlier, an investor’s tolerance for risk typically impacts how they approach investing. Going too far in one direction or the other, however, could end up costing them money. For example, millennials who take an approach that’s too risky — such as a portfolio heavily weighted with stocks — may end up taking big losses if the market dips.

Conversely, millennials who use a more conservative investing approach may be leaving money on the table by having too many lower-risk assets in their portfolio. Remember, the younger an individual is, the more time they have to recover from market downturns.

Ignoring Inflation

Many people calculate how much they’ll need in retirement based on today’s prices. But as the cost of goods and services rises due to inflation, your retirement income won’t stretch as far as you may have originally planned.

For example, if you need $50,000 to cover your expenses in the first year of retirement, a consistent inflation rate of 2.5% could mean you’d need to spend closer to $80,000 20 years later to maintain the same standard of living.

To make sure you’re setting aside a sufficient nest egg, it’s important to adjust your goals and investment strategies to keep up with inflation.

The Takeaway

Millennials face a number of financial challenges, including student loan debt, stagnating wages, and a higher cost of living. While retirement may feel like less of a priority at this stage of life, it’s important for millennials to start saving now so that their money has a chance to grow over time. Options for retirement saving and investing for millennials might include participating in an employer’s 401(k), opening an IRA, or opening a brokerage account.

The sooner millennials begin building their nest egg, generally the better their chances are of achieving a secure retirement.

Prepare for your retirement with an individual retirement account (IRA). It’s easy to get started when you open a traditional or Roth IRA with SoFi. Whether you prefer a hands-on self-directed IRA through SoFi Securities or an automated robo IRA with SoFi Wealth, you can build a portfolio to help support your long-term goals while gaining access to tax-advantaged savings strategies.

Help build your nest egg with a SoFi IRA.

FAQ

How much should I be saving for retirement as a millennial?

How much you should be saving for retirement as a millennial depends on your specific situation, but there are popular rules of thumb that may give you some guidance. For instance, the 80% rule says you should have enough savings to replace roughly 80% of your pre-retirement income in retirement. Another guideline offers rough savings targets based on your age: By age 30, you should have saved 1x your salary; by 35, you should have saved 2x your salary; by 40, you should have saved 3x your salary; by 45, you should have saved 5x your salary; by 50, 6x your salary; and by 60, 8x your salary.

What’s the difference between a 401(k) and an IRA?

A 401(k) and an IRA are both retirement savings accounts. The difference between them is that a 401(k) is an employer-sponsored retirement plan that you can participate in at work if your employer offers it, and an IRA is an individual retirement account that you open and manage on your own.

Is it too late to start saving for retirement in my 30s or 40s?

It’s never too late to start saving for retirement. It’s true that the sooner you start, the better, since your money will potentially have more time to grow through compounding returns. But time is still on your side: If you’re 35 and you start saving now, that still gives you 30 years to save up for the traditional retirement age of 65. If you’re 40, you have 25 years to reach your retirement savings goals.

What are some good investment options for millennials just starting out?

Millennials who are just starting out can participate in their workplace 401(k) plan if their employer offers one or they could open an individual retirement account (IRA) that they manage themselves to save for their retirement. With either type of retirement account, an individual can typically choose from such assets as mutual funds, index funds, exchange-traded funds (ETFs), and stocks.

Should I factor in Social Security for my retirement?

Yes, you should factor in Social Security when planning for retirement. To find out what your Social Security benefit in retirement is expected to be, you can create a Social Security account at www.ssa.gov/myaccount. Then, you can get an estimate of what your future retirement benefits might be by using the Social Security Administration’s online benefits calculator.


Photo credit: iStock/Fly View Productions


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.
Investment Risk: Diversification can help reduce some investment risk, but cannot guarantee profit nor fully protect in a down market.
Calculator: This calculator is for educational purposes only and based on mathematical principles that do not reflect actual performance of any particular investment, portfolio, or index. Results are not gaurenteed and should not be considered investment, tax, or legal advice. Investing involves risks and results vary based on a number of factors including market conditions and individual circumstances. Past performance is not indicative of future results.
Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOIN-Q426-061

Read more
Someone looking at financial charts on a tablet.

How Do Employee Stock Options Work?

Employee stock options (ESOs) may be included in an employee’s compensation package, as a way of giving an employee the opportunity to buy stock in the company at a certain price — and as an incentive to stay with the company for a period of time.

Employee stock options give employees the right to buy company stock at an established grant price once certain terms are met. But there’s no obligation to do so.

Exercising stock options means choosing to purchase the stock at the grant price, after a predetermined waiting period. If an employee doesn’t purchase the stock, the option will eventually expire.

Employee stock options may also give employees a sense of ownership (and, to a degree, actual ownership) in the company they work for. That can have benefits and drawbacks. But if you’re working in an industry in which employee stock options are common, it’s important to know how they work, the different types, and the tax implications.

Key Points

•   Employee stock options (ESOs) may be offered as part of an employee’s compensation package.

•   Employee stock options give employees the right to purchase a certain number of company shares for a certain price, by a certain date.

•   Stock options are typically offered on a vesting schedule, with a percentage of options available by a certain date or series of dates.

•   If the market price of the shares is higher on the exercise date, the employee may be able to realize a profit. But there are no guarantees, and the share price could drop below the exercise price.

•   Incentive stock options typically receive a more favorable tax treatment than non-qualified stock options.

What Are Employee Stock Options?

Employee stock options give an employee the chance to purchase a set number of shares in the company at a set price — often called the exercise price — over a set amount of time.

Typically, the exercise price is a way to lock in a lower price for the shares, although there are no guarantees.

This potentially gives an employee the chance to exercise their ESOs at a point when the exercise price may be lower than the market price — with the potential to make a profit on the shares.

Sometimes, an employer may offer both ESOs and restricted stock units (RSUs). RSUs are different from ESOs in that they are generally a promise of stock at a later date.

Employee Stock Option Basics

When discussing stock options, there are some essential terms to know in order to understand how these options work. (For investors who are familiar with options trading, some of these terms may sound similar. But options trading, which involves derivatives contracts, doesn’t have any bearing on employee stock options.)

•   Exercise price/grant price/strike price: This is the given set price at which employees may purchase the stock options.

•   Market price: This is the current price of the stock on the market (which may be lower or higher than the exercise price). Typically an employee would only choose to exercise and purchase the options if the market price is higher than the grant price.

•   Issue date: This is the date on which the employee is given the stock options.

•   Vesting date: This is the date after which an employee can exercise their stock options per the original terms or vesting schedule.

•   Exercise date: This is the date an employee actually chooses to exercise their employee stock options.

•   Expiration date: This is the date on which the employee’s ability to exercise their stock options expires.

How Do Employee Stock Option Plans Work?

When you’re given employee stock options, that means you have the option to buy stock in the company at the grant price. If you don’t use the options to purchase the stock within the specified period, they expire.

ESO Vesting Periods

Typically, employee stock options follow a vesting schedule, which is basically a waiting period after which you can exercise them. This means an employee must stay at the company a certain amount of time before they can exercise their stock options.

The stock options they’re offered may be fully vested on a certain date, or just partially vested over multiple years, meaning some of the options can be exercised at one date and others at a later date.

ESO Example

For example, imagine an employee was issued employee stock options on February 1 of 2026, with the option of buying 100 shares of the company at $10/share. They can exercise their options starting on February 1, 2027 (the vesting date) for 10 years, until February 1, 2037 (the expiration date).

If they chose not to exercise these options by February 1, 2037, the options would expire and the employee would no longer have the option to buy the stock at $10/share.

Now, let’s say the market price of shares in the company goes up to $20 at some point after they’ve vested in 2027, and the employee decides to exercise their options.

They would buy 100 shares at $10/share for $1,000 total — while the market value of those shares is actually $2,000. In this scenario, the vesting period allowed the stock to grow and deliver a profit. But the reverse could also occur: The share price could drop to $8, in which case the employee wouldn’t exercise their options because they’d lose money. Instead, they might choose to wait and see if the share price rebounds.

Exercising Employee Stock Options

You don’t need to exercise your employee stock options unless it makes sense for you. You’re under no obligation to do so. Whether you choose to do so or not will likely depend on your financial situation and financial goals, the forecasted value of the company, and what you expect to do with the shares after you purchase them.

If you plan to exercise your ESOs, there are a few different ways to do so. The shares you get are effectively the same as the shares available on online investing platforms and brokerages, but some companies have specifications about when the shares can be sold, typically because they don’t want employees to exercise their options and then sell off all their stock in the company immediately.

Buy and Hold

Once you own shares in the company, you may choose to hold onto them — effectively, a buy-and-hold strategy. To continue the example above, you could buy the 100 shares with $1,000 cash and you would then own that amount of stock in the company — until you decide to sell your shares (if you do).

Cashless Exercise

Another way to exercise your ESOs is with a cashless exercise, which means you sell off enough of the shares at the market price to pay for the total purchase.

For example, you would sell off 50 of your purchased shares at $20/share to cover the $1,000 that exercising the options cost you. You would be left with 50 shares. Most companies offering brokerage accounts may do this buying and selling simultaneously.

Stock Swap

A third way to exercise options is if you already own shares. A stock swap allows you to swap in existing shares of the company at the market price of those shares and trade for shares at the exercise price.

For example, you might trade in 50 shares that you already own, worth $1,000 at the market price, and then purchase 100 shares at $10/share.

When the market price is higher than the exercise price — often referred to as options being “in the money” — you may be able to gain value for those shares because they’re worth more than you pay for them.

Why Do Companies Offer Stock Options?

The idea behind employee stock options is generally that if employees are financially invested in the success of the company, then they’re more likely to be emotionally invested in its success as well, and this may increase employee productivity and loyalty.

From an employee’s point of view, stock options may offer a way to see some financial benefit of their own hard work. In theory, if the company is successful, then the market stock price could rise and the stock options could be worth more.

The financial prospects of the company typically influence whether people want to buy or sell shares in that company, but there are a number of factors that can determine stock price, including investor behavior, company news, world events, and primary and secondary markets.

Tax Implications of Employee Stock Options

There are two main kinds of employee stock options: qualified and non-qualified, each of which has different tax implications. These are also known as incentive stock options (ISOs) and non-qualified stock options (NSOs or NQSOs).

Incentive Stock Options (ISO)

When you buy shares in a company below the market price, you could be taxed on the difference between what you pay and what the market price is. ISOs are “qualified” for preferential tax treatment, meaning no taxes are due at the time you exercise your options — unless you’re subject to an alternative minimum tax.

Instead, taxes are due at the time you sell the stock and make a profit. If you sell the stock more than one year after you exercise the option and two years after they were granted, then you will likely only be subject to capital gains tax.

If you sell the shares prior to meeting that holding period, you will likely pay additional taxes on the difference between the price you paid and the market price as if your company had just given you that amount outright. For this reason, it may often be financially beneficial to hold onto ESO shares for at least one year after exercising, and two years after your exercise date.

Non-qualified Stock Options (NSOs or NQSOs)

NSOs do not qualify for preferential tax treatment. That means that exercising stock options subjects them to ordinary income tax on the difference between the exercise price and the market price at the time you purchase the stock. Unlike ISOs, NSOs will always be taxed as ordinary income.

Taxes may be specific to your individual circumstances and vary based on how the company has set up its employee stock option program, so it may be a good idea to consult a financial advisor or tax professional for specifics.

Should You Exercise Employee Stock Options?

While it’s impossible to know if the market price of the shares will go up or down in the future, there are a number of things to consider when deciding if you should exercise options:

•   The type of option — ISO or NSO — and related tax implications

•   The financial prospects of the company

•   Your own investment portfolio, and how these company shares might fit into your overall investment strategy

You also might want to consider how many shares are being made available, to whom, and on what timeline — especially when weighing what stock options are worth to you as part of a job offer. For example, if you’re offered shares worth 1% of the company, but then the next year more shares are made available, you could find your ownership diluted and the stock would then be worth less.

The Takeaway

Employee stock options (ESOs) can be an incentive that companies may offer their employees. They present the opportunity to invest in the company directly, and possibly profit from doing so. There are certain rules around ESOs, including timing of exercising the stock options, as well as different tax implications depending on the type of ESO a company offers its employees.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What happens to my stock options if I leave the company?

It depends on whether the stock options are vested or unvested. Employee stock options typically have a vesting schedule, or period of time, after which you can exercise them. If the options are not vested when you leave the company, you forfeit the stock options. If the options are partially or fully vested, your employer will typically give you a specific window of time — typically between 30 to 90 days — in which to exercise them. After that window, you typically lose the options. If you’ve already bought vested options, they are yours to keep when you leave the company.

What is the difference between ISOs and NSOs?

With ISOs, or incentive stock options, you are not taxed when you exercise your options. Instead, you pay taxes when you sell the options and make a profit. If you wait at least two years after the grant date, and at least one year after exercising the ISOs before selling them, you will typically be subject to the lower capital gains tax rate instead of the ordinary income tax rate. With NSOs, or non-qualified stock options, you are taxed at your ordinary income tax rate as soon as you exercise the options.

Do I have to exercise my stock options right away?

No. You can choose not to exercise your stock options if you wish. However, there is typically an expiration date — often, about 10 years — by which time an employee must exercise their options. After that date, you generally lose the opportunity to exercise them.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.

SOIN-Q426-053

Read more
Someone using a phone and laptop to research how to choose the right ETF.

Tips on How to Choose The Right ETF

Exchange-traded funds (ETFs) are investment funds that trade on stock exchanges throughout the day. They typically hold a basket of assets, such as stocks or bonds, and may track an underlying index or follow another investment strategy. Since the first ETFs launched in the early 1990s, the industry has grown substantially, giving investors thousands of funds to choose from.

But not every ETF is a good fit for every investor or portfolio. ETFs can vary widely in their holdings, investment objectives, risk levels, and costs. Understanding how to evaluate these differences can help investors identify funds that align with their financial goals and investment strategies.

Key Points

•   Choosing the right ETF generally involves evaluating its asset class, investment focus, strategy, costs, and risks.

•   Investors can target broad markets or narrow their focus to specific sectors, company sizes, dividend styles, or themes.

•   Understanding an ETF’s management approach can help clarify its expected returns, overall complexity, and risk factors.

•   Total ownership costs include ongoing expense ratios as well as trading expenses like bid-ask spreads.

•   Reviewing a fund’s holdings, prospectus, and fact sheet can help ensure it aligns with your overall portfolio strategy.

How Do I Pick an ETF?

There’s no single right way to choose an exchange-traded fund (ETF), but following a process can help investors narrow their options and evaluate their choices.

Step 1: Identify the Asset Class

Investors might start by deciding which asset class they want exposure to. The main asset classes include stocks, bonds, cash and cash equivalents, and commodities. Some ETFs also provide exposure to currencies or other types of assets.

Each asset class has different characteristics, including its potential risks and returns.

•   Stocks: Stocks represent ownership in companies. Stock ETFs can offer exposure to individual companies, industries, or broad markets. Stock prices can fluctuate significantly, and investors may lose money.

•   Bonds: Bonds are debt securities issued by governments, corporations, and other entities. Bond ETFs can provide exposure to different types of debt, which may offer income but also carry risks such as interest rate risk and credit risk.

•   Commodities: Commodity ETFs can provide exposure to assets such as gold, oil, or agricultural products. These investments can be volatile and may use futures contracts rather than directly holding the underlying commodity.

•   Cash and cash equivalents: Some ETFs invest in short-term, relatively liquid securities, such as Treasury bills. These funds may have different risk and return characteristics from stock or bond ETFs.

An asset class’s potential return depends in part on the risks involved, but higher risk doesn’t guarantee higher returns. It’s wise for investors to consider their time horizon, financial goals, and ability to tolerate losses when choosing an ETF.

Also keep in mind that choosing one asset class doesn’t preclude investing in others. In fact, holding investments across different asset classes is one way investors may diversify a portfolio. This approach is known as asset allocation.

Step 2: Narrow the Investment Focus

Once investors have chosen an asset class, they can narrow their options by deciding what type of exposure they want within that market.

For stock ETFs, this may mean choosing between funds that track a broad market and those focused on a particular industry, company size, or investment characteristic. For example:

•   Sector ETFs: Focus on a specific industry, such as technology, financial services, or health care.

•   Dividend ETFs : Hold stocks selected for their dividend payments or dividend-related characteristics.

•   Growth or value ETFs: Focus on stocks with characteristics associated with growth potential or relatively low valuations.

•   Small-cap or large-cap ETFs: Focus on companies of different sizes, based on their market capitalization.

Bond ETFs can also vary by investment focus. Investors may compare funds that hold government or corporate bonds, domestic or international debt, or investment-grade or high-yield bonds. These categories can have different risk and return characteristics.

Some ETFs take a narrower approach by focusing on a particular theme, such as artificial intelligence, robotics, or electric vehicles. These thematic ETFs may provide exposure to a specific trend, but their concentrated focus can also increase risk. Investors can review a fund’s holdings and investment objective to understand what exposure it actually provides.

Step 3: Understand the ETF’s Investment Strategy

ETFs can use different strategies to select and manage their holdings. Understanding how a fund operates can help investors evaluate its objectives, costs, and potential risks.

Some common ETF strategies include:

•   Index ETFs: These funds seek to track a market index, such as the S&P 500, and generally follow a passive investment approach.

•   Actively managed ETFs: Rather than tracking an index, these funds rely on portfolio managers to select and manage investments based on the fund’s objectives.

•   Factor ETFs: Also known as smart-beta ETFs, these funds use rules-based approaches to select or weight investments based on characteristics such as value, momentum, or volatility.

•   Leveraged and inverse ETFs: Leveraged ETFs seek to deliver a multiple of an underlying index’s daily return, while inverse ETFs seek to deliver the opposite of its daily performance. These funds typically use derivatives and can carry significant risks, particularly when held for longer than a single trading day.

•   Currency-hedged ETFs: These funds use strategies designed to reduce the impact of currency fluctuations on returns from international investments.

These strategies can affect an ETF’s performance, costs, and risk level. It’s a good idea to review a fund’s investment objective and prospectus to understand how it works before choosing it.

Step 4: Compare ETF Costs

One reason ETFs have become popular is that many offer relatively low costs, particularly those that track broad market indexes. However, ETF costs can vary considerably, and the expense ratio is only one factor to consider.

An ETF’s expense ratio represents its annual operating expenses as a percentage of its assets. These expenses are generally reflected in the fund’s net asset value rather than billed directly to investors. For example, an ETF with an expense ratio of 0.45% would have annual operating expenses equivalent to $4.50 for every $1,000 invested, assuming the investment amount remained unchanged.

Expense ratios can vary depending on the fund’s investment strategy, complexity, and management approach. Many broad-market index ETFs have relatively low expense ratios, while some actively managed or specialized funds charge more. When comparing ETFs with similar objectives, the expense ratio can help investors understand how much they may pay for the fund’s management and operation.

There may also be costs involved in buying or selling ETF shares. These include the bid-ask spread, which is the difference between the highest price a buyer is willing to pay and the lowest price a seller is willing to accept. A wider spread can increase the cost of trading. Investors may also pay brokerage commissions, depending on their brokerage firm and account.

Considering both ongoing fund expenses and trading costs can provide a more complete picture of an ETF’s cost.

Step 5: Evaluate Performance, Tracking, and Liquidity

After narrowing down ETF options, investors may want to examine additional information to better understand how a fund operates and how it has performed.

Historical Performance

Historical performance can help investors understand how an ETF has behaved under different market conditions. However, past performance doesn’t guarantee future results. When comparing funds, it’s wise to look at performance over multiple periods and consider whether the funds have similar investment objectives and levels of risk.

It’s also important to distinguish between price returns and total returns. Total returns generally account for both changes in an investment’s price and distributions, such as dividends or interest.

Tracking Difference and Tracking Error

For index ETFs, tracking is another important consideration. Tracking difference measures how much an ETF’s return differs from the return of its underlying index over a particular period. Tracking error generally measures how much the ETF’s returns fluctuate relative to the index’s returns over time.

An ETF may not perfectly match its benchmark because of expenses, trading costs, cash holdings, sampling techniques, or the way it handles dividends and other distributions. These differences can be particularly important when comparing funds that track the same or similar indexes.

Liquidity

Liquidity refers to how easily an investor can buy or sell ETF shares without significantly affecting the price. A fund’s assets under management (AUM), trading volume, and bid-ask spread can all provide useful information about its trading characteristics.

A larger AUM may indicate that a fund has attracted more investor assets, but fund size alone doesn’t determine liquidity. The liquidity of the underlying securities and the ETF’s trading conditions can also matter.

Investors comparing similar ETFs may want to examine their typical bid-ask spreads and trading volume, as well as the liquidity of the assets they hold.

How to Find an ETF’s Holdings, Prospectus, and Fact Sheet

Researching an ETF’s holdings and official documents can help investors understand what they’re buying and the risks involved.

ETF Holdings

ETF providers typically publish information about a fund’s holdings on their websites. Many ETFs disclose their portfolio holdings daily, although disclosure practices can vary by fund structure and strategy. Reviewing holdings can help investors determine which securities a fund owns, how concentrated its portfolio is, and whether it overlaps with other investments they hold.

ETF Prospectus

An ETF’s prospectus provides detailed information about the fund, including:

•   Its investment objective and strategy

•   The types of securities it holds or may hold

•   Principal risks

•   Fees and expenses

•   Information about the fund’s management and operations

Investors can generally find a fund’s prospectus on the ETF provider’s website or through the SEC’s EDGAR database. Reading the prospectus can help investors understand the fund’s intended strategy and the risks associated with it.

ETF Fact Sheet

An ETF fact sheet provides a shorter overview of the fund. It may include information such as:

•   Investment objective and benchmark

•   Historical performance

•   Expense ratio

•   Top holdings

•   Sector or asset allocation

•   Other portfolio characteristics

ETF providers typically publish fact sheets periodically, often quarterly. Fact sheets can be useful for comparing funds, but investors will want to consult the prospectus and other official fund materials for more detailed information.

The Takeaway

Choosing an ETF from the thousands available can seem daunting, but a step-by-step approach can help simplify the process. Important considerations include the asset class, investment focus, and strategy of the fund, as well as its costs, historical performance, tracking characteristics, and liquidity.

An ETF’s prospectus and fact sheet can provide useful information about its investment objectives, holdings, expenses, and risks.

While an individual ETF may provide exposure to a range of securities, that doesn’t necessarily mean it offers broad diversification. Some investors use multiple ETFs to build a portfolio with exposure to different asset classes and markets. Understanding what each fund holds and how it operates can help investors evaluate how it may fit within their overall portfolio.

Ready to invest in your goals? It’s easy to get started when you open an investment account with SoFi Invest®. You can trade stocks, ETFs, or options through self-directed investing with SoFi Securities, or simply automate your investments with a robo advisor from SoFi Wealth. You'll gain access to alternative investments and upcoming IPOs, and can plan for retirement with a tax-advantaged IRA. With SoFi, you can manage all your investments, all in one place.

Take a step toward reaching your financial goals with SoFi Invest.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

How Many ETFs Should I Own?

There’s no set number of ETFs an investor should own. Some ETFs provide broad exposure to hundreds or thousands of securities, while others focus on specific industries, asset classes, or investment strategies. An investor may be able to build a diversified portfolio with just a few ETFs, depending on their objectives and the funds’ holdings. Owning more ETFs doesn’t necessarily mean having greater diversification, particularly if the funds hold many of the same securities.

Are ETFs a Good Choice for Beginners?

ETFs can be relatively accessible for beginners because they offer exposure to a range of securities through a single fund and trade on stock exchanges like individual stocks. However, ETFs vary in their investment strategies, costs, and risk levels. Beginners will want to understand a fund’s holdings, investment objective, and potential risks before buying shares.

What Is a Good Expense Ratio for an ETF?

A good expense ratio depends on the type of ETF and its investment strategy. Broad-market index ETFs often have relatively low expense ratios, while specialized and actively managed funds may charge more. When comparing ETFs with similar objectives, investors can compare their expense ratios along with other costs, such as bid-ask spreads and brokerage commissions.

Can You Lose Money Investing in ETFs?

Yes. ETFs are subject to market risk, and their share prices can decline if the securities they hold lose value. Some ETFs, such as those focused on narrow market sectors or those using leveraged strategies, may carry additional risks. Even diversified ETFs can lose value during market downturns. An ETF’s diversification and investment strategy don’t guarantee against losses.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOIN-Q426-085

Read more
Someone using a phone to look up the difference between a check routing number and account number.

Check Routing vs Account Number: Differences Explained

The difference between a check routing and account number is that the routing number identifies the bank, while the account number reflects the specific checking account you hold.

If you’re looking for your bank routing and account numbers, they are likely easier to find than you may think: You can locate them on your checks or by logging into your financial institution’s app, for instance.That said, you probably don’t want to broadcast these digits to too many people, as they are sensitive financial details, used for everything from direct deposit to money transfers. Learn more about these digits and how to use and protect them.

Key Points

•   A routing number is a nine-digit code that identifies a bank or credit union.

•   An account number is a unique identifier for your specific bank account.

•   Routing numbers are used for various financial transactions like direct deposit, bill pay, and wire transfers.

•   Account numbers are private and should be kept secure to prevent fraud.

•   You can find your routing and account numbers on checks, through online banking, in-app, or by contacting your bank.

🛈 If you’re looking for the SoFi routing number, you can find it here: SoFi routing number.

What Is a Routing Number?

A routing number is a sequence of nine digits that identifies a bank or credit union, and each banking institution has a unique number. Here are some facts about routing numbers and how they work:

•   A routing number is also sometimes referred to as an ABA number, in reference to the American Bankers Association, which assigns them. Routing numbers are only issued to federal or state-chartered financial institutions that are eligible to maintain an account at a Federal Reserve Bank.

•   Your bank’s routing number and ACH routing number may or may not be the same digits. Check with your bank to be sure.

•   The routing number required for making a wire transfer may often differ from the routing number that is printed on your checks. That number can be found online or by contacting your bank.

•   A small bank may only have one routing number, while a larger financial institution may have several (they typically vary by state). An online bank, which operates without physical branches, will typically have one routing number.

Purpose of a Routing Number in Banking

The purpose of a routing number is to identify the financial institution that is responsible for the payment and ensure that funds are sent to the right place in a financial transaction.

Routing numbers are generally required when reordering checks, paying bills, setting up direct deposit, or making tax payments. Making sure you have the right digits can help ensure smooth transactions.

What Is an Account Number?

While the routing number identifies the financial institution where your account is held, the bank account number represents your specific account. While anyone can find your bank’s routing number, your account number is private; that’s a key difference in routing vs. account numbers. Here are some other points about account numbers to consider:

•   Typically between eight and 12 digits, your account number acts as a road map of sorts for your bank, letting them know where to deposit or withdraw money, whether that’s a checking account or a savings account.

•   If you have two different accounts at the same financial institution, you will have two different account numbers. The routing number for these accounts, however, will be the same.

•   Because your account number can unlock access to the funds in your checking or savings account, it’s critical that you keep it safe.

Role of an Account Number in Transactions

Whether you are receiving a paycheck, making online purchases, or setting up autopay, your account number plays a key role. While routing numbers identify your bank, account numbers ensure that money is correctly credited to or debited from the right bank account.

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

When You Need a Routing Number vs Account Number

There are many times when you may need a routing number vs. account number for everyday financial transactions. These may include:

•   Setting up direct deposit of your paycheck

•   Setting up autopay

•   Setting up direct deposit of Social Security or other government benefits

•   Paying a bill by online banking

•   Setting up autopay

•   Check processing

•   Sending or receiving a wire transfer

•   Sending up a peer-to-peer payment app or service

•   Transferring funds between accounts at different banks

•   Making payments from your bank account by phone

•   Ordering new checks

•   Linking a budgeting app to your bank account

Recommended: 10 Benefits of Direct Deposit

Finding Your Check Routing and Account Number

If you need to find your routing and account numbers, you likely have several options, from looking at a physical check to logging in to your banking app:

How to Find the Routing vs Account Number on a Check

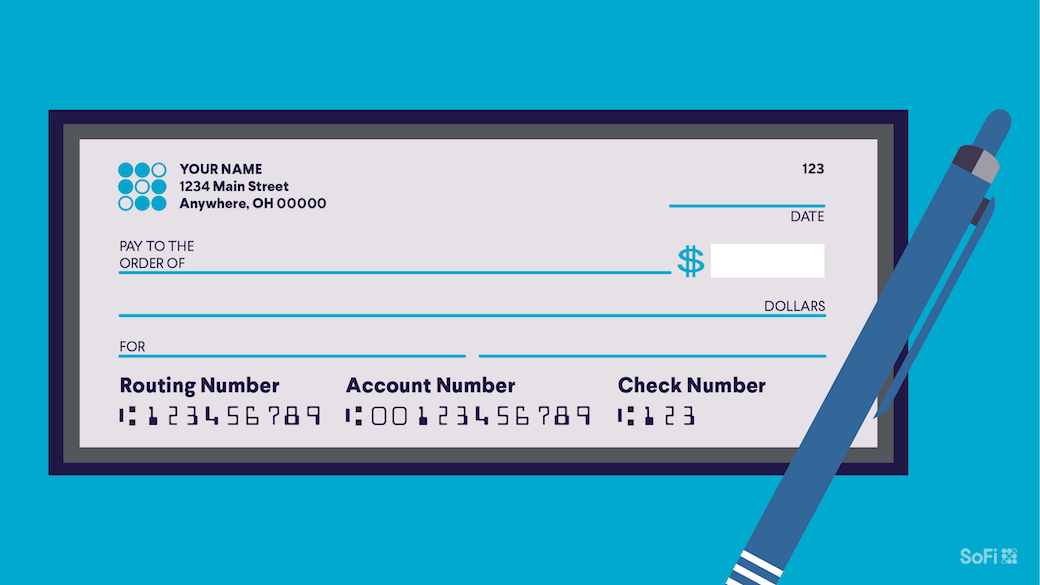
You can find your routing vs. account number on a check, printed on the bottom.

You’ll see three groups of numbers (often separated by spaces and/or symbols). Typically, reading left to right, the first number (nine digits) is the routing number; the next group of numbers (usually eight to 12 digits) is the account number; the third is the actual check number.

check image with numbers

Contacting Your Bank

If you need to find your routing number and account numbers and don’t have access to a check, you can call your bank (or stop into a branch) and ask a customer service representative to provide you with the numbers. Since your account number is private information, you will likely have to provide identifying details to verify your right to gain access to this number.

Note: If all you need is the routing number, you can easily find it on your bank’s website.

Accessing Your Online Account

If you log in to your bank account online or in-app, you should be able to get your banking details. Your account number may be encrypted (meaning you can only see the last four digits). If that’s the case, you can typically get the full number by downloading a recent bank statement. Or there may be a prompt you can click in order to see the full number.

Recommended: Checking Account vs Debit Card: What’s the Difference?

Protecting Your Routing and Account Numbers

Although anyone can locate your bank’s routing number, your account number is not public information. Just as you are probably mindful about who sees your Social Security number, the same goes for your bank account number. You want to try to make sure that someone doesn’t use your bank account and routing number without authorization, which can be a form of bank fraud.

Tips for Keeping Your Banking Information Secure

Here are some ways to help keep sensitive banking information safe:

•   Avoid sharing your banking details unless necessary. To protect yourself from potential bank fraud, you generally don’t want to share your account number with any person or business unless you absolutely need to. Also wise: not sharing pictures of checks you’ve written on social media, even if it is for the first payment on your dream car.

•   Store physical checks in a secure place. Since checks contain both your routing and account number, it’s a good idea to keep your checkbook tucked away in a safe place, not sitting out in the open. Also, if you void a check or are getting rid of old checks and paper statements, it can be wise to shred these documents before throwing them away.

•   Enable multi-factor authentication (MFA) for online banking. Two- or three-factor authentication requires additional information beyond a password — such as a code sent to your mobile phone or a fingerprint scan — for account access. You’ll typically find this option inside the account settings.

•   Regularly monitor your accounts. It’s a good idea to review your bank statements monthly and check your online banking once a week. This can help you to pick up on any suspicious transactions and nip any potential issues in the bud.

Recommended: How to Sign a Check Over to Someone Else

What to Do if Your Information Is Compromised

Here are smart steps to take if you suspect fraud or unauthorized access to your bank account:

•   Contact your bank immediately. Call customer service and inform the representative of any unauthorized banking transactions as soon as you notice them.

•   Change your login credentials: It’s a good idea to choose a new (unique) password for your bank account. Also consider setting up multi-factor authentication if you haven’t already.

•   Review your recent transactions: Comb through recent activity on your bank account and make a list of any transactions you don’t recognize, noting the date and details. You’ll typically need this information to file a dispute with your bank.

•   Consider placing a fraud alert on your credit report: You can contact any one of the three credit bureaus — Equifax®, Experian®, and TransUnion® — to place a fraud alert on all three of your credit reports. A fraud alert is free and notifies creditors to take extra steps to verify your identity before extending credit.

The Takeaway

A check routing number indicates the bank where your account is held, while an account number identifies your specific account at that bank. Routing and account numbers work together to identify your account and ensure that your money gets transferred from the right place or that you receive funds intended for you. Knowing the difference between these numbers, where to locate them, and how to protect them can be vital to managing your finances securely.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Do you need both a routing and account number for a wire transfer?

Typically, yes. Transactions like wire transfers require both a routing and account number. The routing number identifies your bank, while the account number specifies your individual account. Together, they ensure that funds are correctly withdrawn from the right institution and account.

What comes first on a check, the routing or account number?

Typically, when you look at the lower portion of a check (reading left to right), you’ll see the routing vs. account number first, followed by the account number, and then the actual check number.

The routing number is a nine-digit code that identifies the bank, while the account number indicates your specific account within that bank. Checks are typically numbered to help with record-keeping.

Which number do I provide for direct deposit?

For a direct deposit, you generally need to provide both your routing and account numbers. The routing number ensures the deposit is sent to the correct bank, while the account number directs the funds to your specific account. You may also be asked to provide a voided check.

What happens if you use the wrong routing or account number?

Using the wrong check routing number and/or account number can result in a failed transaction or funds being sent to the wrong account. If your bank catches the mistake, it may reject the transaction. If your bank misses it and the account number belongs to someone else, the money could get deposited into the wrong account. If that occurs, you’ll want to contact your bank immediately to try to remedy the problem.

Are routing numbers the same across all bank branches?

Not necessarily. Smaller banks often have a single routing number for all branches. But if a bank has branches located in different states, routing numbers usually won’t be the same across all branches. Your routing number will typically be based on the branch where you first opened your account.


Photo credit: iStock/SeventyFour


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.

SOBNK-Q426-148

Read more
Someone holding a piggy bank.

Pay Yourself First Budgeting Method: Strategy Explained

Budgeting can be key to financial success, but with so many strategies available, it can feel overwhelming. One simple approach is the pay-yourself-first method. What pay yourself means is turning traditional budgeting upside down by prioritizing saving and financial goals before addressing everyday expenses. In other words, instead of saving what’s left over at the end of the month, you save first — and spend what’s left after.

Whether you’re working toward building an emergency fund, saving for a house, or investing for retirement, you may want to consider the pay-yourself-first strategy. Here’s a closer look at how pay-yourself-first budgeting works and how to put it into practice.

Key Points

•   Pay-yourself-first budgeting involves prioritizing savings before expenses.

•   The method is designed to help build consistent saving habits.

•   To get started you’ll need to assess your current income and spending and possibly trim nonessential spending.

•   Automating savings is a way to save consistently and automatically without even thinking about it.

•   Seeing savings and investment accounts grow may help those who use this method stay motivated.

3 Reasons to Pay Yourself First

What pay yourself first means is to prioritize savings over spending when creating a budget. Here are some reasons why individuals might want to adopt this method that’s sometimes referred to as “reverse budgeting.”

1. To Save Consistently

One of the biggest benefits of the pay-yourself-first budget is that it could create a consistent saving habit. Consider this: Many people intend to save whatever money remains at the end of the month, only to find that there isn’t much — or anything — left.

By paying yourself first, you’re removing the temptation to spend that money. It becomes a non-negotiable — just like your rent or electric bill. You commit to putting aside a set amount each month into a savings account or investment account, treating your future self as a priority. Over time, these small contributions may accumulate into a sizable savings or investment fund, providing financial stability and peace of mind.

2. To Prepare for the Future

Financial emergencies are almost inevitable. Whether it’s a car repair, medical bill, or trip to the vet, unplanned expenses can derail even the most careful budgets. Paying yourself first helps you build a safety net by starting an emergency fund before life throws a curveball.

Beyond emergencies, the pay-yourself-first strategy may also help you work toward long-term financial goals. Whether you’re hoping to buy a home, travel, or fund a child’s education, prioritizing savings makes it easier to achieve big-picture plans without relying on debt. And while retirement may seem a long way off, the sooner you start saving, the more time your money potentially has to grow through compound returns (when returns start earning returns of their own).

3. To Stay Motivated

Budgeting can feel restrictive and discouraging, particularly when the main focus is on cutting expenses and limiting spending. Paying yourself first changes that mindset. Instead of seeing what you’re giving up, you focus on what you’re gaining when you save — a savings account that’s growing and/or a bigger retirement fund, and real progress toward your goals.

Each month that you pay yourself first may be considered another step forward. That sense of progress may inspire you to stay on track, stick with your budget, and look for even more ways to improve your financial well-being.

Recommended: 50/30/20 Budget Calculator

Increase your savings
with a limited-time APY boost.*


*Earn up to 4.40% Annual Percentage Yield (APY) on one SoFi Savings account with a 1.10% APY Boost (added to the 3.30% APY as of 10/20/26) for up to 6 months. Open your first SoFi Checking and Savings account and receive eligible direct deposits OR qualifying deposits of $5,000 every 31 days by 12/31/27. Rates are variable, subject to change. Terms apply at https://www.sofi.com/banking/#4. SoFi Bank, N.A. Member FDIC.

How to Start Paying Yourself First

If the idea of paying yourself first sounds appealing, here’s a simple step-by-step guide to getting started.

1. Assess Your Income and Spending

Before you can determine how much to pay yourself, you’ll need to get a sense of your overall financial picture. You can do this by gathering up the last several months of financial statements to calculate your average monthly income and spending.

Next, you’ll want to categorize your monthly expenses and divide the list into essential spending (like housing, utilities, groceries, debt payments) and nonessential spending (dining out, entertainment, clothing).

Once you have a clear picture of your income and expenses, you can start identifying how much room there is to pay yourself first. Keep in mind that the goal here is to prioritize saving as if it were an essential bill.

2. Determine How Much to Pay Yourself

How much money you should save each month depends on your income, expenses, and goals. A good starting point may be 10% to 20% of your take-home pay, but don’t be discouraged if that feels out of reach at first. Even saving 5% is better than nothing, and you can gradually increase the percentage as your financial situation allows.

To hone in the right amount to pay yourself, you’ll want to consider your short- and long-term financial goals, how soon you want to reach them, and how much you’ll need to save monthly to meet those goals.

If saving for multiple goals feels too overwhelming, you could prioritize. For example, If you don’t have a solid emergency fund, you might start there. To determine how big it should be you can use an emergency fund calculator. Once that’s in place, you might bump up your 401(k) contributions and/or start saving for another goal like a down payment on a home or car or your next vacation. The key is to start somewhere and commit to regular contributions.

3. Trim Unnecessary Expenses

If your current spending habits don’t leave much room for saving, you’ll need to find some places to cut back on spending. The easiest way to find extra money is to look closely at your nonessential spending and consider what you can live without.

Some areas where people tend to overspend include:

•   Eating out or ordering takeout frequently

•   Subscriptions and streaming services

•   Unused gym memberships

•   Impulse purchases or retail therapy

Redirecting even $50 or $100 per month from nonessential spending into savings could make a big difference over time. Trimming the fat in your spending not only eliminates waste, but also helps you start spending with more intention, rather than making decisions impulsively or passively. Like other budgeting methods, such as zero-based budgeting, the pay-yourself-first strategy helps ensure that your spending aligns with your values and goals.

4. Review Your Bank Accounts

To successfully pay yourself first, you need the right banking set-up. It’s generally a good idea to have multiple bank accounts to separate your savings from your everyday spending. This prevents the temptation to dip into savings for nonessential expenses.

At a minimum, you’ll want to have one checking account that doesn’t charge any monthly fees (bonus if it also earns some interest), along with at least one savings account that pays a competitive annual percentage yield (APY). To help grow your savings faster, you may want to open a high-yield savings account at a bank or online bank. These accounts offer significantly higher APYs compared to traditional savings accounts.

5. Automate Your Savings

Once you’ve decided how much to pay yourself each month and where to put those payments, automating your savings is the next step. By setting up automatic transfers from your checking account to your savings accounts, you eliminate the need to make a decision each month. It happens behind the scenes — just like a bill payment.

Consider setting your transfer to occur on the same day you receive your paycheck. This ensures the money is moved before you have a chance to spend it elsewhere. Alternatively, you might see if your employer will do a split direct deposit, where most of your paycheck goes into your checking account and a certain percentage goes directly into savings.

6. Review and Adjust Based on Your Goals

Life is constantly changing, and your personal budget should typically reflect that. It’s generally a good idea to periodically review your financial goals, income, and spending habits to make sure your savings strategy still aligns with your priorities. You might set a reminder in your calendar to review your budget every three to six months, for example. You’ll also likely want to go over your budget whenever you experience a major life change (like a new job, move, or marriage).

Some questions to consider when doing a budget review:

•   Am I meeting my savings goals and saving money fast enough?

•   Can I afford to increase how much I pay myself?

•   Are there any expenses I can reduce or eliminate?

•   Have my financial goals changed?

Adjustments are normal and necessary. The key is to remain proactive and intentional with your money. As your income increases and/or debt decreases, look for opportunities to boost your savings rate and pay yourself even more if you can.

The Takeaway

The pay-yourself-first strategy isn’t simply a budgeting method — it’s a shift in mindset that puts your financial well-being front and center. By prioritizing savings before spending, you can potentially build a habit of consistency, prepare for the future, and stay motivated as you work toward your goals.

This approach to budgeting is also typically easy to implement. To get started, you assess your income and expenses, decide how much to pay yourself based on your financial goals, cut unnecessary expenses to free up savings, and automate your savings to stay consistent.

Remember that it’s fine to start small. Over time, you’ll likely gain momentum and confidence, and those early efforts may pay off in the form of more financial flexibility and greater peace of mind.

Interested in opening an online bank account? When you sign up for a SoFi Checking and Savings account with eligible direct deposit, you’ll get a competitive annual percentage yield (APY), pay zero account fees, and enjoy an array of rewards, such as access to the Allpoint Network of 55,000+ fee-free ATMs globally. Qualifying accounts can even access their paycheck up to two days early.

Better banking is here with SoFi, named the #1 Bank in the U.S. for the fourth year in a row by Forbes (2026).* Enjoy up to 3.30% APY on SoFi Checking and Savings.

FAQ

Are there any disadvantages to paying yourself first?

While paying yourself first may be a powerful savings strategy, it can present challenges if your income is irregular or your monthly expenses are high. Automatically transferring money into savings before covering essentials could cause cash flow issues, especially during emergencies or months with unexpected costs. Prioritizing savings without a flexible plan might also lead to relying on credit cards or loans to make ends meet. It’s important to balance saving with realistic budgeting to avoid financial strain.

What types of accounts are best for paying yourself first?

High-yield savings accounts, retirement accounts, and investment accounts are some types of accounts individuals might wish to consider for the paying yourself first method. For example, high-yield savings accounts generally offer easy access and better interest rates than traditional savings accounts, potentially making them a place to save cash for short-term goals. Retirement accounts may provide tax advantages for long-term saving. Individuals will want to choose their accounts based on their specific goals, time horizon, and tolerance for risk.

How does paying yourself first help with financial stability?

Paying yourself first may help build financial stability by prioritizing savings before spending. The idea is that a person who uses this budgeting strategy would consistently set aside money for emergencies, future goals, and retirement, rather than relying on leftover funds. Over time, pay yourself first might help create a financial cushion that reduces stress, prepares an individual for unexpected expenses, and lessens the need for high-interest debt. Ideally, the approach may also help build long-term financial security.

Can I still pay myself first if I have debt?

It’s possible to pay yourself first even if you have debt, but whether it makes sense to do so generally depends on your specific situation and the type of debt you have. Building savings, even a small emergency fund, might prevent further debt when unexpected expenses arise. However, if you have high-interest debt, you may want to prioritize repaying that first to help reduce the amount of interest you’ll pay. You could eventually put the money you save on interest charges into savings.

What are the biggest challenges of paying yourself first?

One of the biggest challenges of paying yourself first is sticking to the habit, especially when money feels tight or unexpected expenses arise. People with irregular incomes may also find it challenging to divert a set amount of money to savings each month. To overcome these hurdles, they might choose to start small by saving a smaller amount whenever they can.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
SoFi® Checking and Savings is offered through SoFi Bank, N.A. ©2026 SoFi Bank, N.A. All rights reserved. Member FDIC. Equal Housing Lender.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOBNK-Q426-149

Read more
TLS 1.2 Encrypted
Equal Housing Lender