businessman reading newspaper

The Basics of Investment Funds

Investment funds offer a way to pool money with other investors to purchase a collection of securities or other assets. They can make investing more accessible by allowing individuals to gain exposure to a range of investments without having to select and manage each one independently.

There are several types of investment funds, including mutual funds, exchange-traded funds (ETFs), and money market funds. Some focus on stocks or bonds, while others combine different asset classes or follow a particular investment strategy. Funds also vary in how they are managed, how much they cost, and how investors buy and sell shares.

Understanding how investment funds work and how different types compare can help investors evaluate their options and determine whether a particular fund aligns with their financial goals, time horizon, and risk tolerance.

Key Points

•   Investment funds pool money from multiple investors to purchase a portfolio of securities or assets.

•   Common fund types include mutual funds, exchange-traded funds (ETFs), index funds, and money market funds.

•   Funds offer potential benefits such as diversification, simplified portfolio management, and access to different markets.

•   Investors pay operating fees and expenses, such as expense ratios, which can impact potential returns.

•   Investment funds carry risks, and investors can lose money depending on market conditions and underlying holdings.

What Is an Investment Fund?

An investment fund pools money from multiple investors to purchase a portfolio of financial securities or other assets. Investors own shares or units representing a proportional interest in the fund’s holdings.

Investment funds can provide access to a broader range of investments than an individual might be able to purchase independently. They also allow investors to share certain costs associated with managing a portfolio.

Common types of investment funds include mutual funds, exchange-traded funds (ETFs), money market funds, and alternative funds. Some funds are actively managed by professional investment managers who select investments based on the fund’s objectives. Others follow a passive strategy designed to track a market index.

Investors generally pay fees and expenses associated with operating a fund. These costs vary depending on the fund’s structure, investment strategy, and management approach.

Types of Investment Funds

Investment funds can be categorized by how they are structured, what they invest in, or the strategies they follow. Some categories overlap, meaning a single fund may fit into more than one.

Mutual Funds

A mutual fund pools money from investors to purchase a portfolio of securities, such as stocks, bonds, and short-term debt instruments.

Mutual funds can provide investors with access to a diversified portfolio through a single purchase. Rather than buying individual securities and managing them independently, investors can purchase shares in a fund that holds a collection of investments.

For example, an individual with $1,000 may find it difficult to purchase every stock in the S&P 500 and maintain the same proportions as the index. A mutual fund that tracks the S&P 500 can provide exposure to those companies through a single investment, subject to the fund’s minimum investment requirements and fees.

Mutual funds can follow different investment strategies. Some are actively managed, meaning a portfolio manager selects and adjusts investments in an effort to achieve the fund’s objective. Others are passively managed and seek to track a particular market index.

Exchange-Traded Funds (ETFs)

Like mutual funds, ETFs can provide exposure to multiple investments through a single purchase. They may hold stocks, bonds, commodities, or other assets, depending on their objectives.

One key difference is how investors buy and sell shares. ETFs trade on stock exchanges throughout the trading day, much like individual stocks. Their market prices can fluctuate during the day and may differ slightly from their net asset value (NAV).

ETFs can be actively or passively managed. Some track market indexes, while others follow specific investment strategies.

Index Funds

Index funds are designed to track the performance of a particular market index, such as the S&P 500 or the Russell 2000. Rather than attempting to outperform a benchmark through individual security selection, an index fund generally seeks to replicate the index’s holdings or performance, before fees and expenses.

Index funds can invest in stocks, bonds, or other assets. They are often passively managed, which can result in lower operating expenses and less portfolio turnover than some actively managed funds.

Index funds may provide exposure to broad markets or narrower segments, such as large-cap stocks, small-cap stocks, particular sectors, or international markets.

Although index funds are often diversified, their level of diversification depends on the index they track. A fund that follows a narrow sector index, for example, may be more concentrated than one that tracks a broad market index.

An index fund can be structured as either a mutual fund or an ETF. For example, an S&P 500 index fund may be available as a traditional mutual fund or an ETF.

Bond Funds

Bond funds invest primarily in bonds and other debt securities issued by governments, corporations, and other entities. Depending on their objectives, bond funds may hold short-term or long-term bonds, government securities, corporate bonds, municipal bonds, or a combination of these investments.

Bond funds can provide income through interest payments received from their underlying holdings. However, unlike an individual bond held to maturity, a bond fund does not promise to return a specific principal amount on a particular date.

Bond funds carry risks, including interest rate risk and credit risk. Their share prices can decline when interest rates rise or when the credit quality of their underlying holdings deteriorates.

Bond funds may be structured as mutual funds or ETFs.

Balanced Funds

Balanced funds, also known as asset allocation funds, invest in a combination of stocks and bonds. Some also hold cash or other assets. These funds generally maintain a relatively consistent allocation between asset classes, such as 60% stocks and 40% bonds, although the specific allocation varies by fund.

By combining different types of investments, balanced funds seek to provide a mix of growth potential and income while reducing reliance on any single asset class. However, diversification does not eliminate the risk of loss.

Balanced funds can be structured as mutual funds or ETFs.

Target-Date Funds

Target-date funds are designed for investors with a particular goal or time horizon, such as retirement in a specific year. These funds typically hold a mix of stocks, bonds, and other investment funds. Their investment allocation generally becomes more conservative as the target date approaches, although the specific strategy varies by fund.

For example, a target-date retirement fund designed for someone retiring in 2060 may initially hold a relatively high allocation to stocks. Over time, it may gradually shift toward a larger allocation to bonds and other less volatile investments.

Target-date funds, which may be structured as mutual funds or ETFs, can simplify portfolio management by automatically adjusting their asset allocation. However, they do not guarantee a particular return or retirement income, and investors can still lose money.

Money Market Funds

Money market funds are mutual funds that invest in short-term, high-quality debt securities, cash, and cash equivalents. Depending on the fund, holdings may include U.S. Treasury securities, certificates of deposit, commercial paper, or short-term municipal securities.

Money market funds generally have lower risk than many other types of mutual funds, but they are not risk-free. They typically seek to maintain a stable net asset value, often $1 per share, but their share price can fluctuate.

Money market funds are also different from money market accounts offered by banks and credit unions. Money market funds are investments and are not FDIC-insured.

Alternative Funds

Alternative funds invest in assets or use strategies that differ from traditional stock and bond investing. Depending on the fund, these investments may include real estate, commodities, private equity, private debt, or other specialized assets. Some alternative funds also use strategies such as short selling or derivatives.

Alternative funds can diversify your risk and potential returns, but they often come with higher fees, complex structures, and less liquidity.

Some funds focus on real estate investment trusts (REITs), companies involved in commodities production, or other specialized markets. The risks vary considerably depending on the fund’s holdings and strategy.

What Are the Benefits of Investment Funds?

Investment funds offer several features that may appeal to investors. However, their benefits depend on the fund’s structure, investment strategy, and costs.

Diversification

Investment funds can provide exposure to a range of investments through a single purchase. Rather than relying on the performance of one company or security, investors may own shares in a fund that holds securities from multiple companies, industries, or asset classes.

Diversification can help reduce the impact of poor performance by an individual investment. For example, losses in one stock may be offset by gains or smaller losses in other holdings. However, diversification does not guarantee a profit or eliminate the risk of loss. A fund that focuses on a single sector or market segment may also offer less diversification than a broad-market fund.

Access to Different Markets

Investment funds can make it easier for investors to gain exposure to different types of securities, markets, and investment strategies. For example, a fund may focus on international stocks, corporate bonds, real estate, or a particular market index.

This can allow investors to access investments that may otherwise be more difficult or expensive to purchase individually. The types of investments available depend on the fund’s objectives and holdings.

Simplified Portfolio Management

Investment funds can simplify investing by allowing investors to purchase a collection of securities through a single investment. Depending on the fund, professional managers may select investments, monitor the portfolio, and make adjustments as needed. Passively managed funds generally require less frequent portfolio trading because they follow an index.

Some funds also allow investors to set up recurring purchases and automatically reinvest dividends or capital gains distributions. Reinvesting distributions can increase the number of shares an investor owns over time. However, distributions are not guaranteed, and the value of the investment can still decline.

Different Management Strategies

Investment funds offer a range of approaches to managing money. Actively managed funds use investment selection and portfolio management in an effort to achieve a particular objective. Passively managed funds generally seek to track a market index.

Investors can compare these approaches based on their objectives, costs, and investment strategies. Neither approach guarantees positive returns or outperformance.

Liquidity

Many investment funds allow investors to buy or sell shares relatively easily, although the timing and process vary. Traditional mutual funds generally process purchases and redemptions at the next calculated net asset value (NAV), typically determined after the market closes. ETFs trade on stock exchanges throughout the trading day. Their prices may fluctuate during market hours and can differ slightly from their NAV.

Some alternative funds may have limited liquidity or restrictions on when investors can redeem their shares. Investors will want to review a fund’s terms before purchasing shares.

What Are the Costs of Investment Funds?

Investment funds generally charge fees and expenses for operating and managing the fund. These costs vary depending on the fund’s structure and strategy.

One common cost is the expense ratio, which represents a fund’s annual operating expenses as a percentage of its assets. Expense ratios vary widely. Actively managed funds often have higher expense ratios than comparable passively managed funds, although this is not always the case. Some funds may also charge sales loads, transaction fees, redemption fees, or other expenses.

Investors can review a fund’s prospectus and fee information to understand its costs before purchasing shares. Comparing expenses can help investors understand how fees may affect investment returns over time.

Can I Lose Money in an Investment Fund?

Yes. Investment funds are investments, and their value can decline. Investors may lose some or all of the money they put into a fund if the value of its underlying holdings falls significantly. The level of risk depends on the fund’s investments and strategy.

For example, a stock fund may experience substantial losses during a market downturn, while a bond fund may lose value when interest rates rise or issuers experience financial difficulties. Even money market funds carry some risk.

Before purchasing an investment fund, investors can review its prospectus, investment objectives, holdings, historical performance, fees, and risks. Understanding these details can help investors evaluate whether a fund is consistent with their financial goals, time horizon, and risk tolerance.

The Takeaway

Investment funds offer a way to pool money with other investors and gain exposure to a collection of securities or other assets. Mutual funds, ETFs, index funds, and other investment funds come in many forms, with different objectives, strategies, costs, and levels of risk.

Understanding how these funds work and what they hold can help investors evaluate their options and make informed decisions about how investment funds may fit into their broader financial plans.

Ready to invest in your goals? It’s easy to get started when you open an investment account with SoFi Invest®. You can trade stocks, ETFs, or options through self-directed investing with SoFi Securities, or simply automate your investments with a robo advisor from SoFi Wealth. You'll gain access to alternative investments and upcoming IPOs, and can plan for retirement with a tax-advantaged IRA. With SoFi, you can manage all your investments, all in one place.

Take a step toward reaching your financial goals with SoFi Invest.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What are the four types of investment funds?

Four common types of investment funds are mutual funds, exchange-traded funds (ETFs), index funds, and money market funds. Mutual funds and ETFs pool money to purchase a portfolio of securities, while index funds seek to track a particular market index and can be structured as mutual funds or ETFs. Money market funds invest in short-term, high-quality debt securities and cash equivalents. Other types include bond funds, balanced funds, and target-date funds.

What is an example of an investment fund?

An S&P 500 index fund is an example of an investment fund. It pools money from investors to purchase stocks that track the S&P 500, an index of large U.S. companies. Investors can gain exposure to a broad group of companies through a single fund rather than purchasing shares of each company individually. Other examples include bond funds, money market funds, and target-date retirement funds.

How does an investment fund work?

An investment fund pools money from multiple investors to purchase a collection of securities or other assets. Investors purchase shares or units representing a proportional interest in the fund’s holdings. Depending on the fund’s strategy, a professional manager may select investments, or the fund may passively track a market index. Investors may receive income through dividends or interest, and the value of their shares can fluctuate based on the performance of the underlying assets. Funds generally charge fees and expenses for their operation and management.

What are the top five investment funds?

There is no universal ranking of the top five investment funds. The right fund depends on an investor’s financial goals, time horizon, risk tolerance, and investment strategy. Five common categories to research include:

•   S&P 500 index funds: Track large U.S. companies.

•   Total stock market index funds: Provide exposure to a broad range of U.S. stocks.

•   International stock funds: Offer exposure to companies outside the United States.

•   Bond funds: Invest in debt securities and may provide income.

•   Target-date funds: Adjust their asset allocation over time based on a specified goal date.

Investors can compare individual funds within these categories by reviewing their objectives, holdings, fees, and risks.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.

Investment Risk: Diversification can help reduce some investment risk, but cannot guarantee profit nor fully protect in a down market.

Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOIN-Q426-079

Read more
Mutli-colored gas pump handles.

How to Invest in Oil and Gas: Buying Oil Stocks & ETFs

Oil is valuable, and one of the most widely used and widely traded commodities in the world. Despite the growth of many forms of alternative energy, oil remains essential to the global economy. But there are many variables that factor into oil prices, and that makes them fairly volatile, often changing numerous times on a daily basis.

The price of oil has an impact on a wide range of industries, and ultimately on the prices that consumers pay at the pump, in the supermarket, and beyond. That also means it may be attractive to some investors, though it also comes with risks to be aware of.

Key Points

•   Investing in oil may be attractive to some investors due to its critical role in global industry and transportation, despite the rise of alternative energy sources.

•   Various investment options exist, including oil company stocks, mutual funds, ETFs, and exchange-traded notes that track oil prices directly.

•   Market dynamics, including OPEC decisions, global supply and demand fluctuations, and production costs, may influence oil prices.

•   Natural disasters and geopolitical tensions could lead to significant price changes, affecting both supply and investor sentiment in the oil sector.

•   Oil investment carries inherent risks due to its volatility, making thorough research and consideration of individual investment goals essential before proceeding.

How Do You Invest in Oil?

For those who are interested in incorporating crude oil investing in their portfolio, there are many ways to get started.

How to Buy Oil Stocks

In addition to the massive, well-known companies in the fossil fuel industry, there are other companies that specialize in different aspects of energy production, oil exploration, drilling, equipment, delivery and more. There are also smaller oil companies with vertical operations, but only in specific parts of the world. Each of those types of companies may perform differently depending on the many geopolitical, economic, technological, and other factors that drive the price of oil up and down.

Recommended: Investing in the Energy Sector: What Any Investor Should Know

Oil Mutual Funds and ETFs

Not every investor has the time or interest to research a host of oil companies. For those investors, another approach might be investing in a mutual fund or exchange-traded fund (ETF) that focuses on the oil sector, or more broadly on the energy sector.

Since thematic ETFs and mutual funds hold many securities, they offer investors a level of diversification within their portfolio. At the same time, diversification would be more limited in an oil fund than in a broader index fund — if the entire industry is in a downturn, an oil fund may fall, as well. Diversification can also never fully protect investors from downside risks.

Recommended: Key Differences between Mutual Funds and ETFs

Oil Futures and Derivatives

More sophisticated investors may also consider investing in the derivatives markets, trading futures and options. Purchasing crude oil barrels may require tens of thousands of dollars, but investors may gain exposure to oil investments through options and futures. Crude oil options trade on the New York Mercantile Exchange (NYMEX) and on the ICE exchange, for example.

Derivatives are complex financial instruments that allow traders to speculate on the price movements of an underlying asset. They can be used to increase purchasing power through leverage. With leverage, investors can essentially take a bigger position with less money. Leverage has the potential to amplify returns, but it can also amplify losses if prices move in an adverse direction, making these investments high-risk and generally used by experienced investors.

Oil Exchange-Traded Notes (ETNs)

Exchange-traded notes are unsecured debt securities issued by financial institutions that track the performance of underlying assets, such as indexes or, in this case, oil commodity futures or another oil commodity benchmark. ETNs promise to pay investors the return (if any) on the underlying asset over a specified period of time, plus return the principal investment.

ETNs are considered higher-risk due to the credit risk involved — it’s possible the issuers could default on the payments they owe. In addition, the structure of oil ETNs could in of themselves be riskier. Some, for example, utilize leverage (or inverse leverage) to speculate on the daily performance of an underlying asset, which could scale both rewards and losses.

Alternative Investments

Investors interested in alternative investments — investments outside of traditional stocks, ETFs, bonds, and cash-equivalents — might get exposure to oil by purchasing mineral rights or buying into Limited Partnerships (LPs) that invest throughout the sector. Alternatives are also generally considered higher risk than traditional assets due to potential factors such as valuation complexity, illiquidity, and possible lack of transparency, depending on the asset.

Oil prices plummeted in 2020, as pandemic-associated lockdowns drove U.S. oil prices into negative territory for the first time in history. In April 2020, investors bid the price for West Texas Intermediate (WTI) from $18 per barrel, down to roughly negative $37 a barrel.

Later that year, oil prices began to normalize. Demand returned in 2021, and oil prices shot back up in 2022, when they reached levels not seen in decades. Then, in 2023, prices did fall a bit again, and bounced around $60 or $80 for a while. In early 2026, military conflicts in the Middle East caused another spike, and prices rose above $100 – as of late September 2026, prices are hovering around the $100 mark.

Forces That Drive Oil Prices

There are many factors that determine oil prices. That, in turn, could affect prices for gasoline and more. Here are some of the forces at play.

The Organization of Petroleum Exporting Countries (OPEC)

Another important contributor to oil prices is the Organization of Petroleum Exporting Countries (OPEC), a group of 12 oil-producing countries, including Algeria, Congo, Equatorial Guinea, Gabon, Iran, Iraq, Kuwait, Libya, Nigeria, Saudi Arabia, the United Arab Emirates, and Venezuela.

Together, they’re responsible for nearly 80% of the planet’s oil reserves. As an organization, OPEC meets regularly to set production levels. And its decisions could directly change the price of oil and gas. And while it has a massive influence on the price of oil, it doesn’t control the price.

Market Fundamentals

The global oil market is a force in its own right, as supply and demand tend to fluctuate sharply and unpredictably. There might be too much supply, causing prices to fall. Within OPEC, members don’t always follow through on the limits they agreed upon limits. There are also major oil suppliers, such as the United States, who are not OPEC members who may produce more oil than expected. That could cause high levels of supply relative to demand, which could drive down prices.

Production Costs

Oil in Canada’s oil sands or American shale reserves is far more labor-intensive and expensive to extract and refine than the oil in the Middle East. Those extraction costs contribute to the price of the oil, which might drive the oil prices higher or lower, depending on where the bulk of supply is coming from at any given time.

Natural Disasters

Oil prices are also susceptible to change as a result of natural disasters. Hurricanes, for example, regularly shut down oil production in the Gulf of Mexico, which could reduce the supply of oil and drive prices up.

International Relations

The headlines, especially international ones, could also drive oil prices. A significant amount of the world’s oil comes from the Middle East. Political instability in that region creates investor uncertainty, which might lead to price fluctuation. The same goes for countries like Russia, which produces a lot of oil, but is often involved in geopolitical conflicts, and several countries in the Middle East.

Economic Factors

While not always the case, recessions and economic turmoil could push oil prices lower.

The relative strength of the U.S. dollar also plays a role in the price of oil. The thinking is that a strong dollar allows American oil companies to buy more oil, and cut the cost to U.S. consumers, who buy a good percentage of the oil on the market.

However, while oil does not typically perform well during a recession, it does typically become more attractive to investors later in the business cycle.

Is an Oil Investment Safe?

While there may be longstanding demand for oil, it’s important to keep in mind that no investment is “safe.” Oil is volatile, and there are many factors and variables that can influence its supply and demand. Investors should remember that just because oil prices are up one day, they may fall the next. That could affect oil investments, as well as the broader economy.

Investors have different options to choose from to gain exposure to oil, from oil-related stocks, ETFs, and mutual funds to potentially higher risk choices, such as exchange traded notes (ETNs) and oil derivatives. Each has its own risk profile, and it’s important to understand the potential for both rewards and losses before investing in any type of oil asset.

The Takeaway

Oil is always in demand and important to the global economy, which makes it an attractive investment to some investors. Oil is also a volatile and higher risk investment, however, and risk exposure may also vary depending on how you may choose to invest in it, such as through stocks, ETFs, or derivatives. Given that many people are focused on renewable energy sources, too, investing in oil may not be quite as attractive as it once was.

It’s worth considering what role the different types of oil investments might have in your portfolio, and whether they align with your objectives.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What are the best ways to start an oil investment?

There are several ways to potentially invest in oil either directly or indirectly, including oil company stocks, mutual funds, ETFs, and exchange-traded notes that track oil prices directly.

What factors determine oil prices?

There’s a long list of variables that may affect oil prices, including the goals of cartels like OPEC, production costs, natural disasters, and international relations or military conflicts.

What is OPEC?

OPEC is the Organization of Petroleum Exporting Countries (OPEC), a group of 12 oil-producing countries, including Algeria, Angola, Congo, Equatorial Guinea, Gabon, Iran, Iraq, Kuwait, Libya, Nigeria, Saudi Arabia, the United Arab Emirates, and Venezuela. OPEC makes up nearly 80% of the planet’s oil reserves.

How much money do you need to start investing in oil?

It may be possible to start investing in oil with very little capital, as investors may be able to buy shares of oil-related ETFs or fractional shares of oil-related stocks, with as little as $1 to $100 dollars. Mutual funds often have a higher minimum than ETFs. The amount required to invest in oil derivatives could be substantially higher depending on the contract size and type.

Are there sustainable alternatives to investing in oil?

There are many potential sustainable alternatives to investing in oil, and those could include renewable energy stocks, clean energy funds, or even green bonds. These all have their own pros and cons, of course, so investors should do their research before investing in them.


Photo credit: iStock/kckate16


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Before investing, carefully consider the investment objectives, risks, charges, and expenses detailed in a Fund’s prospectus. This document contains important information and must be read carefully prior to investing; you can find the current prospectus by clicking the link on the Fund’s respective page.
Alternative investments are highly risky and may not be suitable for all investors. These investments often involve leveraging, speculative practices, and the potential for complete loss of investment. They typically charge high fees, lack diversification, and can be highly illiquid and volatile. Be aware that both registered and unregistered alternative investments, including Interval Funds, are not subject to the same regulatory requirements as mutual funds, and their illiquid nature may restrict your ability to trade on your timeline. Always review the specific fee schedule for Interval Funds within their prospectus.


Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.

SOIN-Q326-144

Read more
Someone writes down notes at a desk while using a laptop computer.

How to Calculate Dividend Yield: Meaning & Formula

Dividend yield is a financial ratio that shows how much a company pays in dividends each year relative to its stock price. It’s expressed as a percentage and helps investors evaluate income potential from dividends.

Dividend yield concerns how much an investor potentially realizes from their investments over the course of a year as a result of dividends. Dividends, which are payouts to investors as a share of a company’s overall profit, could help investors generate returns, and some investors even formulate entire strategies around maximizing dividends.

But it’s important to have a good understanding of dividends, dividend yields, and other related concepts before going too far into the weeds.

Key Points

•   Dividend yield represents the annual dividend paid to shareholders relative to the stock price, expressed as a percentage, which helps investors assess potential returns.

•   Investors can calculate dividend yield by dividing the annual dividend per share by the stock’s current price, providing insight into a company’s attractiveness as an investment.

•   A higher dividend yield may signal an established company, but it may also indicate slower growth or potential financial troubles, requiring careful evaluation.

•   Considering the history of dividend growth and the dividend payout ratio could provide additional insights into a company’s financial health and dividend sustainability.

•   Understanding the difference between dividend yield and dividend rate is essential, as dividend yield is a ratio while dividend rate is expressed in dollar amounts.

What Does Dividend Yield Mean?

A stock’s dividend yield is how much the company annually pays out in dividends to shareholders, relative to its stock price. The dividend yield is a financial ratio (dividend/price) expressed as a percentage, and is distinct from the dividend itself.

Dividend payments are expressed as a dollar amount, and supplement the return a stock produces over the course of a year. For an investor interested in total return, learning how to calculate dividend yield for different companies might help to decide which company may be a better investment.

But bear in mind that a stock’s dividend yield will tend to fluctuate because it’s based on the stock’s price, which rises and falls. That’s why a higher dividend yield may not be a sign of better value. This can all be important to understand if you plan to buy stocks online or otherwise start investing.

For more background, it may be helpful to review a beginner’s guide to the stock market.

How Does Dividend Yield Differ From Dividends?

It’s important to really drive home the difference between dividend yield and dividends in general.

Dividends are a portion of a company’s earnings paid to investors and expressed as a dollar amount. Dividends are typically paid out each quarter (although semi-annual and monthly payouts are common). Not all companies pay dividends.

Dividend yield, on the other hand, refers to a stock’s annual dividend payments divided by the stock’s current price, and expressed as a percentage. Dividend yield is one way of assessing a company’s earning potential.

How to Calculate Dividend Yield

Calculating the dividend yield of an investment is useful for investors who want to compare companies and the dividends they pay. For investors looking for investments to help supplement their cash flow, or even to possibly live off dividend income, a higher dividend yield on a stock would be more attractive than a lower one.

It may be helpful to experiment with a stock profit calculator to try and develop a deeper understanding of how this may affect overall potential returns.

What Is the Dividend Yield Formula?

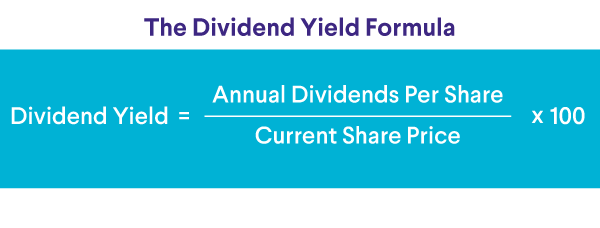
The dividend yield formula is more of a basic calculation than a formula: Dividend yield is calculated by taking the annual dividend paid per share, and dividing it by the stock’s current price.

Annual dividend / stock price = Dividend yield (%)

Dividend Yield Formula

How to Work Out Dividend Yield Step-by-Step

Investors can calculate the annual dividend of a given company by looking at its annual report, or its quarterly report, finding the dividend payout per quarter, and multiplying that number by four. For a stock with fluctuating dividend payments, it may make sense to take the four most recent quarterly dividends to arrive at the trailing annual dividend.

It’s important to consider how often dividends are paid out. If dividends are paid monthly vs. quarterly, you want to add up the last 12 months of dividends.

This is especially important because some companies pay uneven dividends, with the higher payouts toward the end of the year, for example. So you wouldn’t want to simply add up the last few dividend payments without checking to make sure the total represents an accurate annual dividend amount.

Example of Dividend Yield

If Company A’s stock trades at $70 today, and the company’s annual dividend is $2 per share, the dividend yield is 2.85% ($2 / $70 = 0.0285).

Compare that to Company B, which is trading at $40, also with an annual dividend of $2 per share. The dividend yield of Company B would be 5% ($2 / $40 = 0.05).

In theory, the higher yield of Company B may look more appealing to some investors. But investors can’t necessarily determine a stock’s worth by yield alone.

Start investing with up to $1,000 in stock.

Open and fund a SoFi Active Invest account and get up to $1,000 in stock.*


*Customer must fund their Active Invest account with at least $50 within 45 days of opening the account. Probability of customer receiving $1,000 is 0.028%. See full terms and conditions. Screen images simulated.

Dividend Yield: Pros and Cons

thumb_up

Pros:

•   May help with company valuation.

•   May indicate how much dividend income investors might expect.

thumb_down

Cons:

•   Dividend yield could indicate a more established, but slower-growing company.

•   Higher yield may mask deeper problems.

•   Yield doesn’t tell investors the type of dividend (ordinary vs. qualified), which could impact taxes.

For investors, there are some advantages and disadvantages to using dividend yield as a metric that helps inform investment choices.

Pros

•   From a valuation perspective, dividend yield may be a useful point of comparison. If a company’s dividend yield is substantially different from its industry peers, or from the company’s own typical levels, that could be an indicator of whether the company is trading at the right valuation.

•   For some investors, the primary reason to invest in dividend stocks is for income. In that respect, dividend yield could be an important metric. But dividend yield might change as the underlying stock price changes. So when using dividend yield as a way to evaluate income, it’s important to be aware of company fundamentals that provide assurance as to company stability and consistency of the dividend payout.

Cons

•   Sometimes a higher dividend yield could indicate slower growth. Companies with higher dividends are often larger, more established businesses. But that could also mean that dividend-generous companies are not growing very quickly because they’re not reinvesting their earnings. You can also learn more about dividend reinvestment plans.

Smaller companies with aggressive growth targets are less likely to offer dividends, but rather spend their excess capital on expansion. Thus, investors focused solely on dividend income could miss out on some faster-growing opportunities.

•   A high dividend yield could indicate a troubled company. Because of how dividend yield is calculated, the yield is higher as the stock price falls, so it’s important to evaluate whether there has been a downward price trend. Often, when a company is in trouble, one of the first things it is likely to reduce or eliminate is that dividend.

•   Investors need to look beyond yield to the type of dividend they might get. An investor might be getting high dividend payouts, but if they’re ordinary dividends vs. qualified dividends they’ll be taxed at a higher rate. Ordinary dividends are taxed as income; qualified dividends are taxed at the lower capital gains rate, which typically ranges from 0% to 20%. If you have tax questions about your investments, it may be helpful to consult with a tax professional.

The Difference Between Dividend Yield and Dividend Rate

A dividend is a way for a company to distribute some of its earnings among shareholders, as noted earlier. Dividends might be paid monthly, quarterly, semi-annually, or even annually (although quarterly payouts tend to be common in the U.S.). Dividends are expressed as dollar amounts. The dividend rate is the annual amount of the company’s dividend per share.

A company that pays $1 per share, quarterly, has an annual dividend rate of $4 per share.

The difference between this straight-up dollar amount and a company’s dividend yield is that the latter is a ratio. The dividend yield is the company’s annual dividend divided by the current stock price, and expressed as a percentage.

What Is a Good Dividend Yield?

dividend yield of sp500 vs dividend aristocrats

Two companies with the same high yields are not created equally. While dividend yield is an important number for investors to know when determining the annual cash flow they might expect from their investments, there are deeper indicators that investors may want to investigate to see if a dividend-paying stock will continue to pay in the future.

A History of Dividend Growth

When researching dividend stocks for a self-directed investment account, one place to start is by asking if the stock has a history of dividend growth. A regularly increasing dividend is an indication of earnings growth and typically a good indicator of a company’s overall financial health.

The Dividend Aristocracy

There is a group of S&P 500 stocks called Dividend Aristocrats, which have increased the dividends they pay for at least 25 consecutive years. Every year the list changes, as companies raise and lower their dividends.

As of writing, there are 69 companies that meet the basic criteria of increasing their dividend for a quarter century straight. They include big names in energy, industrial production, real estate, defense contractors, and more, which often resembles a list of blue chip stocks.

Dividend Payout Ratio (DPR)

Investors could calculate the dividend payout ratio by dividing the total dividends paid in a year by the company’s net income. By looking at this ratio over a period of years, investors may learn to differentiate among the dividend stocks in their portfolios.

A company with a relatively low DPR is paying dividends, while still investing heavily in the growth of its business. If a company’s DPR is rising, that’s a sign the company’s leadership likely sees more value in rewarding shareholders than in expanding. If its DPR is shrinking, it’s a sign that management sees an abundance of new opportunities abounding. In extreme cases, where a company’s DPR is 100% or higher, it’s unlikely that the company will be around for much longer.

Other Indicators of Company Health

Other factors to consider include the company’s debt load, credit rating, and the cash it keeps on hand to manage unexpected shocks. And as with every equity investment, it’s important to look at the company’s competitive position in its sector, the growth prospects of that sector as a whole, and how it fits into an investor’s overall plan. Those factors will ultimately determine the company’s ability to continue paying its dividend.


Test your understanding of what you just read.


The Takeaway

Dividend yield is a simple calculation: You divide the annual dividend paid per share by the stock’s current price. Dividend yield is expressed as a percentage, versus the dividend (or dividend rate) which is given as a dollar amount. The dividend yield formula may be a valuable tool for investors, and not just ones who are seeking cash flow from their investments.

Dividend yield could help assess a company’s valuation relative to its peers, but there are other factors to consider when researching stocks that pay out dividends. A history of dividend growth and a good dividend payout ratio (DPR), as well as the company’s debt load, cash on hand, and credit rating could help form an overall picture of a company’s health and probability of paying out higher dividends in the future.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

Can a stock’s dividend yield be negative?

Dividend yield cannot be negative, as that would effectively be shareholders paying a tax or fee – a stock may have no dividend yield, however. But if yield is below zero, then there is no yield at all.

Why do some profitable companies pay no dividends?

There can be a variety of reasons that profitable companies choose not to pay or issue dividends, but generally, it’s because they’re reinvesting earnings and profits in an effort to fuel further growth or expansion.

Are high dividend yield stocks always safe investments?

There is no such thing as a safe investment, but stocks with high dividend yields tend to be older or more established and stable, which some investors may translate as being associated with lower relative risk.

How often do companies update their dividend yields?

Dividend yields are often updated continuously, and in real-time, though it depends on the specific company or stock.

Does a stock split affect the dividend yield?

A stock split should not affect dividend yields as dividend per share and the actual share price should change or adjust proportionately.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
S&P 500 Index: The S&P 500 Index is a market-capitalization-weighted index of 500 leading publicly traded companies in the U.S. It is not an investment product, but a measure of U.S. equity performance. Historical performance of the S&P 500 Index does not guarantee similar results in the future. The historical return of the S&P 500 Index shown does not include the reinvestment of dividends or account for investment fees, expenses, or taxes, which would reduce actual returns.

SOIN-Q326-085

Read more
Presentation Of Chart With Pieces Of Doughnut

How to Buy Stock: Where and How Do You Purchase Stocks?

A stock is a share of ownership in a company. Theoretically, individuals may buy stock in a publicly traded company as long as they have access to an investment account.

In addition to buying shares of stock directly, it’s also possible to own stock through pooled investments, such as mutual funds or exchange-traded funds (ETFs). Investors who can’t afford a full share of stock in some higher-priced companies might choose to invest in a product known as fractional shares.

Read on to learn more about how to buy stock.

Key Points

•   Investors may buy or sell a stock in publicly traded companies via a public stock exchange.

•   Private companies may also issue shares of stock, but these are not available on public stock exchanges.

•   To buy a stock, an investor needs a brokerage account or a retirement account.

•   An investor might open an account at a full-service brokerage firm, a discount brokerage, an online platform, or a robo-advisor platform.

•   It’s possible to buy stocks through pooled investments like mutual funds and exchange-traded funds ( ETFs), or to invest in a fraction of a share of stock.

Where Can I Purchase Stock?

Individuals can purchase stocks through a brokerage account or a retirement account like an individual retirement account (IRA). You can set up an account at a full-service brokerage firm, which offers a variety of financial services including investment advisors; a discount brokerage that has fewer services and charges lower fees than a full-service brokerage; and an online brokerage that offers online trading and may charge even lower (or no) fees.

Once you choose the type of brokerage you want, set up an account, and fund it (typically, by transferring money into it from your bank account), you can begin buying stocks, including trading stocks online.

When choosing a brokerage, investors can compare the different options to help decide which one will best fit their needs. They can check into the investment fees brokerages may charge, such as maintenance fees, transaction fees, and commissions. Also, it’s wise to find out if there’s a minimum balance to start buying stocks. At some online brokerages, investors can get started with as little as $1 to $5.

How Do You Buy Stocks in 5 Steps?

There are generally five basic steps to buying stocks from start to finish. Here’s what they involve.

Step One: Think About What You Want to Buy

To start, investors may want to decide whether they’re interested in buying full shares of individual stocks, fractional shares of a stock, or investing in a fund, such as a mutual fund or exchange-traded fund (ETF).

Individual Stocks

A stock represents a share of ownership in a publicly traded company. Many companies offer both common and preferred stock.

•   Preferred stock generally does not come with voting rights, but dividend payments on these shares are prioritized over common stock dividend payments.

•   Common stock comes with voting rights. These shares may be more volatile, but might provide higher long-term returns. Common stock only pays dividends after preferred stock dividends are paid.

Stocks may provide a return on investment in two ways. The first is through potential price appreciation (though this is never guaranteed). The second is through dividend payments to shareholders, if applicable.

Ideally, shareholders may be able to benefit from a company’s share value increasing over time, as the company’s earnings and market presence expand. However, it’s very difficult to predict which stocks — and which businesses — will be successful in the future.

Individual stocks may be volatile and riskier than other types of investments, such as diversified index funds like the S&P 500 — although they may also provide the potential for higher rewards.

Fractional Shares

Fractional shares of stock offer investors the chance to buy a percentage of a share of stock, rather than owning a full share. Previously, fractional shares were available only to institutional investors, but now retail investors can also buy them, assuming their brokerage offers them.

Owning a fractional share of a stock allows investors to realize gains, losses, and even dividend payments proportional to the fractional ownership amount.

One reason an investor might choose fractional shares investing is to manage cost. Shares of certain companies can be expensive. For example a share of stock of a company worth $1,000 might be available to investors as a fractional share for $100 (a 0.1% share).

Funds

A fund, whether it’s an ETF or a mutual fund, might be thought of as a bundle of investments. Often, these funds invest in stocks, but they may also hold bonds, real estate, or cash. For example, it’s possible to buy an S&P 500 mutual fund or ETF that holds the stocks of the top 500 publicly traded companies in the U.S.

An investment in an ETF or mutual fund that invests in a wide range of stocks is generally considered less risky than owning individual stocks because funds generally offer broad market exposure and may help an investor diversify their portfolio. However, as with all investments, there is risk involved in investing in funds. Diversification doesn’t guarantee profits and it’s possible to lose money.

Start investing with up to $1,000 in stock.

Open and fund a SoFi Active Invest account and get up to $1,000 in stock.*

Prefer mobile? Download the app:

*Customer must fund their Active Invest account with at least $50 within 45 days of opening the account. Probability of customer receiving $1,000 is 0.028%. See full terms and conditions. Screen images simulated.

Step Two: Determine What Type of Account to Open

The next decision for an investor is whether to open a brokerage account or a retirement account.

There are several differences between a brokerage account and a retirement account, with one fundamental difference being the tax treatment of assets in these accounts.

•   Brokerage accounts allow investors to buy and sell securities. They are typically taxable accounts. There are no contribution limits or withdrawal penalties with brokerage accounts.

•   Retirement accounts are tax-advantaged accounts that can hold investments and savings. Tax-deferred accounts (like traditional IRAs) typically defer taxes on investment gains until retirement. With after-tax accounts, like Roth IRAs, qualified withdrawals are tax-free in retirement. However, retirement accounts have annual contribution limits as well as strict withdrawal rules.

Investors may choose to open a brokerage account if they’re already covered by a retirement plan through work like a 401(k). If they opt for a retirement account, investors could open a Roth IRA or a traditional IRA, or a SEP IRA if they’re self-employed.

Recommended: Understanding Dollar-Cost Averaging

Step Three: Decide Where to Open an Account

When it comes to deciding where to open an account, investors have plenty of options, including these:

•   Discount brokerage: One option is to open an account at a low-cost or discount brokerage. Depending on the firm, there may be account and trading fees, but these fees tend to be much lower than those charged by full-service brokerage firms.

•   Online trading platform: Another popular option is to use an online investment platform, where investors can buy shares of stocks and ETFs right from an app. Online trading platforms may offer low or no fees. These days, there is a great deal of overlap between discount and online brokerages, as the former moves increasingly online.

•   Robo-advisor platforms. These services offer automated investment portfolios that typically consist of low-cost ETFs or index funds rather than individual stocks. Robo-advisor platforms may help investors manage a portfolio over time through automated asset allocation and portfolio rebalancing.

•   Full-service brokerage firm: These firms tend to offer expanded services, such as advisors, brokers, and wealth management advisors who can help individuals execute trades, monitor their investments, and more. These services tend to come with much higher costs.

Once an investor has chosen a brokerage or platform, they can typically open an account online by providing information like their Social Security number, date of birth, address, and employment details.

Step Four: Fund Your Account With Cash

The next step in buying stock is to fund the account with cash. Depending on the institution, investors may be able to set up a link to an existing bank account to deposit money into their investment account.

Investors may also be able to sign up for an automated monthly transfer. In this way, money is deposited in the investment account regularly (without the need to remember to do so).

Another funding option is to use a brokerage’s cash management account, which usually offer a combination of checking and savings account features, and are linked to investment accounts.

Step Five: Place a Trade to Purchase Stock

Once the account is funded, an investor can navigate to the area of the dashboard or app that says either buy, sell, or trade.

Here, investors can indicate what stock they would like to buy and specify how many shares, typically using the ticker symbol (a short abbreviation for each stock or fund name).

If buying a stock or an ETF, investors may also need to indicate the order type, though the default is typically a market order — an instruction to buy or sell immediately at the best available current price. Both stocks and ETFs trade on an exchange, like the New York Stock Exchange or the Nasdaq. On these exchanges, prices fluctuate throughout the day. Mutual funds do not trade on an open exchange and their value is calculated once per day.

Recommended: Dividend Yield: What It Is

Understanding Market vs Limit Orders

There are different stock market order types. When purchasing stock, new investors may want to stick to the basics: either a market order or a limit order.

•   A market order will be executed as soon as possible, at the best available price. The order can fill quickly, but it may not be instantaneous. Therefore, the price could change slightly from the original quote. If an investor places a market order, they may want to have a slight cash cushion to protect from any erratic changes in price. If placing a market order while the market is closed, the order is typically filled at the market’s open, at whatever the prevailing price per share is at that time.

•   A limit order focuses on pricing precision. With a limit order, investors name the parameters for the order. For example, an investor could say that they only want to purchase a stock if it falls below $70 per share. Therefore, the order is placed if the stock falls below $70 per share. This means it’s possible a limit order won’t get filled if it doesn’t reach the investor’s pre-selected price parameters, but it also means the investor won’t pay more than they planned to.

Finally, an investor can execute the trade by pressing the “buy” button. Once the trade is executed, the investor then owns the stock.

The Takeaway

With today’s evolving technology, it’s relatively easy for individuals to buy stock. They might open an investment account at a brokerage or online platform of their choice, for example, and buy shares of company stock directly on a stock exchange.

Investors may also choose to buy a bundle of stocks or other assets through a mutual fund or ETF, or invest in fractional shares, in which they buy a percentage of a single share of stock. Each investor can determine what investments make the most sense for their specific financial situation and goals.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What is the minimum amount of money needed to buy stock?

An investor can often start buying stocks with very little money. Some brokerages allow individuals to begin investing, with as little as $1 to 5, for example. Many brokerage platforms also offer fractional investing that may allow investors to buy fractions of a share of stock for just a few dollars, depending on the price of the stock.

How do I buy stocks without a broker?

You can buy stocks without a traditional broker through an online trading platform. To do this, you could set up an investment account with a brick and mortar financial services firm, discount broker, or an online brokerage. Once you set up your account and fund it, you could start researching and buying stocks. If you wish to buy stocks directly on your own, you may explore direct stock plans or dividend reinvestment plans (DRIPs) offered by some companies.

How do you make money from owning stocks?

You have the potential to make money from owning stocks if you’re able to sell them for a higher price than you bought them for, though price appreciation is never guaranteed and it’s possible prices may decline instead. You may also make money from owning stocks if the company pays dividends, which is when a company periodically distributes a portion of their net earnings to shareholders. However, not all companies pay dividends.

Are there fees associated with purchasing stock?

There may be fees involved with purchasing stock, such as commission, transaction, and maintenance fees, depending on the type of brokerage or investment platform an investor uses. Full-service brokerage firms typically charge the highest fees, while discount brokerages usually charge less, and some online brokers have low or no fees.

Do you have to pay taxes on your stock investments?

When you sell a stock in a taxable brokerage account and make a profit on it, those earnings are generally subject to capital gains tax. The rate at which you’re taxed depends on how long you held the stock before selling it. Typically, if you held the stock for a year or less (short-term), you will be taxed at your ordinary income tax rate. If you held the stock longer than a year (long-term), you’ll be taxed at a rate ranging from 0%, 15%, or 20%, depending on your taxable income and filing status. Dividends from a stock are also generally taxable.


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.
Tax Information: This article provides general background information only and is not intended to serve as legal or tax advice or as a substitute for legal counsel. You should consult your own attorney and/or tax advisor if you have a question requiring legal or tax advice.
Third Party Trademarks: Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®

SOIN-Q326-079

Read more
days of the month on pieces of paper.

Settlement Date vs Trade Date & How Long Settling Takes

The day a trader’s buy or sell order is executed in the market is known as the trade date. The settlement date is when the security and cash legally change hands, making the investor the official owner of the asset.

The period of time between the trade date (designated as “T”) and the settlement date varies by asset class. Following a regulatory update by the U.S. Securities and Exchange Commission (SEC), the standard settlement window for most securities — including stocks, bonds, and exchange-traded funds (ETFs) — moved from two business days (T+2) to a single business day (T+1).

Understanding this timeline is important for investors, as officially owning a security or waiting for transaction cash to clear directly impacts subsequent trading decisions and account cash management.

Key Points

•   The trade date is when the investor executes a trade; the settlement date is when the security legally changes hands.

•   Historically, paper trades were common, and the gap between the trade and settlement dates generally took five days, or T+5.

•   In 2017, the time between trade and settlement shifted to T+2, thanks to advances in technology.

•   In May of 2024, the SEC issued a new rule that most trades should settle within one business day (or T+1).

•   Given recent technological developments, some people believe T+0, or real-time settlement, is possible.

What Is a Settlement Date in Investing?

In investing, the settlement date is the specific day a transaction becomes final and the investor takes legal ownership of a security. For years, the standard settlement cycle for most assets was two business days after the trade date, known as T+2. However, following a regulatory shift by the SEC in May 2024, the financial markets transitioned to an accelerated timeline, compressing the standard settlement window down to just one business day (T+1).[1]

Types of Settlement Dates

Depending on the type of security involved in a trade or transaction, settlement dates may vary. That said, you can generally expect a settlement date to be one business day following the sale or purchase of a stock, bond, or ETF. This is sometimes referred to as “T+1,” meaning “trade date, plus one day” to settle.

While certain specialized transactions, such as primary market underwritings for newly issued debt, may utilize custom or extended settlement timelines, standard “regular way” trades for corporate, municipal, and government bonds now all adhere to this uniform T+1 standard.

Note that the time to settle is the same whether you’reinvesting online or through a traditional brokerage.

Trade and Settlement Dates Explained

To recap, the trade date is the specific day an investor’s buy or sell order is executed in the market. Once the order is filled, the price is locked in, and the investor assumes full market risk for the position. For example, if a stock order executes on a Tuesday, that Tuesday is the official trade date.

Following execution, the transaction undergoes an institutional clearing process. Under current regulatory standards, standard transactions for stocks, bonds, and ETFs require exactly one business day to complete. Therefore, a trade executed on Tuesday will legally settle on Wednesday, provided it is not a market holiday.

Why Is There a Delay Between Trade and Settlement Dates?

Given modern technology, it seems reasonable to assume that everything should happen instantaneously. But settlement rules go back decades, to the creation ofthe Securities and Exchange Commission (SEC) in 1934, when all trading happened in person, and on paper.

Back then, a piece of paper representing shares of a security had to be in the possession of traders in order to prove they actually owned theshares of stock. Paper transactions sometimes took as long as five business days after the trade date, or T+5.

Recommended: A Brief History of the Stock Market

Start investing with up to $1,000 in stock.

Open and fund a SoFi Active Invest account and get up to $1,000 in stock.*


*Customer must fund their Active Invest account with at least $50 within 45 days of opening the account. Probability of customer receiving $1,000 is 0.028%. See full terms and conditions. Screen images simulated.

What Is the T+1 Rule?

The T+1 rule refers to the fact that it now takes one day for a trade to settle. For example, if a trade is executed on Tuesday, the settlement date will be Wednesday.

Note that weekends and holidays are excluded from the T+1 rule. That’s because in the U.S.,stock exchanges are open from 9:30am to 4:00pm Eastern time Monday through Friday.

Before the T+1 rule took effect in 2024, the general rule for settlement dates was T+2.

What Investors Need to Know About T+1

The T+1 settlement rule applies uniformly to the trading of stocks, exchange-traded funds (ETFs), and some mutual funds. Bonds — including corporate, municipal, and government debt — also follow this identical timeline, meaning that standard “regular way” transactions across all these major asset classes clear and settle in exactly one business day.

Understanding the difference between the trade date and the settlement date is especially important for investors utilizing a cash account. In a cash account, investors can only trade using fully settled funds that are physically present in the account. In contrast, margin accounts allow investors to borrow funds directly from the brokerage firm to leverage trades or bypass settlement waiting periods by using their existing portfolio as collateral.

Because of these timelines, investors will often see two distinct figures describing the cash balance in their brokerage account: the settled balance and the unsettled balance. Settled cash refers to fully cleared funds that are immediately available for trading or withdrawal. Unsettled cash refers to the proceeds from a recent sale that have not yet legally cleared, but are scheduled to become fully settled on the following business day.

Are T+0, or Real-Time Settlement Dates Possible?

Many market experts are already looking beyond T+1, pushing for the settlement process to move even faster to improve trading conditions.

The momentum to shorten the settlement timeline gained traction following the extreme market volatility of 2020 and 2021. During the famous “meme stock” frenzies, the multi-day settlement delay exposed severe financial risks, forcing clearinghouses to demand billions in collateral from retail brokers. This structural bottleneck is what prompted regulators to accelerate the shift to a one-day cycle.

Moving all the way to T+0, or true real-time settlement, would require formal SEC approval and a large technological overhaul across dozens of Wall Street institutions. However, the instant transactions made possible in the cryptocurrency market by blockchain technology have permanently shifted the conversation, suggesting that real-time traditional securities markets may be a realistic goal for the future.

Potential Violations of the Trade Date vs Settlement Date

Knowing the difference between trade date vs. settlement date can allow investors to avoid potentially costly trading violations.

The consequences of these violations can differ according to which brokerage an investor uses, but the general concept still applies. Violations all have one thing in common: They involve the attempted use of cash or shares that have yet to come under ownership in an investor’s account.

Cash-Liquidation Violation

To buy a security, brokerages typically require investors to have enough settled cash in an account to cover the cost. Trying to buy securities with unsettled cash can lead to a cash-liquidation violation, asliquidating a security to pay for another requires settlement of the first transaction before the other can happen.

Let’s look at a hypothetical example: Say Mira wants to buy $1,000 worth of ABC stock. On Monday, Mira has no settled cash in her account, but she goes ahead and places the buy order anyway. Under the T+1 rule, her purchase of ABC is scheduled to legally settle on Tuesday.

On Tuesday, needing to cover the cost of her purchase, Mira raises funds by selling $1,200 worth of XYZ stock that she already owned.

However, because she sold the XYZ stock on Tuesday, those proceeds will not settle until Wednesday. Since her ABC purchase settled on Tuesday and she lacked the settled cash to cover it on that exact day, a cash-liquidation violation occurred. Investors who face this kind of violation three times in one year can have their accounts restricted for up to 90 days.

Freeriding Violation

A freeriding violation occurs when an investor buys a stock or ETF and then sells that exact same security to pay for the initial purchase before ever depositing the cash required to cover the buy order. Essentially, the investor is trying to pocket a profit without ever risking their own money.

For example, say Jay buys $1,000 worth of ABC stock on Tuesday morning with $0 in his cash account. Under the T+1 rule, Jay must deposit $1,000 in settled cash by Wednesday to pay for the trade. However, later on Tuesday afternoon, ABC stock jumps in value, and Jay sells the shares for $1,100.

Because Jay used the proceeds of the sale to cover the cost of the original purchase instead of depositing his own cash, he committed a freeriding violation. Under Federal Reserve Regulation T, incurring just one freeriding violation results in an immediate 90-day restriction, forcing the investor to trade exclusively with fully settled cash.

Good-Faith Violation

For example, say an investor sells $1,000 worth of ABC stock on Tuesday morning. Later that afternoon, they use those unsettled proceeds to buy $1,000 worth of XYZ stock. This is perfectly legal.

However, if XYZ stock suddenly spikes on Tuesday afternoon and the investor sells the XYZ shares that same day, they will incur a good-faith violation. This is because they sold XYZ before the cash used to buy it (the proceeds from the ABC sale) officially settled on Wednesday morning.

With these examples in mind, it’s not hard for active traders to run into problems if they don’t understand cash-account trading rules, all of which derive from trade date vs. settlement date. Having adequate settled cash in an account can help avoid issues like these.

Settlement Date Risks

Given that a lag exists between the trade date and settlement date, there are risks for traders and investors to be aware of — namely, settlement risk and credit risk.

Settlement Risk

Settlement risk occurs when one party in a transaction fails to deliver on their end of the deal — either by failing to hand over the security or failing to pay for it on the settlement date. In a default scenario, the counterparty faces the risk of financial loss or losing their assets without receiving the agreed-upon payment.

For standard trades on major U.S. stock exchanges, central clearinghouses step in to legally guarantee transactions, effectively eliminating this risk for everyday retail investors. However, settlement risk remains a significant factor in over-the-counter (OTC) markets and foreign exchanges, where competing time zones, cross-border banking delays, and differing regulatory systems make simultaneous settlement much harder to synchronize.

Credit Risk

Credit risk involves potential losses suffered due to a counterparty’s inability to meet their long-term financial obligations. However, when a specific trade is executed and a buyer’s funds are not transferred before the settlement date, this credit risk manifests as settlement risk. When this happens, it causes an immediate interruption in the clearing process and can result in the transaction being canceled altogether.

History of Settlement Dates

The SEC makes the rules regarding how stock markets operate, including trades, and evenwhat a broker does in regard to retail investing. As such, the SEC is tasked with creating the clearance and settlement system — a power it was granted back in the mid-1970s.

Prior to the SEC’s involvement, exchanges and transfers of security ownership were left up to participants, with sellers delivering stock certificates through the mail or even by hand in exchange for payment. That could take a long time, and prices could move a lot, so the SEC came in and set the settlement date at five business days following the trade date.

But as technology has progressed, transactions have been able to execute faster. In 1993, the SEC changed the settlement date to three business days, and in 2017, it was changed to two days. In 2024, it was officially made T+1.

The Takeaway

The trade date is the day an investor or trader books an order to buy or sell a security, and the settlement date is when the legal exchange of ownership actually happens. For many securities in financial markets, the T+1 rule now applies, meaning the settlement date is usually one business day after the trade date — not including weekends or holidays. An investor therefore will not legally own the security until the settlement date.

While there’s been chatter that the settlement process needs to speed up to real-time settlement, it’s still important for investors and traders to know these rules so they don’t make violations that lead to restricted trading or other penalties.

Invest in what matters most to you with SoFi Active Invest. In a self-directed account provided by SoFi Securities, you can trade stocks, exchange-traded funds (ETFs), mutual funds, alternative funds, options, and more — all while paying $0 commission on every trade. Other fees may apply. Whether you want to trade after-hours or manage your portfolio using real-time stock insights and analyst ratings, you can invest your way in SoFi's easy-to-use mobile app.

Invest with as little as $5 with a SoFi Active Investing account.

Options involve substantial risk of loss and the possibility an investor may lose the entire amount invested. Before starting options trading, investors should be familiar with the Characteristics and Risks of Standardized Options . TTax implications with options should be considered. Consult your tax advisor to understand any impacts to your taxes.

FAQ

What’s the difference between trade date and settlement date?

The trade date is the day an investor’s buy or sell order is executed in the market. The settlement date is when the cash and securities legally change hands, making the investor the official owner of the asset. Under current SEC regulations, standard settlement occurs exactly one business day after the trade date (known as T+1).

Is the settlement date the issue date?

No, these are fundamentally different concepts, though they can occasionally overlap. The issue date is the day a brand-new security (like a newly minted bond or an IPO stock) is first created and made available to the public. The settlement date applies to every subsequent trade of that asset on the secondary market, representing the day-to-day completion of individual buy and sell transactions.

Why does it take one day to settle a trade?

Even though electronic trading feels instant, the one-day window is a necessary buffer for the broader financial system. Behind the scenes, individual brokerages, clearinghouses (like the DTCC), and institutional banks must spend that day matching trade details, verifying account funding, moving cash across central banking net systems, and legally transferring security titles between counterparties.

Article Sources


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Mutual Funds (MFs): Investors should read and carefully consider the information contained in the prospectus, which contains the Mutual Fund’s investment objectives, risks, charges, expenses, and other relevant information. You may obtain a prospectus from the Fund company’s website or SoFi's customer service at: 1.855.456.7634. Mutual Funds must be bought and sold at NAV (Net Asset Value); unless otherwise noted in the prospectus, trades are only done once per day after the markets close. Investment returns are subject to risks. Shares may be worth more or less their original value when redeemed. The diversification of a mutual fund will not protect against loss. A mutual fund may not achieve its stated investment objective. Rebalancing and other activities within the fund may have tax implications.

SOIN-Q426-080

Read more
TLS 1.2 Encrypted
Equal Housing Lender