Car insurance forms on a desk.

Different Types of Car Insurance Coverage: Everything You Need to Know

Car insurance protects you financially if you’re in an accident or your car is damaged or stolen. There are several different types of car insurance coverage out there, each of which serves a different purpose. Understanding the ins and outs of these car insurance types is essential to making smart decisions that will effectively protect you, your passengers, and your car.

Key Points

•   A key type of standard auto insurance, liability coverage compensates for damages to others and their property when you’re responsible for an accident.

•   Comprehensive coverage protects you in case of noncollision damage, including vandalism, animal impacts, and natural disasters.

•   Collision coverage covers repair costs for your car after a crash, subject to a deductible.

•   Uninsured/underinsured motorist coverage protects you against financial loss from accidents with inadequately insured drivers.

•   Personal injury protection (PIP) covers medical expenses for you and your passengers after a collision, regardless of who’s at fault.

The Big Three: Standard Car Insurance

There are three main types of auto insurance: liability coverage, collision coverage, and comprehensive coverage. When you’re looking to get auto insurance. It’s important to understand all three. Here’s a closer look at each one.

Recommended: Auto Insurance Terms, Explained

Liability Coverage

Liability coverage helps cover the cost of damages to other people involved in an accident when you are at fault. So, for example, if you were to miss a stop sign and hit an oncoming vehicle, you would generally be considered at fault. Your liability coverage would cover the cost of repairs to the other driver’s car, their medical bills and lost wages, and other related expenses.

Most states require that you have liability coverage, though minimum car insurance coverage requirements will vary. California, for example, requires:

•   $30,000 for injury/death to one person

•   $60,000 for injury/death to more than one person

•   $15,000 for damage to property

New York, on the other hand, has a very different set of requirements:

•   $10,000 for property damage for a single accident

•   $25,000 for bodily injury and $50,000 for death for a person involved in an accident

•   $50,000 for bodily injury and $100,000 for death for two or more people in an accident

You may choose to carry coverage beyond the minimum requirement to protect yourself against costly accidents. If you’re covered for $10,000 in property damage in New York and you cause $20,000 of damage, for instance, your insurance will only pay for $10,000. You’ll have to come up with the rest yourself.

Recommended: No Fault Insurance States

Collision Coverage

As you look at what car insurance covers, collision coverage is key. This type of vehicle insurance helps pay for the cost of repairs for damage to your vehicle if you’re at fault in an accident. It will also help pay for damage if you hit an inanimate object, such as a building, tree, guardrail, or retaining wall.

Collision coverage typically has a deductible that you must pay out of pocket first. Then the insurance kicks in and pays the rest, up to a predetermined limit. For example, if you have a $500 deductible and your car sustains $2,500 in damages, you’ll pay $500 and your insurance will cover the other $2,000.

No state requires collision coverage. But if you have an auto loan or lease, your lender or lessor will likely require you to have it.

There are situations in which you might consider doing without collision coverage. For example, if you own your car outright and it’s not worth much, it may be cheaper to pay out of pocket to repair or replace the car than it would be to pay a monthly premium.

However, if your vehicle is more valuable or you don’t have the money on hand to pay to replace it, you may want to add collision coverage to your policy.

Comprehensive Coverage

Comprehensive coverage helps pay for auto damage that doesn’t result from a collision. That damage could be caused by random incidents such as vandalism, hitting an animal, hailstorms, or a fallen tree branch. Again, if you have an auto loan or lease, those contracts will likely require you to carry comprehensive coverage. Generally, you’ll have to pay a deductible before the policy kicks in.

Recommended: Does Car Insurance Cover Repairs?

Medical and Driver Protections

There are additional types of vehicle insurance for cars that you may want to consider. Some are optional add-ons. Others may be mandatory in your state, so it’s a good idea to check with your Department of Motor Vehicles (DMV) to see what you need.

Uninsured and Underinsured Motorist Coverage

Unfortunately, not everyone on the road carries insurance. Even if they do, they may not carry enough to cover the cost of the damage caused by an accident.

That’s where uninsured and underinsured motorist coverage comes in. Many states mandate uninsured motorist coverage, and several states require both types of insurance. These policies pay when the at-fault party doesn’t carry enough –– or any — insurance to pay for the accident’s costs.

What’s more, if you’re in a hit-and-run accident, you may be able to file a claim on your uninsured coverage. Make sure up front by checking the fine print on any policy you may be considering.

Without uninsured motorist coverage, if you get into an accident with an uninsured or underinsured driver that results in vehicle damage or bodily injury, you might have to pay for car repairs and medical care out of your own pocket.

Get Car Insurance Coverage That's Right for You.

Compare prices and coverage options from a network of top auto insurance providers.


Recommended: Motorcycle Insurance

Personal Injury Protection (PIP)

PIP, also known as no-fault insurance, can help pay the costs associated with personal injury for you and your passengers, including medical expenses, lost wages, disability, rehab costs, death benefits, and related household services, such as child care or cleaning services. PIP covers you no matter who was at fault in the accident. This coverage is mandatory in some states and optional or unavailable in others.

Medical Payments (MedPay) Coverage

Medical payments insurance, also called MedPay, is an optional form of insurance that helps protect you and your passengers by paying for your medical expenses in the event of an accident, no matter who is responsible. In many cases, it may cover you when you’re hit by a car while walking or riding a bike, though policies can vary. Typically, a policy will pay for doctor’s bills, but not other costs such as lost wages, which may be covered by liability insurance if the other party is at fault. Bear in mind, too, that medical payments insurance typically has a limit of $1,000 to $10,000.

Recommended: Does Car Insurance Cover Rentals?

Common Optional Add-Ons

Finally, there are a number of insurance options you can choose to add to your required policies. Whether these make sense for you will depend largely on your individual situation and your level of comfort with risk.

Guaranteed Asset Protection (GAP) Insurance

If you have collision or comprehensive coverage and your car is totaled or stolen, that coverage will typically pay you up to the car’s depreciated value.

But what if you have an auto loan or you lease, and you owe more on the loan than the depreciated value of your car? In that case, gap insurance can kick in and help you pay off your loan.

Rental Car Reimbursement Coverage

Rental reimbursement is optional coverage that may help cover the cost of a rental car after an accident that leaves your own vehicle damaged and inoperable. To add this coverage to your policy, you’ll generally need to carry collision and comprehensive insurance as well.

Without this coverage, you might have to pay out of pocket for a rental car after an accident.

Roadside Assistance Coverage

Many insurance companies offer roadside assistance add-ons, though you may also be able to get roadside assistance from an auto club (such as AAA) or your car manufacturer. Typically, roadside assistance provides help when your car is stranded, offering services like jump-starts, flat tire fixes, aid if you’re locked out, and fuel delivery if you run out of gas, among others. Prices for this insurance add-on typically range from $10 to $60 per year.

Recommended: Switching Your Car Insurance

The Takeaway

Choosing the right car insurance is about protecting yourself financially and ensuring peace of mind while you’re on the road. By understanding the different types of coverage that are available, you can determine how much auto insurance you want and pick a policy to suit your needs and your budget. Revisit your policy regularly to make sure it still provides the type and amount of protection you need, so you can be prepared no matter what happens out on the road.

Having the right auto insurance means knowing you're truly protected — not just checking a legal box. SoFi lets you shop and compare quotes from top carriers in minutes, so you can find coverage that gives you real peace of mind on the road. Explore your coverage options.

SoFi brings you real rates, with no bait and switch.

FAQ

What is “full coverage” car insurance?

“Full coverage” car insurance typically refers to a policy that includes liability, collision, and comprehensive coverage.

Should I get gap car insurance?

If you’ve leased or financed a vehicle, you may want to consider gap insurance. In fact, many lease agreements require it. If you have an auto loan, you might consider gap insurance if you made a small down payment, your loan term is 60 months or longer, or you purchased a car that depreciates quickly.

Do I need both comprehensive and collision coverage?

While you may not be required to have both car insurance coverage types — comprehensive and collision — you may want to consider it anyway. Having both may be especially worth considering if you have a newer car or if you might not be able to pay out of pocket to repair or replace your vehicle.

Is PIP required in my state?

To find out if your state requires PIP, check the website for your state’s Department of Motor Vehicles (DMV).

What happens if I don’t have enough car insurance?

Not having enough car insurance — or the right car insurance coverage types — can put you at financial risk. If you are the at-fault party in an accident and you don’t have enough insurance, you could be on the hook for the remainder of the cost for the damage you caused.


photo credit: iStock/asbe


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOPRO-Q426-032

Read more
A mechanic working on a car in a car shop.

Does Car Insurance Cover Repairs? What Car Owners Should Know

One of the main purposes of your car insurance is to help cover the cost of repairs when your car is damaged in an accident, due to theft or vandalism, or by natural disasters. As this list suggests, standard auto insurance doesn’t cover the cost of all repairs, like those caused by normal wear and tear.

As a policyholder, you’ll want to understand what is covered and what isn’t so you know where to turn when your car needs some TLC.

Key Points

•   Car insurance typically covers repairs from accidents, theft, vandalism, and natural disasters.

•   Routine maintenance, wear and tear, and intentional damage are excluded from standard coverage.

•   Accidents should be documented with photos, videos, and, potentially, police reports for claims.

•   The claims process involves filing with the insurer, an assessment, and approval of repair costs.

•   Mechanical breakdown insurance is an option for covering repairs in older vehicles.

When Insurance Covers Repairs (and When It Doesn’t)

Typically, your car insurance can cover repairs from damage that’s sudden or accidental, such as a car accident or hailstorm. But it’s likely your insurance will deny other types of claims.

Covered by Auto Insurance Not Covered by Auto Insurance
Collision Routine maintenance
Theft Normal wear and tear
Vandalism Mechanical breakdowns/poor maintenance
Natural disaster Intentional damage by owner

Here’s a closer look at what your car insurance covers.

Repairs Covered by Collision and Comprehensive Policies

So, how does your car insurance work? First, it likely comprises several different types of coverage. Through your collision coverage, insurance should pay for repairs for damage caused during a collision with another vehicle, an animal, or stationary objects, such as a tree or guardrail.

Through comprehensive insurance, you should also be covered if your car is stolen or intentionally damaged by another person in an act of vandalism. Damage that occurs during natural disasters, such as fire, floods, hail, or falling debris, is also covered under this type of policy.

Recommended: What Does Liability Auto Insurance Typically Cover?

Repairs Not Covered by Insurance

There’s a long list of things that you shouldn’t expect your insurance to cover. Routine maintenance and general wear and tear are not covered by standard auto insurance. Neither are mechanical breakdowns, such as a failing transmission, or damage done through lack of maintenance, like failing to change your oil. Unfortunately, you’ll have to pay for these repairs on your own.

It may also go without saying that damage you do purposefully to your vehicle is not covered. And if you damage your car while using it for business purposes or performing an illegal activity, your insurance may deny you as well.

What Happens If a Mechanic Damages Your Car?

Your car insurance likely won’t cover mechanic negligence if your car is damaged when a mechanic is making a repair. Typically your first recourse would be to ask the mechanic or garage to make things right by fixing the damage. The costs may be covered by their liability policy.

If they’re unwilling or unable to do so, you might want to try to file a claim with the mechanic’s liability insurer. You can check with your own insurer to see if they’ll help or if you can file a claim with them, too. However, it’s likely that your insurer will cover only certain types of damage — from covered perils.

Something else to check before you file is whether filing will endanger any no-claims discount you might have. Since you would presumably not be at fault, you might be able to retain the benefit, but it’s best to find out in advance.

Understanding Your Deductible’s Role in Repairs

Your collision and comprehensive insurance policies may have a car insurance deductible. This is the amount of money you’ll have to pay before the insurance kicks in. For instance, say a tree branch falls on your car, causing $1,500 in damage. If you have a $500 deductible on your comprehensive policy, you’ll need to pay that first, and your insurance should pay the remaining $1,000.

Recommended: Different Types of Car Insurance Coverage

What About Mechanical Breakdowns?

There is optional coverage generally available that can provide further protection. Mechanical breakdown insurance (MBI) can help protect you from unexpected repairs and breakdowns after your manufacturer’s warranty expires. It’s usually offered as an add-on to your existing insurance policies, but there are also third-party providers who may sell it as a standalone policy.

How This Separate Coverage Fills the Gaps in Standard Policies

Standard policies don’t cover breakdown-related repairs. If you have MBI, it will step in and cover the cost of mechanical failures in major systems such as the engine, transmission, steering, axles, fuel systems, and electrical system. There is typically a deductible that you’ll need to pay first before this add-on kicks in.

Some MBI policies may even include coverage for roadside assistance, which could cover you if your car has to be towed or you’re locked out or your car needs to be jumped. If you’re stranded somewhere far from home, MBI may even cover the cost of lodging or renting a temporary replacement vehicle.

Note that MBI doesn’t cover routine maintenance like oil changes, tune-ups, or brake pads.

Who Should Consider This Type of Coverage?

You might want to consider getting MBI if your car is no longer under factory warranty, since typically your factory warranty should cover the cost of mechanical breakdowns as long as it’s valid. You might also be offered an extended warranty, but it’s worth checking whether mechanical breakdown insurance is cheaper than this option. In general, MBI costs around $100 per year. An extended warranty by comparison, typically costs between $600 and $1,000 per year on average, though it can go to $8,000 or more, depending on factors like the car’s make and year and what exactly the warranty covers.

If you plan to keep your car for a long period of time, MBI may be worth considering, as the likelihood of breakdowns increases as your vehicle ages. Additionally, if you don’t have a high tolerance for risk and you’re worried about large bills for major repairs, this coverage might be worth exploring.

Recommended: How Much Auto Insurance Do You Really Need?

The Process: Filing a Claim for Car Repairs

When covered damage does occur, whether through your standard policies or MBI, you’ll need to file a claim with your insurance company. Your insurer will determine whether the damage is covered and how much it’s willing to pay for the repair.

Steps to Take After Covered Damage Occurs

When damage occurs to your vehicle, your first step should be to document the incident. If the accident involves another driver, get their name, phone number, and insurance information. Take down information about their vehicle as well, including the make, model, and license plate number. And if there were any witnesses, take down their contact information as well.

Take pictures and videos to document the scene of the accident. This will help show what damage was done to your car and to the other person’s vehicle, and it can help capture what the weather and road conditions were like at the time of the accident. It can also be a good idea to get a police report, which can help the claims process move more quickly.

Next, call your insurer and file a claim. You’ll need to provide your policy number, the details of the incident, and the police report, if you have one. An insurance adjuster will then investigate the damage and liability. You’ll likely need to send them the information you gathered documenting the accident.

The adjuster may assess the damage to your vehicle in person or they may have you take your car to a repair shop, which will assess them.

Working With Your Insurer and Repair Shop

After you file a claim, your next step is to get a repair estimate from a body shop. Your insurance company may recommend shops or you can go to the shop of your choosing. You can then submit this estimate to your insurance company.

Next, an adjuster may need to review the estimate and compare it to their own assessment of the damage. If the estimates are similar, your insurer will likely approve the cost. If they’re not, you may need to get additional estimates from other body shops.

Once the estimate is approved, the body shop can start making the repairs. Your insurer may pay the shop directly or issue a payment to you, minus your deductible.

Recommended: Does Car Insurance Cover Rental Cars?

The Takeaway

Does car insurance cover repairs? Your insurance will usually cover the cost of repairs to damage done in an accident or other covered incidents. But it may not cover repairs for mechanical issues or general wear and tear. For that kind of coverage, you might consider mechanical breakdown insurance, which can help pay for certain types of mechanical issues after your vehicle warranty has expired. To help you decide if this coverage makes sense for you, it may be a good idea to review your policy so you understand what it covers and when you might need to be prepared to pay for a repair out of pocket.

Having the right auto insurance means knowing you're truly protected — not just checking a legal box. SoFi lets you shop and compare quotes from top carriers in minutes, so you can find coverage that gives you real peace of mind on the road. Explore your coverage options.

SoFi brings you real rates, with no bait and switch.

FAQ

Does car insurance cover normal wear and tear on my vehicle?

Car insurance can cover many repairs, but it does not cover normal wear and tear on your car, so it’s a good idea to be prepared to cover these expenses yourself. The good news is that they tend to be predictable, so it may be worth establishing a separate savings account to cover your auto repairs.

What’s the difference between collision and comprehensive coverage for repairs?

Collision insurance covers damage to your vehicle caused by a collision with another car or an object. Comprehensive coverage protects you in the event of damage not caused by a collision, such as theft, vandalism, animal damage, and natural disasters.

Will my insurance pay for an engine or transmission failure?

Your standard insurance will typically not pay for engine or transmission failure other than damage incurred during an accident. However, a mechanical breakdown insurance (MBI) policy may cover these costs.

Do I have to use the repair shop my insurance company recommends?

Insurance companies may have a list of repair shops they recommend, but you don’t have to use those options. You can take your car to your own trusted mechanic.

What is mechanical breakdown insurance, and is it worth it?

Mechanical breakdown insurance (MBI) helps cover unexpected mechanical and electrical issues after your vehicle warranty has expired. It’s often cheaper than an extended warranty and may be worthwhile if you plan to keep your vehicle for a long time.

Is a mechanic liable if they damage my car during a repair?

Yes, generally the mechanic or garage is liable. If your vehicle is damaged during a repair, they may fix it or their liability insurer may pay for it to be fixed. If they refuse to fix the damage or are uninsured, your next recourse would be small claims court.


photo credit: iStock/koldo studio


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOPRO-Q426-040

Read more
Two people wearing boots in a flooded apartment.

Does Renters Insurance Cover Floods? What You Need to Know

If you’re a renter, you probably know it’s important to have renters insurance to protect yourself against different kinds of perils. But you may not realize that not all perils are covered. Take, for example, floods.

While renters insurance may pay for water damage from a pipe that bursts unexpectedly or a dishwasher that overflows without warning, it typically doesn’t cover flood damage. If you want that kind of protection, you should consider purchasing a separate flood insurance policy.

Key Points

•   Renters insurance typically does not cover flood damage.

•   Separate flood insurance is generally required for flood protection.

•   The cost of flood insurance varies based on location and coverage limits.

•   A contents-only policy covers up to $100,000 of personal property.

Understanding Flood Damage and Standard Renters Insurance

Renters insurance can protect tenants in a few key ways. It provides financial reimbursement for covered losses to your personal property. It can help protect you if someone is injured while on your rented premises. And some policies will also pay your living expenses if your home is deemed uninhabitable due to damage from a covered peril, like a fire or storm.

Unfortunately, although it’s generally easy to get renters insurance, policies don’t typically cover damage to your rental or belongings that’s caused by a flood. As we mentioned above, for that type of coverage, you’ll need to look into purchasing a flood insurance policy for renters.

Recommended: What Does Flood Insurance Cover?

How Separate Flood Insurance Policies Protect Renters

Renters who live in one of the more than 22,600 participating National Flood Insurance Program (NFIP) communities may be eligible to purchase renters flood insurance. The NFIP is managed by the Federal Emergency Management Agency (FEMA) and is delivered to the public by a network of more than 48 insurance companies and the NFIP Direct.

To purchase flood insurance, you can get a quote with the NFIP Quote Tool available via FloodSmart.gov. Then share the quote with an agent near you, or call your insurance company directly. There’s typically a 30-day waiting period for an NFIP policy to go into effect.

The cost for flood insurance for renters depends on a variety of factors, including whether your rental is located in a flood plain or other high-risk area and what your renters insurance coverage limits are. Living near a body of water within a high-risk area will usually drive flood insurance prices up.

Internal Water Damage vs External Flooding

Renters insurance may differentiate between types of water damage when determining what’s covered. Sudden, accidental internal damage -– from a broken pipe or a leaking washing machine, for instance — are typically covered. External flooding — like damage from a flood or backed-up sewer — will likely not be covered by an average renters insurance policy, though you might be able to purchase additional coverage to protect against such events. Here’s a brief rundown of common water damage events and what would or would not probably be covered by a renters insurance policy.

Type of Water Damage Typically Covered?
Burst plumbing Yes
Overflowing toilet Yes
Leaking appliance Yes
Heavy rain No
Storm surge No
Overflowing river No
Mudslide No

Standard renters insurance policies typically exclude flood damage. Renters insurance often covers water damage from unexpected events inside the building, like burst pipes, leaking appliances, and accidental water discharge from plumbing. As we’ve mentioned, to protect your belongings from flood damage, you’ll need to purchase a separate renters flood insurance policy.

Flood insurance for renters is typically a “contents-only” policy, meaning that only your personal property within the rental unit will be covered. Renters flood insurance can cover up to $100,000 of tenant-owned property in rental units on or above the lowest elevated floor, according to FEMA. This can include things like furniture, clothing, electronics, and other personal items. Coverage for contents below the lowest elevated floor or in a basement or basement apartment is generally limited to a washer, a dryer, and/or a freezer, including the food in it.

Recommended: Does Renters Insurance Cover Water Leak Damage?

Does Renters Insurance Cover Basement Flooding?

Renters insurance typically doesn’t cover basement flooding. If you rent your home and you’re concerned about flooding, there may be other insurance you can buy or add on that will provide some coverage, but it’s wise to make sure you fully understand what exactly you’re signing up for.

Natural Flood Damage to Basements

Natural flood damage is the damage that occurs to basements when water seeps in from an outside source. These sources can include rainstorms, rising bodies of water, or storm surges.

for example. You can buy a separate renters flood insurance policy. This will generally cover your possessions up to the policy limit — but not necessarily in a basement. In a space below the first elevated floor – a basement or underground crawl space, for instance — even flood insurance typically covers only a few major appliances, such as a washer, dryer, and/or freezer.

Sewer Backup and Sump Pump Failures

Generally, renters insurance doesn’t cover damage caused by a backed-up sewer or a failed sump pump. Nor does flood insurance. However, you may be able to purchase a water backup endorsement from your insurer to provide protection from issues like this. Policies may vary in terms of what they cover in the basement, so read the fine print carefully.

Recommended: Does Renters Insurance Cover Temporary Housing?

Protecting Your Belongings From Flood Damage as a Renter

One of the most effective ways to protect your belongings from flood damage as a renter can be having renters flood insurance coverage.

Other proactive measures include moving valuable belongings to higher ground, creating flood barriers like sandbags to block water from entering your rental, and sealing cracks and gaps around windows, doors, pipes, and wires.

If you see appliances or parts of the rental unit that are in need of upkeep, be sure to let your landlord know so that they can be promptly fixed.

What to Do After Experiencing Flood Damage in Your Rental

If a flood is in progress in your rental, immediately turn off the gas, electricity, and central air conditioning and heating to prevent further damage. Then contact your landlord or property manager to inform them about the flood and any damage it caused.

If you have renters flood insurance and want to file a claim, then you should also contact your insurance company to start the claims process. Take photos and videos of the water and the damage to your belongings for insurance purposes.

However, before making the call, it’s helpful to consider the pros and cons of filing. One clear benefit of filing a claim is that, ideally, you’ll receive money for some or all of the costs to fix or replace your items (and, depending on the extent of the damage, perhaps pay for your living expenses while your home is being repaired).

However, you’ll be on the hook for any insurance deductibles. If the only thing that was damaged during the flood was a cheap couch that’s several years old and broken, it might not be worth filing a claim, especially if the insurance company raises your premium afterward. The process can also be time consuming and potentially frustrating.

Recommended: How Much Renters Insurance Do I Need?

The Takeaway

Does renters insurance cover flood damage? While renters insurance generally covers water leak damage from pipes unexpectedly bursting or appliances leaking, water damage from floods will likely not be covered. If you rent in a high-risk flood zone, you’re generally not required to have flood insurance, but it can be a good idea. And keep in mind, floods can still occur outside high-risk flood zones.

Your belongings matter, even if you don't own the space you live in. SoFi makes it simple to find renters insurance that fits your life — so you can feel confident the things you care about are protected. Explore your coverage options.

Explore renters insurance options offered through SoFi.

FAQ

Does renters insurance cover any type of water damage?

Renters insurance does usually cover some types of water damage, such as damage from a pipe unexpectedly bursting or an appliance leaking.

Where can renters buy flood insurance?

Renters who live in a National Flood Insurance Program (NFIP) area may be able to buy flood insurance from one of the more than 48 participating insurance companies. You can get a quote through the online NFIP Quote Tool and then contact the insurance company to purchase the renters flood insurance policy.

What does flood insurance for renters typically cover?

Renters flood insurance can cover up to $100,000 of tenant-owned property in rental units above the lowest elevated floor. This can include things like furniture, clothing, electronics, and other personal items. Coverage for contents below the lowest elevated floor or in a basement or basement apartment is limited to a washer, a dryer, and/or a freezer and the food in it.

Is flood insurance expensive for renters?

The cost of flood insurance for renters depends on a variety of factors, including your renters insurance coverage limits and whether your rental is located in a floodplain or other high-risk area. Living near a body of water within a high-risk area will generally increase the price you pay for flood insurance.

Do I need flood insurance if I don’t live in a high-risk flood zone?

Generally speaking, you’re not required to have flood insurance if you don’t live in a high-risk flood zone, but it’s usually recommended. Floods can still occur outside high-risk flood zones.


Photo credit: iStock/Image Source


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

Non affiliation: SoFi isn’t affiliated with any of the companies highlighted in this article.

SOPRO-Q426-039

Read more
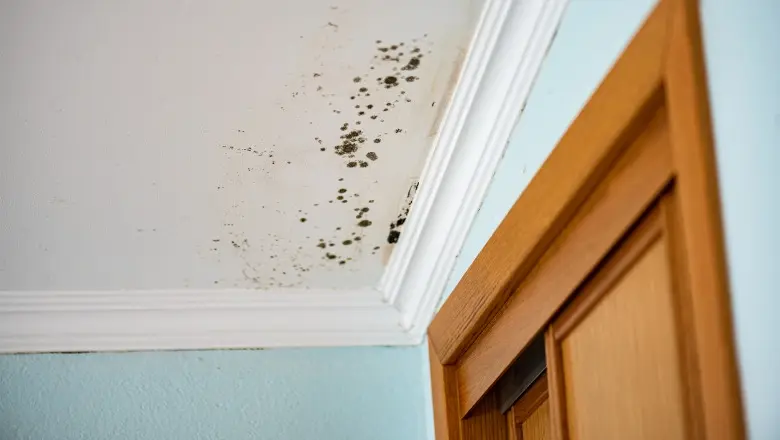
Mold in the upper corner of a room.

Does Renters Insurance Cover Mold Damage?

Renters insurance may cover mold damage but only in certain situations. If the mold is caused by a sudden and accidental event, like a burst pipe or unexpected water leak, your policy could offer some coverage. But if the mold builds up slowly due to factors like long-term leaks, humidity, or poor ventilation, it’s typically not covered.

Here’s what you need to know about renters insurance and mold coverage, what to do if you find mold in your rental unit, and how to protect your belongings from exposure.

Key Points

•   Mold damage can be covered if it’s caused by sudden, accidental events.

•   Long-term mold issues or poor maintenance are generally not covered by renters insurance.

•   It’s smart to notify the landlord immediately upon discovering mold.

•   You may be able to prevent mold with proper humidity management and ventilation.

•   Mold exposure can cause allergy-like symptoms and breathing issues.

Mold Coverage at a Glance

There are some situations that cause mold that may not be covered by insurance. Here are possible scenarios and whether or not they’re likely to be covered by renters insurance.

Covered Scenarios Not Covered Scenarios
Broken pipe or other plumbing failure Neglect or poor maintenance
Broken or overflowing appliance High humidity/condensation
Water damage from firefighting External flooding
Water leaking from a unit above Sump pump or sewer backup

Recommended: Does Renters Insurance Cover Car Theft?

When Does Renters Insurance Cover Mold Damage?

Generally, renters insurance may cover mold damage as long as it results from a covered peril. Typical examples include water damage from a burst pipe or a malfunctioning appliance. In these situations, your policy may help pay to repair or replace your personal items like rugs, clothes, or furniture, after you pay your deductible and up to your policy limits.

Your policy’s loss of use coverage may also come into play to help cover temporary living expenses if the mold damage makes your rental unlivable. This might include hotel stays, meals, and other added costs while your home is being repaired.

When Does Renters Insurance Not Cover Mold Damage?

Renters insurance usually doesn’t cover mold caused by long-term issues or poor upkeep. For example, if you leave a window open during a storm and mold develops, your policy likely won’t help pay for the cleanup or replacing your belongings.

Sometimes, though, mold can appear because your landlord fails to maintain the property— for example, if they ignore a leak. Renters insurance typically won’t help with restoring or rebuilding parts of the unit. However, your landlord may be responsible for fixing the problem and covering damages to your belongings.

It’s also important to know that mold caused by flooding or sewer backup usually isn’t covered either. Purchasing separate flood insurance can help you protect your belongings in the event of a flood. If a sewer issue causes mold, it’s a good idea to reach out to your landlord promptly for next steps.

Recommended: How Much Renters Insurance Do I Need?

How Much Coverage Does Renters Insurance Provide for Mold?

As long as the mold is tied to a covered peril, your renters insurance could help you recover at least some of the cost of your personal property. The amount you’re eligible for, though, depends on your personal property coverage, which usually ranges from $10,000 to $100,000.

Consider choosing a coverage amount that matches the total value of your belongings. For example, if your policy includes $10,000 in personal property coverage and your claim is approved, you could be reimbursed up to that amount, minus your deductible. But if your belongings are worth more, you may want a higher coverage amount.

If the mold forces you to move out, your policy’s loss of use coverage may help cover extra living expenses for the short term. This type of insurance usually comes as either a flat amount, such as $3,000 to $5,000, or a percentage of your personal property coverage. So if your policy covers up to $10,000 in personal belongings and includes 40% loss of use coverage, you could have up to $4,000 for hotel stays, meals, and other temporary costs.

Mold-Specific Coverage Limits and Endorsements

As mentioned above, renters insurance will only cover mold damage in certain cases. But additionally, renters insurance policies may have coverage limits specific to costs related to mold-damaged belongings and mold remediation. These limits can range widely, but $5,000 or less is typical. Some insurance companies offer endorsements that you can opt to buy if you want to increase how much protection you have against mold damage and/or to help with the costs of mold cleanup.

Recommended: How to Get Renters Insurance

Preventing Mold Growth in Your Rental

Here’s the thing about mold: It can spread quickly. In fact, once it finds a damp area, it can start growing in just a day or two. You might notice a musty smell before you see signs of mold, but sometimes, there’s no smell at all. That’s why it’s important to keep an eye on your space, take care of any moisture right away, and understand what you’re responsible for—and what your landlord should handle.

As a tenant, your job is to keep your rental clean and well-ventilated — and to act quickly when you notice something isn’t right. So with that in mind here are some simple ways you can help prevent mold from showing up in your rental, according to the Centers for Disease Control and Prevention:

•   Keep surfaces dry. Pay attention to moisture in bathrooms, kitchens, and basements. Wipe up spills, and report leaks as soon as you spot them.

•   Manage humidity. Use fans or dehumidifiers in your space, especially if you live in a humid climate. Aim to keep indoor humidity between 30–50%.

•   Ventilate your space: Use bathroom and kitchen fans when cooking or showering. And open windows when the weather allows.

•   Act fast: If you smell something musty or see signs of mold, don’t wait. Let your landlord know right away.

Remember, it’s your landlord’s responsibility to make sure the place is safe to live in, which means fixing leaks, taking care of water damage, and helping prevent mold. They should also get the property inspected when needed and let you know if there’s been an issue with mold before. If you report a problem and your landlord doesn’t do anything about it, they could be responsible for any damage or health issues that arise because of it.

Understanding the Health Risks of Mold

Everyone reacts to mold differently. Many people who are exposed to it experience allergy-like symptoms or irritation, including:

•   Stuffy nose or sinus pressure

•   Itchy, red, or watery eyes

•   Breathing issues like wheezing, coughing, or shortness of breath

•   Sore or scratchy throat

•   Skin irritation or rashes

•   Headaches

Though it’s rare, mold exposure can sometimes lead to infections or illness. This is more common among people with weakened immune systems or chronic lung problems.

What to Do If You Find Mold in Your Rental

Mold can look fuzzy, slimy, or discolored, and it usually smells musty. You can typically find it in damp areas like bathrooms or kitchens and around windows. Look carefully, and don’t forget to check behind carpets, wallpaper, and cabinets or inside closets.

If you end up spotting mold — or even just smell something musty — you’ll want to take swift action. Remember, this stuff grows quickly!

Here are some steps to take:

•   Tell your landlord right away: As soon as you notice mold (or anything that could lead to mold, like a leak), contact your landlord or property manager. It’s their responsibility to fix the issue.

•   Stop further damage: If a broken pipe or appliance is causing the problem, shut off the water source if it’s safe to do so. Taking action right away can help prevent more damage to your home and belongings.

•   Document everything: Take clear photos and videos of the mold and any damage it caused. Write down the date you found it and what you reported. Keeping a paper trail is helpful in case things escalate or you need to break your lease.

•   Check local laws: Some states require landlords to respond within a certain time frame. Look up your state’s mold laws so you know your rights and can take action if needed.

•   Start an insurance claim if needed: If your belongings are damaged or you have to move out while repairs are made, contact your renters insurance provider. The agent will explain what your policy covers and guide you through the claims process.

Recommended: Cheapest Renters Insurance Companies

The Takeaway

Renters insurance may help cover mold damage, but only if the mold was caused by something your policy covers, like a burst pipe or sudden leak. Coverage usually comes with limits and exclusions, so it’s smart to review your policy and ask your insurer what’s included.

Also, keep in mind that renters insurance only covers your personal belongings and, potentially, whatever personal expenses you incur if you have to live elsewhere while mold repairs are being done. Coverage doesn’t extend to the rental unit itself. That’s your landlord’s responsibility, so it’s worth checking that they’re handling repairs and have the right coverage in place.

Your belongings matter, even if you don't own the space you live in. SoFi makes it simple to find renters insurance that fits your life — so you can feel confident the things you care about are protected. Explore your coverage options.

Explore renters insurance options offered through SoFi.

FAQ

If a burst pipe causes mold on my furniture, is the furniture covered?

It might be. If the mold on your furniture was caused by a cracked water line — a situation typically covered by renters insurance — your policy may help pay to repair or replace the damaged items. Just make sure to check your coverage limits and deductible to understand how much you could be reimbursed.

Does renters insurance pay for mold removal from walls or ceilings?

No, renters insurance typically doesn’t cover the structure of your rental unit, including walls or ceilings. That’s your landlord’s responsibility. If the mold was caused by something like sudden pipe failure or accidental bathtub overflow — a covered event — your landlord is usually in charge of handling the repairs and cleanup. Renters insurance is designed to protect your personal belongings, not the building itself.

Is mold caused by high humidity or condensation covered?

Usually not. For renters insurance to cover mold damage, it has to be caused by something your policy specifically covers, like an appliance leak. Mold that forms from high humidity or everyday condensation isn’t typically covered, since those issues are considered preventable with regular upkeep.

What if my landlord is responsible for fixing the mold source?

If the mold is caused by something your landlord should have repaired, such as a leak or plumbing issue, then they’re likely responsible for fixing the problem and cleaning up the mold. Landlord duties vary by state, so it’s a good idea to check your local laws or contact your local housing authority to understand your rights. In some states, like California, there are specific rules about how landlords must handle mold in rentals.

Does my policy cover hotel costs if mold makes my apartment unlivable?

It might, depending on what caused the mold. Renters insurance may include loss of use coverage, which can help pay for hotel stays, meals, and other living expenses if your place becomes unlivable during repairs, up to policy limits. However, the mold must be caused by something your policy covers, like a sudden roof leak or water damage from a broken washing machine hose. Check your policy details or talk to your insurer to see what’s included in your policy.


Photo credit: iStock/Rocky89


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.
Non affiliation: SoFi isn’t affiliated with any of the companies highlighted in this article.

SOPRO-Q426-038

Read more
A smiling woman and her happy golden retriever enjoy a car ride, underscoring the importance of uninsured motorist coverage.

What Is Uninsured Motorist Coverage?

Uninsured motorist coverage shields you from having to pay for injuries and property damage in accidents that weren’t your fault and were caused by an uninsured driver.

According to the Insurance Research Council, 15.4% of motorists on the road are uninsured. Purchasing auto insurance for uninsured drivers coverage reduces the likelihood that you’ll have to pay out of pocket if you’re involved in an accident caused by one of these irresponsible drivers.

It’s generally a good idea to add uninsured motorist coverage to your auto insurance policy, as it’s fairly inexpensive, usually only costing about an extra $14 or so a month, per vehicle, for policyholders with clean driving histories. Below, we give you the scoop on the different kinds of uninsured motorist coverage and what these policies entail.

Key Points

•   Uninsured motorist coverage protects against financial losses from accidents caused by uninsured drivers.

•   Auto insurance for uninsured drivers coverage can include bodily injury and property damage, addressing medical and repair costs.

•   Coverage limits are typically set per person and per accident, such as 100,000/300,000.

•   Underinsured motorist coverage covers the gap when the at-fault driver’s insurance is insufficient.

•   State requirements for uninsured motorist coverage vary, with some mandating it and others not.

Breaking Down Uninsured Motorist Coverage Variations

Uninsured motorist insurance coverage is a type of car insurance coverage. There are two main kinds of uninsured motorist coverage. Much as your standard auto insurance policy has collision and bodily injury coverage, this kind of policy breaks down into uninsured motorist bodily injury (UMBI) coverage and uninsured motorist property damage (UMPD) coverage.

•   Uninsured motorist bodily injury coverage: Covers your party’s medical expenses and related costs in accidents caused by uninsured drivers.

•   Uninsured motorist property damage coverage: Covers your repair bills and related costs in accidents caused by uninsured drivers.

Bodily injury and property damage coverage for uninsured motorists are sometimes packaged and sold together when you purchase uninsured motorist insurance. However, this isn’t the case with all policies, so check with your insurance provider to know for sure. Now let’s take a closer look at each of these kinds of coverage.

Get Car Insurance Coverage That's Right for You.

Compare prices and coverage options from a network of top auto insurance providers.


Types of Uninsured Motorist Coverage at a Glance

The chart below provides a quick overview.

Coverage Type What It Covers What It Pays For
Uninsured motorist bodily injury (UMBI) Medical and related expenses from accidents caused by uninsured drivers Medical bills, lost wages, pain and suffering, funeral expenses
Uninsured motorist property damage (UMPD) Repairs and related expenses from accidents caused by uninsured drivers Car repair bills, costs of other property damaged by the accident

Uninsured Motorist Bodily Injury Coverage (UMBI)

Uninsured motorist bodily injury coverage (UMBI) pays for the cost of medical bills, lost wages, pain and suffering, and funeral costs (though we hope that’s not needed) in the event an uninsured driver causes an accident in which you’re the victim.

In some instances, this policy may pay out if you, as a pedestrian or bicyclist, are involved in an accident caused by an uninsured driver. Check with your car insurance provider to confirm whether this might be covered.

UMBI typically does not have a deductible to meet, so you would generally get full reimbursement of the costs.

Uninsured Motorist Property Damage Coverage (UMPD)

Uninsured motorist property damage coverage pays for the cost of repair bills for either your vehicle or property in the event either is involved in an accident caused by an uninsured driver.

Unlike bodily injury coverage, UMPD often requires the payment of a deductible when used. This is usually set by state law and typically is between $100 and $1,000.

Remember that what’s covered by auto insurance of any kind also depends on your individual policy and its terms.

Recommended: How Does Car Insurance Work?

How an Uninsured Motorist Claim Works

Rather than waiting until an accident happens to try to figure out what to do, it can be helpful to know in advance what exactly the process is like. Below, you can find a step-by-step breakdown.

Step 1: The Accident Happens

When your car is hit, the first thing to do is to check whether you and your passengers, if any, have sustained any physical injuries. If so, you’ll need to call emergency medical aid – and either way, you should call the police since you’ll want there to be an official verification of the incident. If it’s safe to do so and makes sense, you may want to move your vehicle out of traffic and turn on your hazard lights. It’s also helpful to take pictures of the damage and the location if you can do it safely.

Step 2: The At-Fault Driver Can’t Pay

Once things are secure, you’ll need to confer with the other driver. If you find out that they are uninsured, you’ll want to get their name and address, driver’s license number, license plate information, and the year and make of their vehicle, as well as give them yours. If the driver leaves the scene, the accident is considered a hit-and-run, which is typically treated as an uninsured driver incident in most states.

Step 3: You File a Claim With Your Own Insurer

Let your insurer know as soon as possible about the accident. Make sure they get the information about the uninsured driver, a copy of the police report, and any other details or documentation you can provide about the accident, including your photos and notes.

Recommended: Motorcycle Insurance

Uninsured vs Underinsured Motorist Coverage

There’s another kind of coverage you should know about – underinsured motorist coverage. Underinsured motorist coverage helps cover your costs if you’re involved in an accident where the party at fault has insufficient insurance coverage to pay for your medical costs or property damage.

Underinsured motorist coverage differs from uninsured motorist coverage in that it’s designed to cover any shortfalls in your costs due to the underinsured motorist’s inadequate insurance policy. By contrast, uninsured motorist coverage covers your bills due to the uninsured driver’s failure to purchase insurance.

Similar to uninsured motorist coverage, underinsured motorist coverage also comes in bodily injury and property damage variants. Both bodily injury and property damage coverage is usually packaged and sold together, though insurance policies may vary.

Underinsured motorist coverage is sold separately from uninsured motorist coverage, and states can have different coverage requirements for each. Check with your insurance provider to verify whether you need to purchase these separately.

Uninsured Motorist Coverage Limits

When it comes to uninsured driver coverage, an important insurance term to understand is coverage limits. Your auto insurance quote will typically break down your uninsured motorist coverage limits into two numbers: a smaller dollar figure followed by a larger dollar figure, separated by a slash. For example, $100,000/$300,000.

This can also be expressed as follows:

•   $100,000 per person

•   $300,000 per accident

These two numbers represent the per person and per accident coverage limits of your uninsured motorist insurance. The per person limit is the maximum your insurance company will pay for any single individual injured in a covered accident. Conversely, the per accident limit is the maximum your insurance company will pay for a covered accident, regardless of how many injured people are in your party.

How Uninsured Motorist Coverage Limits Work

Now let’s spell out how this coverage would work, using this $100,000/$300,000 example. If you have a family of five that’s riding in a car that gets hit by an uninsured driver, the maximum amount your insurance company will pay for their cumulative medical bills is $300,000, despite each individual’s coverage limit being $100,000.

If you’re ever involved in an accident caused by an uninsured driver where your costs exceed your coverage limits, in most cases, your health insurance policy will kick in on medical bills to help cover the balance. Consult your insurance providers for the specifics on your policies.

Recommended: How Much Auto Insurance Do I Really Need?

How Much Uninsured Motorist Coverage Do I Need?

The answer depends on whether your state requires uninsured motorist coverage. If it does, you must buy at least the state’s minimum (for more details, see below). Typically, this amount will match your liability coverage amounts. If your state doesn’t require this kind of coverage, consider variables like the health care costs in your state and how much your vehicle is worth. Generally, uninsured motorist coverage is fairly affordable and can be a worthy investment for some peace of mind.

According to the Insurance Research Council, more than one in seven drivers on the road are uninsured. This figure is even higher in states like Mississippi, where more than 28% of drivers on the road are estimated to be uninsured.

Based on those figures, residents of higher-risk states may be well served by purchasing uninsured motorist coverage. Conversely, it might not be as high a priority for residents of lower-risk states, like Maine and Utah, where 5.7% and 6.2% of drivers respectively are estimated to be uninsured.

Now, let’s circle back to the states that do require this kind of policy. The table below lists the regulations regarding the minimum required uninsured and underinsured driver insurance coverage for each state.

Recommended: What Does Liability Auto Insurance Typically Cover?

Uninsured/Underinsured Motorist Coverage Requirements by State

Let’s take a look at the guidelines in every state, so you can see how much coverage may be required where you live. In each category, the amount shown is per person/per accident. When there is not a figure in an area of the chart, that means the insurance isn’t required.

State Uninsured Bodily Injury Uninsured Property Damage Underinsured Bodily Injury Underinsured Property Damage
Alabama
Alaska
Arizona
Arkansas
California
Colorado
Connecticut $25,000/$50,000 $25,000/$50,000
Delaware
District of Columbia $25,000/$50,000 $5,000
Florida
Georgia
Hawaii
Idaho
Illinois $25,000/$50,000
Indiana
Iowa
Kansas $25,000/$50,000 $25,000/$50,000
Kentucky
Louisiana
Maine $50,000/$100,000 $50,000/$100,000
Maryland $30,000/$60,000 $15,000 $30,000/$60,000 $15,000
Massachusetts $25,000/$50,000
Michigan
Minnesota $25,000/$50,000 $25,000/$50,000
Mississippi
Missouri $25,000/$50,000
Montana
Nebraska $25,000/$50,000 $25,000/$50,000
Nevada
New Hampshire* $25,000/$50,000 $25,000 $25,000/$50,000 $25,000
New Jersey $35,000/$70,000 $25,000 $35,000/$70,000 $25,000
New Mexico
New York $25,000/$50,000 $25,000/$50,000
North Carolina $50,000/$100,000 $50,000 $50,000/$100,000 $50,000
North Dakota $25,000/$50,000 $25,000/$50,000
Ohio
Oklahoma
Oregon $25,000/$50,000 $25,000/$50,000
Pennsylvania
Rhode Island
South Carolina $25,000/$50,000 $25,000
South Dakota $25,000/$50,000 $25,000/$50,000
Tennessee
Texas
Utah
Vermont $50,000/$100,000 $10,000 $50,000/$100,000 $10,000
Virginia* $50,000/$100,000 $25,000 $50,000/ $100,000 $25,000
Washington
West Virginia $25,000/$50,000 $25,000
Wisconsin $25,000/$50,000
Wyoming

*New Hampshire does not require drivers to purchase auto insurance, but drivers who do choose to purchase auto insurance must have at least the minimum uninsured/underinsured motorist coverage amounts listed.

Recommended: 5 Steps to Switching Your Car Insurance

How Much Does Uninsured Motorist Coverage Cost?

Depending on how much uninsured motorist coverage you choose to purchase and your personal driving habits, your cost for uninsured motorist coverage could be as little as $5 to $10 per month. This figure also tends to vary widely based on the overall percentage of uninsured motorists in your area, according to national insurance data.

Insurance premiums vary widely across drivers, states, and even insurance providers, so make sure you check around for a personalized quote.

The Takeaway

The prospect of being in an accident caused by an uninsured driver is a real concern, given the number of these motorists on the road. Adding uninsured motorist coverage to your auto insurance policy may be a good idea. In some states, it may even be required by law. For a relatively low cost, you can protect yourself from the possibility of being left with bills because another driver didn’t have insurance. The right package of car insurance policies is one way to protect yourself from unexpected circumstances.

Having the right auto insurance means knowing you're truly protected — not just checking a legal box. SoFi lets you shop and compare quotes from top carriers in minutes, so you can find coverage that gives you real peace of mind on the road. Explore your coverage options.

SoFi brings you real rates, with no bait and switch.

FAQ

Do I need UMPD if I already have collision coverage?

Not necessarily, unless your state mandates it. However, deductibles on collision policies are typically higher than those for uninsured motorist property damage (UMPD), so if you have both you may be able to pay less before your insurance kicks in.

Does uninsured motorist coverage cover hit-and-run accidents?

Generally, uninsured motorist bodily injury (UMBI) policies will cover you for medical costs in the case of a hit-and-run. However, some states will not allow you to file for uninsured motorist property damage (UMPD) in the case of a hit-and-run.

Am I required to carry uninsured motorist coverage, or can I decline it?

Whether you’re required to carry uninsured driver coverage depends on what state you’re licensed in. You can check with your Department of Motor Vehicles (DMV) to determine the requirements where you are.

Can I sue an uninsured driver instead of filing an insurance claim?

Yes, you have the right to sue an uninsured driver instead of filing an insurance claim. Bear in mind that practically, you would only be able to sue if the hit-and-run driver was located by law enforcement. And it’s also important to remember that even if the court decides in your favor, the driver might not have the financial assets to pay.

Does uninsured motorist coverage protect pedestrians and cyclists?

Generally, if you’re hit by an uninsured motorist when you’re walking or riding a bicycle, your uninsured driver insurance coverage will cover you. There can be exceptions, conditions, and exclusions, so you may want to check with your insurer to verify your situation.


Photo credit: iStock/RyanJLane


This content is for educational and informational purposes only. The products, services, or features discussed may not currently be available via the SoFi platform. Any references to third-party products, services, or companies do not constitute an endorsement, recommendation, or solicitation by SoFi. Readers should independently evaluate their options and consider their individual financial needs and circumstances before making any decisions. ©2026 SoFi Technologies, Inc. All rights reserved.

SOPRO-Q426-033

Read more
TLS 1.2 Encrypted
Equal Housing Lender